

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Special Category Semi-trailer Market: Why 5.48% CAGR Changes Everything

Strategic Shifts and Commercial Opportunities in the Worldwide Special Category Semi-trailer Market
The worldwide special category semi-trailer market has entered a phase of structural expansion, driven by the need to move oversized, temperature-sensitive, and hazardous cargo across increasingly complex supply chains. Valued at approximately USD 20.96 billion in 2025, the market has grown consistently from a base of roughly USD 16.5 billion in 2020, reflecting a compound annual growth rate of 5.48 percent through 2032. By the end of the forecast period, revenue is projected to approach USD 30.45 billion, signaling durable demand rather than a cyclical upturn. This trajectory underscores a fundamental shift in how heavy and specialized freight is mobilized globally, with manufacturers and fleet operators alike recalibrating capacity, materials, and product architecture to meet evolving operational realities.
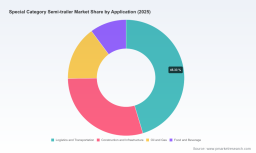
Behind the headline growth figures lies a landscape defined by uneven regional momentum and product-level divergence. North America, Europe, and Asia Pacific collectively anchor the largest revenue pools, each shaped by distinct infrastructure maturity, regulatory intensity, and industrial demand profiles. Product categories spanning lowboy, refrigerated, tanker, car carrier, and logging configurations continue to coexist, but their growth trajectories are increasingly decoupled. The market is not growing uniformly; instead, it is being reshaped by application-specific requirements, where logistics and transportation, construction and infrastructure, oil and gas, and food and beverage sectors each impose different payload, durability, and compliance expectations.
Several critical challenges and inflection points define the current market environment. First, the industry is navigating a tightening regulatory perimeter around emissions and safety standards, forcing manufacturers to reconsider powertrain-adjacent design choices and component selection even for non-propelled trailer assets. Second, raw material economics have become a persistent source of margin pressure and strategic trade-offs, as producers balance weight reduction benefits against cost premiums and embedded carbon considerations. Third, the market is experiencing a gradual bifurcation between standardized volume production and highly customized special-category solutions, creating operational complexity for OEMs that must serve both segments without diluting expertise or scale advantages. These dynamics are not temporary friction points; they are reshaping competitive positioning and investment priorities across the value chain.
Core Drivers Reshaping Market Trajectory
Technological innovation is moving beyond incremental improvements and beginning to redefine what special category semi-trailers can deliver in terms of payload efficiency, safety, and operational visibility. Advancements in high-strength steel alloys and engineered aluminum formulations are enabling lighter yet structurally robust configurations, allowing operators to maximize legal payloads without compromising durability. At the same time, integration of telematics, load-sensing systems, and modular coupling architectures is transforming trailers from passive cargo carriers into data-enabled components of smarter freight networks. These capabilities are particularly valuable in special category applications, where load stability, route constraints, and configuration flexibility directly influence utilization rates and total cost of ownership.
The regulatory environment is exerting a parallel and equally powerful influence. Environmental mandates targeting heavy-duty transport are increasingly extending their reach into trailer design and material choices, even when the trailer itself does not generate propulsion emissions. Standards governing braking performance, lighting, structural integrity, and safe operation continue to raise the baseline for market entry, while emissions-related frameworks are nudging manufacturers toward materials and designs that support broader fleet efficiency goals. Compliance is no longer a checkbox exercise; it is becoming a design constraint that rewards early adopters of lighter, more efficient, and easier-to-integrate special category platforms.
PW Consulting
Demand-side behavior is shifting as freight networks prioritize reliability, speed, and cargo integrity across longer and more fragmented routes. Logistics and transportation operators are expanding their reliance on specialized equipment to handle complex multimodal movements, while construction and infrastructure activity is sustaining demand for heavy-lift and low-clearance configurations. Simultaneously, temperature-sensitive and high-value cargo flows are reinforcing the role of refrigerated and secure carrier formats. Buyers are increasingly evaluating trailers not just on acquisition cost but on lifecycle performance, downtime risk, and compatibility with evolving fleet management practices. This evaluation shift is pushing manufacturers to articulate value through durability, configurability, and service support rather than price alone.
Specialty Tire Market
Supply chain and cost structure dynamics complete the driver set. Material availability, energy costs, and production localization decisions are reshaping manufacturing economics, particularly for high-specification special category units that require specialized fabrication and quality control. The relative cost of aluminum versus steel remains a recurring strategic consideration, with aluminum offering measurable weight and payload advantages while carrying a higher upfront price and a materially larger carbon footprint per kilogram produced. In parallel, regional production footprints are being revisited as OEMs seek to reduce lead times, respond to local compliance requirements, and better serve fragmented demand pockets. These supply-side pressures are encouraging more modular design approaches, selective material substitution, and closer alignment between manufacturing capacity and end-market demand clusters.
Competitive Landscape and Leading Strategies
The competitive field in the special category semi-trailer market is defined by a mix of large-scale multinational OEMs and specialized manufacturers with deep application expertise. Companies such as CIMC Vehicles, Schmitz Cargobull AG, Krone Commercial Vehicle Group, Wabash National Corporation, Great Dane LLC, Hyundai Translead, and Kässbohrer occupy prominent positions by combining broad product portfolios with regional manufacturing strength and established aftermarket support. Their scale enables them to serve high-volume logistics segments while maintaining dedicated lines for heavy haul, temperature-controlled, and custom configurations. At the same time, a second tier of specialist producers—including Miller Industries, Cottrell, Faymonville/MAX Trailer, Nooteboom Trailers, Goldhofer, Landoll, Boydstun, and Heil Trailer International—competes on niche proficiency, often winning demand in vehicle transport, car hauling, extendible lowbed, and liquid or dry bulk applications where engineering specificity and operational familiarity carry outsized weight.
Leading players are differentiating through a combination of product breadth, regional responsiveness, and capability depth rather than through price competition alone. Global-scale OEMs lean on standardized platforms, broad service networks, and the ability to offer multiple special category variants from shared manufacturing logic, which helps manage cost while preserving configuration flexibility. Specialist manufacturers, by contrast, often compete by tailoring structural layouts, axle arrangements, and coupling systems to very specific load profiles and route conditions. This dual structure creates a market where scale and specialization coexist, and where the most resilient brands are those that can move between volume-oriented production and highly engineered custom builds without losing quality control or delivery predictability.
Recent market developments point to a landscape that is becoming more transparent, more regionally nuanced, and more responsive to near-term demand signals. Global OEM rankings based on confirmed production output have drawn sharper attention to relative scale and capacity utilization, giving buyers and investors a clearer reference point for manufacturing leadership. At the same time, regional manufacturers are reinforcing their positioning by emphasizing durability, compliance, and service availability for both domestic and export markets. New model-year listings for specialized variants, including paver and heavy-duty configurations, indicate that product refresh cycles and application-specific availability remain key tools for capturing demand in segmented verticals. These signals suggest that competitive advantage is increasingly tied to the ability to align production readiness with localized demand timing.
The market structure is evolving along two intersecting paths: consolidation at the scale end and persistent fragmentation at the specialist end. Larger groups are well placed to absorb compliance costs, invest in material and design innovation, and expand service coverage across regions, which can pressure smaller competitors that lack capital flexibility or geographic reach. Yet the long tail of specialized demand continues to support smaller, highly focused manufacturers that can iterate quickly on custom configurations and build deep relationships in narrow application segments. New entrants are most likely to succeed where they can combine a clear application focus with reliable compliance, cost-competitive material strategies, and credible after-sales support. For incumbents, the strategic question is not whether to pursue scale or specialization, but how to organize both within a single operating model that can switch efficiently between standardized output and custom engineering.
Forward Outlook: Trends Shaping the Next Three to Five Years
One of the most consequential trends ahead is the continued integration of material and design innovation with regulatory and efficiency pressures. As emissions-related standards for heavy-duty transport tighten and fleet operators look for every available lever to improve utilization and reduce operating cost, lighter and more structurally efficient special category trailers will gain preference in many applications. Expect greater experimentation with mixed-material architectures, higher-strength steel grades, and selective aluminum use where payload or fuel-efficiency gains justify the cost premium. The commercial opportunity lies in offering modular, application-tuned platforms that let buyers balance weight, durability, and total cost of ownership without committing to a single material philosophy across the entire fleet.
Semitrailer (Semi-Trailer) Market
A second trend is the growing importance of configuration agility and regional production alignment. Demand for special category equipment is unlikely to homogenize; instead, it will continue to cluster around specific industrial corridors, resource projects, and logistics hubs. Manufacturers that can tailor axle layouts, deck heights, tank formats, and carrier adaptations to local requirements—while maintaining repeatable quality and reasonable lead times—will capture disproportionate share in high-value segments. This creates an opening for producers that invest in flexible fabrication, regional service presence, and rapid customization workflows, especially in markets where infrastructure projects, energy activity, or temperature-controlled freight are expanding faster than the broader fleet base.
A third trend is the gradual shift from equipment purchase decisions to lifecycle and compliance-aware procurement. Buyers are increasingly weighing safety standards, emissions-linked material implications, maintenance access, and integration with fleet data systems when selecting special category semi-trailers. This creates room for manufacturers and suppliers that can demonstrate transparent performance characteristics, predictable service intervals, and compatibility with broader operational management tools. The associated risk is that misalignment between product design and future compliance expectations could erode competitiveness, particularly if standards converge in ways that favor lighter, more efficient, and more easily certified configurations. Uncertainty around material costs, regional demand pacing, and the exact timing of regulatory effects will require scenario-based planning rather than fixed long-term commitments.
Actionable Priorities for Decision-Makers
For manufacturers, the immediate priority is to strengthen the balance between scale efficiency and application-specific engineering. That means investing in modular platforms, clarifying material strategies in light of both cost and carbon considerations, and building production flexibility that can absorb regional demand swings without sacrificing delivery reliability. Firms that can demonstrate credible compliance readiness, predictable customization lead times, and strong service coverage will be better positioned to defend margins as competition intensifies around differentiated capability rather than base pricing.
For investors, the most relevant signal is that growth is concentrated in specific product and application pockets rather than distributed evenly across the market. Capital allocation should favor producers with clear positioning in high-demand special categories, durable regional manufacturing footprints, and the operational discipline to manage material cost volatility. Diversification into adjacent service, aftermarket, and configuration-support capabilities can also provide resilience when new equipment cycles slow or when procurement shifts toward lifecycle value.
For procurement teams and fleet operators, the strategic imperative is to evaluate special category semi-trailers as long-term operational assets rather than short-term cost items. Decisions should incorporate payload efficiency, compliance trajectory, material trade-offs, and service accessibility alongside acquisition price, with particular attention to how equipment choices align with anticipated cargo mix and route complexity. Given the pace of regulatory, material, and demand-side change, access to granular segmentation data and scenario-based market intelligence is increasingly valuable for reducing procurement risk and timing capacity decisions more effectively. For organizations seeking a deeper dive into segment-level dynamics, regional comparisons, and tailored strategic implications, the full research report provides the detailed breakdown needed to translate these trends into operational and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Special Category Semi-trailer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com