

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Diethyl Chlorophosphate Market: Why 5.03% CAGR and Asia Pacific’s 94M Shift Redefine Growth

Strategic Trends and Commercial Opportunities in the Worldwide Diethyl Chlorophosphate Market
The global diethyl chlorophosphate market has evolved into a specialized yet strategically vital segment within the broader organophosphorus chemicals landscape. Valued at approximately USD 205.0 million in 2025, the market reflects a compound annual growth rate of 5.03 percent from 2020 through 2032, translating into a projected valuation of nearly USD 289.0 million by the end of the forecast period. This trajectory indicates steady expansion rather than speculative volatility, underpinned by sustained demand across chemical synthesis, flame retardant manufacturing, and agrochemical production. The market has demonstrated resilience through recent macroeconomic fluctuations, with 2024 recording a notable recovery to USD 196.6 million following a temporary contraction in 2023. Such patterns underscore an industry that is structurally anchored yet sensitive to input cost dynamics, regulatory shifts, and regional demand reallocation.
Despite this steady upward course, the sector confronts several structural friction points that will shape competitive positioning and investment priorities. First, the classification of diethyl chlorophosphate as a hazardous material under international transport frameworks introduces compliance complexity that disproportionately affects smaller manufacturers and cross-border traders. Logistics constraints, labeling requirements, and carrier restrictions elevate operational overhead and can delay time-sensitive deliveries to downstream formulators. Second, the market remains moderately concentrated, with the top three players capturing roughly 35 percent of global revenue and the top five accounting for just over half. This distribution leaves substantial headroom for fragmentation, yet it also means that scale advantages in procurement, purification, and regulatory documentation are increasingly decisive. Third, the industry is navigating a transitional phase in feedstock economics, where volatility in primary intermediary pricing has compelled producers to recalibrate margin structures and explore cost-pass-through mechanisms without alienating price-sensitive buyers.
Key Challenges at an Inflection Point
The intersection of regulatory scrutiny and supply chain recalibration has created an inflection point for market participants. Companies that once relied on incremental capacity additions and standardized distribution models are now compelled to rethink how they manage hazard compliance, quality consistency, and customer segmentation. The pressure is particularly acute in regions where transportation infrastructure is undergoing upgrades or where environmental enforcement is becoming more stringent. At the same time, downstream buyers are demanding greater transparency regarding material sourcing, batch consistency, and safety documentation. These expectations are reshaping procurement criteria and elevating the importance of supplier reliability over pure price competition. For executives evaluating exposure to this segment, the immediate question is not whether growth will continue, but which operational and strategic capabilities will determine who captures the most profitable share of that growth.
Key Drivers Shaping Market Trajectory
The expansion of the diethyl chlorophosphate market is being pulled forward by a convergence of technological, regulatory, and demand-side forces. Understanding these drivers requires looking beyond headline growth figures and examining the operational and commercial mechanisms that convert industry momentum into tangible value creation.
Technological Innovation and Process Refinement
Advancements in synthesis pathways and purification techniques are steadily improving the cost-efficiency and quality consistency of diethyl chlorophosphate production. Manufacturers are investing in optimized chlorination and esterification processes that reduce impurity profiles, particularly for applications requiring high-purity grades. In research and specialty chemical contexts, tighter control over moisture content and byproduct formation has become a differentiator, enabling suppliers to serve demanding applications in pharmaceutical intermediate synthesis and fine chemical production with greater reliability. These process improvements are not merely incremental; they are reshaping the value proposition of the high-purity segment by lowering rejection rates, reducing batch-to-batch variability, and expanding the range of downstream reactions that can be supported with confidence. As a result, suppliers that can demonstrate reproducible purity levels and robust analytical documentation are gaining preference in procurement decisions where performance consistency outweighs marginal price differences.
PW Consulting
Regulatory and Compliance Evolution
The regulatory environment continues to act as both a constraint and a competitive filter. Diethyl chlorophosphate is classified as a hazardous substance under international transport codes, requiring specific labeling, packaging, and carrier coordination in line with Department of Transportation and IATA standards. This classification is not merely a logistical footnote; it influences sourcing decisions, inventory positioning, and the economics of cross-border distribution. In parallel, European Union registration requirements under REACH impose additional obligations for volumes exceeding one tonne per year, with ongoing safety assessments evaluating reprotoxic classification potential. These requirements elevate the compliance burden for manufacturers and distributors operating in or supplying into Europe, but they also create a barrier that favors organizations with established regulatory expertise and document management capabilities. The practical effect is a market where compliance readiness increasingly functions as a strategic asset, enabling better-positioned players to secure long-term supply agreements and expand into regulated end markets with fewer friction points.
Demand-Side Shifts and Application Breadth
On the demand side, end-use industries are driving sustained consumption through both volume growth and application diversification. Agrochemical synthesis remains the largest application channel, reflecting the ongoing need for organophosphorus building blocks in crop protection and specialty pesticide formulations. This segment benefits from structural agricultural demand and the continued modernization of pest management portfolios in multiple regions. Flame retardant manufacturing represents another significant demand pillar, as materials used in electronics, construction, and transportation increasingly require halogen-free or lower-hazard fire resistance solutions. Diethyl chlorophosphate serves as a functional intermediate in certain formulations, linking its consumption to broader materials innovation cycles. Pharmaceutical and fine chemical intermediates, while smaller in aggregate volume, contribute disproportionately to margin profiles because these applications typically require higher purity, stricter documentation, and more responsive technical support. The cumulative effect is a demand base that is broad enough to buffer sector-specific downturns while offering multiple pathways for value creation.
Tris (Clorisopropyl) Phosphate Market
Supply Chain and Cost Structure Dynamics
Supply chain conditions have emerged as a decisive factor in shaping market economics. Feedstock availability and pricing, particularly for phosphorus oxychloride, directly influence production costs and margin resilience. Early 2024 saw a notable increase in intermediary pricing driven by supply chain disruptions in China, a shift that rippled through procurement cycles and prompted manufacturers to reassess inventory strategies. Some producers responded by securing longer-term supply agreements, diversifying source origins, or adjusting product mix toward grades with stronger margin characteristics. The broader lesson is that cost structure flexibility is becoming a competitive requirement rather than an optional optimization. Companies that can dynamically manage input exposure, maintain buffer inventory where justified, and communicate transparent cost drivers to customers are better positioned to preserve profitability during periods of input volatility. Conversely, rigid cost models and single-source dependencies increase vulnerability to regional disruptions and price shocks.
Competitive Landscape and Leading Strategies
The competitive structure of the diethyl chlorophosphate market reflects a blend of established specialty chemical suppliers and regional manufacturers with focused application expertise. Rather than a race to the bottom on price, the leading players are competing on reliability, technical support, purity assurance, and the ability to navigate evolving compliance requirements.
Differentiation Among Key Participants
Several companies have carved out recognizable strategic positions based on their product orientation and end-market focus. Major reagent and research chemical suppliers emphasize high-purity offerings for organic synthesis, phosphorylation reactions, and laboratory-scale applications. Their value proposition centers on consistent batch quality, comprehensive safety documentation, and accessibility for research and development teams. These players often benefit from broad catalog reach, global distribution networks, and strong brand recognition in scientific procurement channels. In contrast, manufacturers oriented toward industrial and agrochemical applications prioritize scale, export capability, and the ability to supply intermediates in volumes that support sustained downstream production. Their differentiation often lies in manufacturing flexibility, the capacity to serve organophosphorus compound supply chains, and responsiveness to bulk procurement requirements. A third group of specialty chemical producers focuses on fine chemical synthesis and pharmaceutical intermediate pathways, where technical service, purification consistency, and regulatory alignment with research-grade expectations matter more than sheer throughput.
Dicalcium Phosphate Market
Strategic Positioning and Competitive Advantages
The most effective competitive strategies in this market combine product-grade focus with operational discipline. High-purity suppliers gain advantage by reducing customer risk in sensitive applications, backing their products with analytical data, and maintaining inventory availability for time-sensitive research and pilot-scale demand. Industrial-focused producers compete by stabilizing supply, managing feedstock exposure, and offering dependable logistics even under hazardous-material transport constraints. Across both models, an increasingly important advantage is regulatory fluency. Suppliers that can anticipate compliance obligations, prepare necessary registration and safety documentation, and communicate transport requirements clearly reduce friction for buyers and strengthen long-term supply relationships. Another differentiating factor is customer segmentation discipline. Companies that align grade offerings, documentation depth, and service levels with specific application needs tend to protect margins more effectively than those pursuing undifferentiated volume growth.
Market Structure Evolution
The market structure appears poised for selective consolidation and parallel specialization. Moderate concentration leaves room for new entrants and regional expansion, particularly where demand growth outpaces local supply or where import dependence creates opportunities for domestic production. At the same time, the compliance, logistics, and quality assurance demands of the sector favor players with established infrastructure and process maturity. Over time, this dynamic is likely to encourage partnership models, capacity alignment with key downstream users, and gradual consolidation among smaller suppliers that lack the scale or capability to keep pace with regulatory and cost pressures. New entrants will need a clearly defined angle, whether through niche purity standards, regional supply reliability, or application-specific technical support, rather than competing purely on availability. The broader trend is toward a more segmented market in which competitive success depends on matching the right grade, the right compliance posture, and the right service model to the right end-use segment.
Future Trends and Commercial Implications
Looking ahead across the next three to five years, several trends are likely to shape how value is created and captured in the diethyl chlorophosphate market. These trends are not isolated developments; they interact with one another and will influence both opportunity selection and risk management.
Continued Growth with Graded Maturity
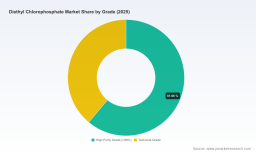
Market expansion is expected to remain positive, but the pace and composition of growth will likely diverge by segment and region. High-purity applications may continue to command stronger margins as research, fine chemical, and specialized intermediate demand grows more exacting. Industrial and agrochemical channels will still contribute substantial volume, but their profitability will depend more heavily on cost management, feedstock stability, and logistics efficiency. For commercial leaders, this implies that strategy should be calibrated by grade and application rather than treating the market as a single growth pool. The most resilient portfolios will likely combine reliable volume sources with higher-value specialty positions that benefit from stricter quality and documentation requirements.
Regulatory and Transport Compliance as a Strategic Lever
Compliance expectations are likely to intensify rather than plateau. Transport classification, labeling discipline, and regional registration processes are already shaping purchasing behavior, and this influence should deepen as enforcement becomes more consistent and documentation expectations rise. Organizations that proactively invest in compliance infrastructure, standardize safety and transport documentation, and monitor regulatory signals will be better equipped to expand into regulated channels and maintain supply continuity. The commercial opportunity here lies in reducing buyer friction: when a supplier can streamline compliance-related overhead for customers, it becomes a preferred partner in procurement decisions where reliability and risk management matter. The risk is equally clear. Operators that treat compliance as a reactive administrative task may face increasing delays, restricted market access, and customer attrition as buyers shift toward partners with stronger readiness.
Feedstock Volatility and Supply Chain Resilience
Input cost dynamics will remain a central theme. Intermediary pricing sensitivity, regional supply disruptions, and logistics constraints can quickly alter margin outlooks. The trend is pushing the market toward greater supply chain resilience through diversified sourcing, inventory planning that balances carrying costs against disruption risk, and closer coordination with downstream users to anticipate demand swings. Companies that build flexibility into procurement and production planning will be more capable of protecting margins while maintaining service levels. At the same time, the market may see increased interest in regional supply hubs and localized distribution strategies to reduce exposure to long-haul hazardous transport constraints and cross-border regulatory variation. The uncertainty lies in how quickly feedstock markets rebalance after disruptions and whether regional production capacity expands fast enough to absorb demand shifts without creating new bottlenecks.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to align grade strategies with the realities of cost structure and compliance readiness. High-purity lines should be supported by robust analytical control and documentation that justifies premium positioning, while industrial-grade operations should focus on feedstock diversification, logistics reliability, and disciplined inventory management. Companies that define their target applications clearly and avoid overextending into segments where they lack technical or regulatory capability are more likely to protect margins and build durable customer relationships.
For investors, the most attractive exposure may not come from undifferentiated volume plays but from operators that combine application focus with compliance strength and supply chain flexibility. Due diligence should assess feedstock exposure, hazardous-material logistics capability, regional regulatory readiness, and the extent to which a company’s product mix aligns with stable or growing end-use channels. Capabilities that reduce customer friction in regulated environments often translate into stronger retention and pricing power over time.
For procurement and sourcing leaders, supplier selection should extend beyond unit price to include batch consistency, documentation quality, transport compliance, and responsiveness under disruption. Long-term agreements can be valuable when paired with suppliers that demonstrate process maturity and regulatory alignment, particularly where production continuity and safety assurance are critical to downstream operations. Ongoing visibility into regional demand shifts, feedstock movements, and regulatory developments will help sourcing teams adjust specifications and inventory posture before disruptions cascade into operational risk. Detailed market intelligence that tracks these signals at a segment and regional level can materially improve planning accuracy and partnership decisions.
For decision-makers seeking a deeper view of segment-level demand structure, regional dynamics, and company-specific positioning, the full PW Consulting market research report provides the supporting detail needed to translate these strategic themes into actionable plans. The complete analysis offers a more granular breakdown of market size trajectories, segmentation intensity, and competitive moves that can inform capacity allocation, sourcing strategy, and investment prioritization with greater precision.
For detailed analysis of this topic, please visit the official page: Worldwide Diethyl Chlorophosphate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com