

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Hot Tapping Machines Market: The Real Drivers Behind 4.7% CAGR Growth

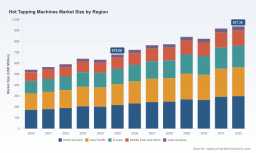
Hot Tapping Machines Market: Strategic Trends, Commercial Opportunities, and the Path Forward
The global hot tapping machines market has settled into a steady growth trajectory, anchored by recurring pipeline intervention needs across energy and industrial sectors. Valued at approximately USD 679.66 million in 2025, the market expanded from around USD 540.21 million in 2020 and is projected to reach roughly USD 937.39 million by 2032, translating to a compound annual growth rate of about 4.7%. This pace reflects a sector that is neither in a speculative boom nor in contraction, but rather in a mature, reliability-driven expansion where incremental gains are earned through operational resilience, compliance, and targeted innovation. The growth is broad-based, spanning multiple product types and application verticals, yet underlying segments show distinct velocity and margin profiles that shape where value is created. A glance at the revenue mix clarifies the competitive battlefield: hydraulic machines command the largest revenue pool, followed by pneumatic systems, with manual and electric variants occupying niche but strategically important positions. Application demand is similarly distributed, with oil and gas pipelines representing the most substantial revenue contributor, while water and wastewater treatment, chemical and industrial processing, and power generation plants collectively sustain a diversified demand base.
Framing the market solely by size, however, obscures the operational realities that determine winners and laggards. The sector is navigating a series of inflection points that test supply resilience, technical sophistication, and commercial agility. First, demand is increasingly defined by in-service continuity. Utilities, energy operators, and industrial plants are reluctant to accept full shutdowns for routine maintenance, branch connections, or emergency repairs, which elevates the strategic importance of equipment that can operate safely under pressure and varying flow conditions. Second, the cost of downtime has become a dominant economic variable. In tightly coupled supply chains and constrained labor markets, a single unplanned outage can cascade into production losses, contract penalties, and reputational damage. Third, regulatory and standards expectations continue to raise the technical bar. Operators and contractors must align procedures with widely referenced safety and design guidelines, which increases the importance of documented process control, material integrity, and operator training. Fourth, raw material specifications matter more than ever. Equipment constructed from pressure vessel–grade materials, with impact toughness at sub-zero temperatures and resistance to sulfide stress cracking, is increasingly favored in demanding service environments. These dynamics are reshaping procurement criteria, pricing power, and service expectations across the value chain.
For executives and investors, the practical implication is that market growth is not a simple function of new capital deployment. The most actionable opportunities lie in reducing total cost of intervention, improving uptime assurance, and aligning product capabilities with evolving compliance expectations. Companies that can demonstrate repeatable performance in live systems, shorten mobilization time, and support diverse pipe materials and pressure classes are better positioned to capture share in a fragmented but increasingly demanding market.
Key Drivers Reshaping the Hot Tapping Machines Market
Technical Capability as the New Differentiator
Innovation in hot tapping is moving beyond mechanical capacity toward integrated performance. The industry is seeing a push toward machines that handle a wider range of pipe diameters, wall thicknesses, and operating pressures without compromising alignment, seal integrity, or cut quality. Proprietary cutter and drive designs, double block and bleed sealing arrangements, and purpose-built accessories are increasingly central to competitive positioning. High-pressure capability is particularly significant in complex service environments, where operators require equipment that can tolerate sour gas conditions, subsea or offshore constraints, and challenging metallurgical profiles. In parallel, there is growing interest in systems that simplify setup and reduce operator dependence, enabling faster mobilization and more consistent outcomes in the field. These capabilities matter because they directly influence whether a contractor can accept a job, how long it takes to complete, and how much risk is transferred back to the asset owner.
Tamping Machine Market
The practical effect is a shift in purchasing logic. Buyers are less focused on unit price alone and more attentive to total intervention cost, including preparation time, tooling availability, spare parts access, and post-operation support. Manufacturers that can package equipment with clear operating envelopes, robust material specifications, and documented procedure support are gaining credibility in segments where failure tolerance is low. This is especially visible in applications where pipelines remain in service during branch connections or line stops, since even minor deviations can create operational or safety exposure.
Regulatory Expectations and Standards Alignment
Standards and guidance documents continue to shape both procurement and field practice. Widely referenced safety and design frameworks provide structured expectations for welding and hot tapping on equipment in service, while pressure equipment and pipeline design codes influence the technical envelope within which machines must operate. Compliance is not merely a procedural formality; it affects liability, insurability, and contractor qualification. As a result, suppliers that can demonstrate alignment with recognized engineering expectations and provide documentation that supports safe execution are better positioned to win work in regulated markets.
This regulatory backdrop also influences product design. Equipment intended for demanding service environments increasingly requires materials and fabrication practices that address sub-zero impact toughness, corrosion resistance, and resistance to sulfide stress cracking. These requirements elevate the importance of supply chain control, quality assurance, and traceability. For operators, the implication is that machine selection is increasingly a risk management decision. For manufacturers, it creates a premium on consistency, certification readiness, and transparent documentation.
Demand-Side Shifts Toward Continuity and Resilience
A structural change in operator behavior is reinforcing demand for in-service connection and repair solutions. Many organizations are prioritizing continuity over the simplicity of a shutdown, particularly where interruptions would disrupt downstream operations, customer commitments, or critical infrastructure services. This shift is visible across multiple verticals, including water distribution, industrial processing, and energy transport. In water systems, for example, there is sustained interest in under-pressure connection methods that allow branch installation without service interruption. In industrial and energy contexts, the emphasis is on minimizing exposure to process upsets while maintaining throughput.
This demand pattern changes the commercial equation. It rewards equipment that is versatile across pipe materials such as steel, copper, brass, and aluminum, and across pressure classes. It also favors suppliers who can support both planned maintenance and urgent response scenarios. From a market perspective, this broadens the addressable opportunity beyond large-scale energy projects into municipal, industrial, and distributed infrastructure work, where frequency of intervention may be higher even if individual project sizes are smaller.
Supply Chain, Cost Structure, and Manufacturing Concentration
Cost dynamics in the hot tapping market are being reshaped by material input requirements, fabrication complexity, and the concentration of manufacturing capability. The top three competitors account for a meaningful share of revenue, and the top five collectively represent more than half of market output. This level of concentration suggests that scale, engineering depth, and established service relationships confer real advantages, particularly in high-stakes applications. At the same time, the presence of specialized manufacturers and regional suppliers ensures that niche requirements, faster turnaround, and application-specific configurations remain viable competitive positions.
Investment in in-house manufacturing capacity is one sign of how companies are responding to these pressures. Strengthening machine shop capability allows suppliers to reduce dependency on external fabrication, improve lead-time predictability, and maintain tighter control over critical components. In an environment where equipment specifications are demanding and downtime costs are high, predictability in production and support can be as valuable as the machine itself. Cost structures are therefore not only about material prices; they are about the ability to deliver repeatable quality, maintain inventory of key parts, and respond to customized requests without excessive premium pricing.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive field in hot tapping machines is diverse, spanning established global specialists, regional manufacturers, and equipment providers that serve narrower application sets. Leadership is not uniformly defined by portfolio breadth; it is increasingly defined by the ability to match machine capability with service requirements, demonstrate reliability in live systems, and support customers through installation, operation, and maintenance. Several firms have built recognizable positions by emphasizing either high-pressure performance, application specialization, or broad coverage across pipe sizes and materials.
One cluster of competitors has focused on comprehensive hot tapping capability for live pipeline connections across a wide diameter and pressure range, including onshore and offshore use. This type of positioning appeals to operators who need a single supplier relationship for multiple project conditions. The strategic advantage here is versatility, supported by a portfolio that spans smaller branch connections and much larger interventions. Another group has built its differentiation around proprietary high-pressure machines with sealing architectures designed for demanding service environments, including sour service and subsea-related applications. In this segment, credibility is tied to documented performance envelopes and the ability to manage risk in challenging conditions. A third group serves water and municipal applications with equipment optimized for under-pressure connections and live service insertion. These companies often compete on long experience, ease of use, and familiarity with local utility practices. A fourth group addresses smaller diameter or lower-pressure needs, including hand-operated or specialized systems for active lines. These offerings may not dominate headline revenue, but they can be strategically important where speed, simplicity, and accessibility matter more than maximum operating pressure.
Differentiation Paths and Commercial Logic
Across these positions, several common success factors emerge. The first is technical clarity. Suppliers that define operating envelopes precisely, specify compatible pipe materials and pressure ranges, and provide accessories that reduce field complexity tend to earn stronger customer confidence. The second is service integration. Hot tapping is not purely an equipment sale; it often involves procedure support, training, spare parts availability, and rapid response when field conditions change. Companies that treat support as part of the core offering can command better retention and more predictable demand. The third is manufacturing discipline. Recent investments in advanced machine tools by established players reflect an intent to control critical production steps internally, which can improve consistency and reduce dependence on external sources for key components. Such moves are especially meaningful when equipment must meet stringent material and performance expectations.
How the Landscape Is Evolving
The market structure appears likely to remain moderately fragmented while rewarding scale in the upper end of the pressure and diameter spectrum. Consolidation may continue where companies seek broader application coverage, stronger service networks, or deeper manufacturing capability. At the same time, the presence of specialized and regional players is likely to persist because many projects have localized requirements, specific material constraints, or limited scope that favors agile suppliers over large portfolios. New entrants face a meaningful barrier in credibility, documentation, and field validation, but they can still gain traction by targeting underserved size ranges, particular materials, or specific application workflows. In parallel, industry events and technical exchanges continue to accelerate the spread of best practices, especially around repair methods, in-service welding considerations, and safe intervention procedures. These forums matter because they influence operator expectations and elevate the importance of demonstrable competence over generic capability claims.
Forward Outlook: Trends and Opportunity Windows for 2026–2032
The next several years are likely to be shaped by a combination of steady demand growth and selective performance upgrades. One clear direction is the continued emphasis on in-service operations. As operators weigh the cost of shutdowns against the complexity of live interventions, equipment that enables safe branch connections and line stops without service interruption will remain central. This favors designs that improve alignment control, sealing reliability, and adaptability across pipe types. A second direction is the expansion of application coverage in water, wastewater, and industrial processing. While energy pipelines remain a major revenue pillar, diversified infrastructure spending and the need to maintain existing systems create repeated intervention opportunities in other verticals. A third direction is increasing attention to material integrity and compliance documentation. As expectations around pressure equipment, pipeline design, and safe field practice remain elevated, suppliers will be rewarded for transparent specifications and repeatable quality.
These trends create several commercial opportunity windows. For manufacturers, there is room to strengthen high-pressure and specialty portfolios while also improving accessibility for smaller-diameter or lower-pressure applications where demand frequency can be high. For equipment distributors and service providers, the value lies in combining suitable machines with procedure support, training, and rapid parts availability, since field outcomes depend on more than hardware alone. For investors, the more attractive exposure is likely to be in companies that can demonstrate consistent execution, controlled manufacturing, and the ability to serve regulated or high-risk applications where failure is costly. At the same time, uncertainty remains. Demand can shift with project cycles, maintenance budgets, and macroeconomic conditions. Raw material and fabrication costs may compress margins if not managed carefully. And competitive pressure can intensify where products become more comparable, especially in commoditized size and pressure ranges. The net effect is that growth will likely continue, but profitability and market share will be determined by execution quality rather than market tailwinds alone.
Actionable Implications for Decision-Makers
For manufacturers and equipment suppliers, the strategic priority is to align product capability with the economics of uptime. That means sharpening the definition of operating envelopes, investing in manufacturing control for critical components, and treating documentation and support as core commercial assets. Companies that can reduce setup complexity, improve reliability across materials, and shorten mobilization timelines will be better positioned to compete in both planned and urgent intervention scenarios. It also pays to evaluate where portfolio breadth genuinely adds value and where focused specialization can protect margin.
For investors and strategic planners, the key is to look beyond headline market size and assess where value is being retained. Attention should be given to suppliers with credible high-pressure or specialty positions, disciplined production capabilities, and service models that reduce customer risk. Portfolio exposure should be evaluated against demand diversification across oil and gas, water and wastewater, chemical and industrial processing, and power generation, since segment mix influences both growth resilience and sensitivity to project cycles. In a market where the top five competitors hold a majority share, scale advantages are real, but differentiated application expertise can still create durable niches.
For procurement teams and end users, machine selection should be evaluated through a total-intervention lens. The relevant questions include how well the equipment matches pipe material and pressure class, how quickly it can be deployed, how restrictive its documentation and compliance support are, and whether spare parts and field support are available when conditions change. Buying on unit price alone can understate operational risk and long-cycle cost. Selecting equipment that aligns with service conditions and support expectations typically reduces exposure to delays, rework, and downtime-related losses.
For decision-makers who need precise segmentation, regional demand patterns, product-type breakdowns, application-level revenue detail, and competitive benchmarking, a comprehensive market study can provide the granularity required for planning and investment judgment. A full research report can also support scenario analysis around pricing, capacity investments, and entry strategy across different application verticals and geographic markets.
Worldwide Single Axis Automatic Tapping Machine Market
For detailed analysis of this topic, please visit the official page: Worldwide Hot Tapping Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com