

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Worldwide Enalapril Market CAGR Insights: What the 2032 Growth Path Means
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Enalapril Market
Market Overview and Core Challenges
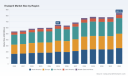
The global enalapril market has demonstrated steady expansion over the past half-decade, reflecting the persistent demand for effective cardiovascular therapeutics. From 2020 to 2025, the market evolved from a base of approximately 538 million USD to an estimated 649 million USD in the current year, indicating a compound annual growth rate of 3.82 percent through the forecast horizon extending to 2032. This trajectory suggests that while the molecule is well-established, the addressable market continues to expand alongside broader epidemiological shifts and healthcare accessibility improvements. The growth pattern, however, is not linear, with projected fluctuations in the late 2020s highlighting the sensitivity of revenue streams to regulatory approvals, generic erosion, and regional pricing pressures.
Despite this foundational stability, the industry is navigating several structural challenges that threaten to reshape competitive dynamics. First, the maturation of generic penetration has intensified price competition, compressing margins for formulators who lack differentiated supply chain capabilities or regulatory agility. With the market characterized by moderate concentration, where the top three firms capture roughly 38 percent of revenue and the top five account for over half, smaller players must rely on niche capabilities or regional partnerships to maintain relevance. Second, supply chain fragility remains a persistent risk, particularly given the heavy reliance on imported active pharmaceutical ingredients for cardiovascular therapies in major consumption markets. This dependency exposes manufacturers to geopolitical disruptions, regulatory audits, and cost volatility that can ripple through finished product pricing. Third, reimbursement scrutiny and formulary management in developed healthcare systems are increasingly favoring cost-optimized procurement, forcing suppliers to demonstrate value beyond molecule efficacy alone. These intersecting pressures create a pivotal moment where operational efficiency, regulatory foresight, and market access strategy determine long-term positioning.
Key Drivers of Market Evolution
Technological and manufacturing innovation continues to influence how enalapril is produced, formulated, and delivered. Advances in process chemistry and continuous manufacturing principles have enabled more consistent API quality and reduced batch variability, which is especially relevant for narrowly therapeutic molecules where impurities or potency drift can trigger regulatory action. A practical illustration of shifting formulation priorities emerged in early 2024, when a major generic manufacturer received FDA clearance for an enalapril maleate oral solution. This approval expanded the available dosage forms beyond conventional tablets, addressing patient populations with swallowing difficulties or pediatric needs and signaling that incremental formulation innovation remains a viable pathway to differentiation even in a mature generic landscape.
Regulatory and policy frameworks are simultaneously reshaping market access and competitive entry. The authorization landscape has shown renewed openness to specialized indications, as evidenced by a 2023 European Medicines Agency decision clearing a pediatric heart failure indication for an enalapril-based product. Such regulatory milestones matter because they extend the clinical utility of the molecule into underserved patient groups, create labeling distinctions that can support market segmentation, and encourage manufacturers to invest in targeted clinical or regulatory submissions rather than competing solely on bulk generic volume. At the same time, regulatory scrutiny on supply chain integrity continues to tighten, reinforcing the importance of documented quality systems and traceability for both API producers and finished dosage manufacturers.
Demand-side behavior is shifting as healthcare systems and patients navigate long-term cardiovascular management. Hypertension and heart failure remain dominant indications for enalapril, supported by its established clinical profile and broad generic availability. Yet the demand narrative is increasingly shaped by adherence considerations, chronic care management programs, and the preference for therapies that integrate smoothly into multiprescriber regimens. In this environment, products that offer reliable supply, consistent bioequivalence performance, and supportive packaging or delivery formats can gain outsized attention from procurement teams and clinical stakeholders who prioritize continuity of care over marginal unit-cost differences.
Cost structure dynamics, particularly around API procurement, add another layer of complexity. Reported pricing disparities across sourcing regions underscore how regulatory compliance requirements, local demand from formulation manufacturers, and regional production costs influence input economics. These variations create opportunities for companies that can secure stable, compliant supply at competitive terms, while also elevating the risk for players dependent on single-source procurement or exposed to currency and logistics volatility.
- Process and formulation innovation can unlock incremental value even after patent expiry, particularly when it addresses adherence or population-specific needs.
- Regulatory approvals for new indications or dosage forms can create temporary differentiation windows and support targeted market access strategies.
- Demand patterns are increasingly influenced by adherence, chronic care integration, and procurement priorities that weigh supply reliability alongside price.
- API cost dispersion across regions encourages diversified sourcing strategies and emphasizes the value of compliant, audit-ready suppliers.
Competitive Landscape and Leading Strategies
The competitive field is defined by a mix of large multinational generic suppliers and specialized API manufacturers concentrated in India, China, Europe, and the United States. This geographic spread reflects both historical manufacturing strengths and the way regulatory pathways shape market entry. Companies with integrated API and formulation capabilities tend to hold an advantage in managing cost, quality, and lead times, while API-focused producers often compete on regulatory filings, export reach, and customization for formulation partners. The presence of multiple suppliers for finished dosage forms indicates a mature competitive environment where scale, regulatory track record, and distribution relationships are central to sustaining share.
Strategic positioning among leading players often hinges on regulatory asset accumulation and market-specific execution. A notable example occurred in mid-2025, when one company expanded its U.S. market footprint by acquiring an FDA-approved abbreviated new drug application for enalapril maleate tablets in multiple strengths from another established manufacturer. Transactions of this type illustrate how regulatory assets can serve as strategic currency, enabling faster commercial entry, portfolio expansion, or geographic rebalancing without the lead time of de novo filings. In parallel, the broader pattern of multiple firms maintaining broad generic tablet portfolios across strengths suggests that competitive advantage increasingly depends on operational reliability, supply continuity, and the ability to serve procurement programs that value predictability.
Epinephrine Market
The market structure appears to be moving through a phase where consolidation and selective diversification coexist. On one hand, acquisition of approved applications and partnerships between API producers and formulators can consolidate capability among players seeking to reduce dependency on external suppliers. On the other hand, specialized entrants continue to find openings in narrower segments, such as alternative formulations or indication-specific supply arrangements. This duality means that incumbents must defend share through cost discipline and quality assurance, while new and expanding participants can pursue differentiated routes tied to regulatory assets, formulation variants, or regional supply agreements.
Several strategic themes recur among stronger performers. First, maintaining a diversified regulatory footprint reduces exposure to single-market pricing pressure and creates options for portfolio optimization. Second, investing in supply chain resilience, including multi-source API strategies and audit-ready quality systems, supports both commercial continuity and customer confidence. Third, building capability around non-tablet formats or specialized indications can create pockets of differentiation in an otherwise crowded field. The interplay of these approaches suggests that long-term success will depend less on molecule novelty and more on execution excellence across regulation, manufacturing, and market access.
- Leading players combine regulatory asset strength with formulation breadth to sustain presence across multiple markets and dosage strengths.
- Acquisition of approved applications and partnership-based supply models are becoming common mechanisms for accelerating market entry and rebalancing portfolios.
- Competitive differentiation is shifting toward supply reliability, quality documentation, and targeted formulation or indication strategies rather than volume alone.
- The coexistence of consolidation activity and niche expansion indicates a market where operational agility and regulatory readiness determine competitive outcomes.
Future Trends and Outlook
Over the next three to five years, the market is likely to be shaped by the interplay of sustained cardiovascular demand, continued generic competition, and incremental regulatory and formulation evolution. One key trend is the ongoing rationalization of supply chains toward greater resilience and documentation rigor. As procurement organizations in major markets place increasing weight on supply continuity and auditable quality, suppliers that can demonstrate robust sourcing, validated processes, and transparent compliance records will be better positioned to secure long-term contracts and withstand price competition. This trend creates commercial opportunities for manufacturers that invest early in supply chain diversification and regulatory readiness, especially where API sourcing is concentrated or vulnerable to external shocks.
A second trend concerns the gradual broadening of usage contexts through formulation and indication refinement. Even in a well-established generic category, approvals that address specific patient populations or delivery preferences can create meaningful commercial differentiation. Products aligned with pediatric, geriatric, or adherence-sensitive use cases may command more favorable positioning in certain procurement and clinical settings, particularly where healthcare providers seek to reduce administration barriers and support long-term therapy continuity. The opportunity here lies not in discovering new therapeutic territory, but in translating existing molecule utility into formats and labeling that better fit practical care delivery.
A third trend is the intensification of pricing discipline as more competitors compete in mature generic segments. With a wide field of suppliers, margin preservation will increasingly depend on operational efficiency, mix management, and value-added services such as reliable delivery, batch consistency, and responsive regulatory support. This environment favors organizations that can manage cost structures without sacrificing quality, and that understand the local procurement dynamics of each market they serve. At the same time, uncertainty remains around reimbursement pressure, regulatory enforcement intensity, and the potential for supply disruptions to alter short-term pricing and availability. Companies that treat these variables as manageable risks rather than external surprises will be better prepared to capture share when conditions shift.
Worldwide Enfuvirtide Market
- Supply chain resilience and documented quality will become more commercially relevant as procurement prioritizes continuity and compliance.
- Formulation and indication refinements offer realistic differentiation opportunities that support adherence and specific patient groups.
- Pricing pressure will reward operational efficiency and market-specific execution, while exposing firms that rely on single-channel volume strategies.
- Regulatory, reimbursement, and supply-side uncertainties will require scenario-aware planning rather than static forecasts.
Actionable Insights for Decision-Makers
For manufacturers, the priority is to strengthen the operational foundations that translate into commercial reliability. Diversifying API sourcing, reinforcing quality documentation, and investing in formulation flexibility can reduce exposure to input cost swings and regulatory interruptions while improving the ability to serve differentiated customer needs. Companies should also evaluate regulatory asset strategies, including the potential to acquire or partner around approved applications, as a means to accelerate entry or expand strength coverage in target markets.
PW Consulting
For investors, the market rewards disciplined exposure to participants with credible supply chains, broad regulatory footprints, and the ability to compete on reliability as much as price. Due diligence should focus on sourcing dependencies, approval pipelines for additional indications or formulations, and the extent to which a company’s portfolio mix supports margin stability in a competitive generic environment. Monitoring transaction activity around regulatory assets can also provide early signals about where capability is consolidating.
For procurement and market access teams, the emphasis should be on qualifying suppliers that can deliver consistent supply and auditable quality without sacrificing cost efficiency. Balancing multi-source strategies with long-term partnership structures can help mitigate disruption risk while preserving negotiating leverage. Where possible, aligning product selection with adherence-friendly formats and reliable delivery performance can support both clinical continuity and total cost-of-care objectives.
For stakeholders seeking a deeper view of regional revenue splits, formulation and indication dynamics, concentration metrics, and company-level strategic profiles, a more comprehensive research resource is available to support detailed planning and scenario modeling.
For detailed analysis of this topic, please visit the official page: Worldwide Enalapril Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Super High Count Cashmere Yarn Market: Why 5.86% CAGR Reshapes Luxury Growth
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Global Super High Count Cashmere Yarn Market
Market Landscape and Core Challenges
The worldwide super high count cashmere yarn market has demonstrated consistent upward momentum over the past five years, with total revenue expanding from approximately $382 million in 2020 to $512 million in 2025. Over the 2026-2032 forecast period, the market is projected to reach $763 million, reflecting a compound annual growth rate of 5.86 percent. This trajectory underscores steady demand for ultra-fine, high-count yarns that deliver exceptional softness, drape, and luxury aesthetics. Revenue growth has been particularly pronounced as brands elevate premium product lines and consumers increasingly prioritize tactile quality and material provenance over volume-driven fashion cycles.
Despite this expansion, the industry faces structural inflection points that will shape competitive outcomes over the next several years. First, raw material volatility continues to complicate planning and margin management. Cashmere fiber prices softened but remained highly unpredictable through late 2025, driven by constrained grazing conditions, shifting buyer sentiment, and evolving trade policies in key sourcing regions. Concurrently, wool and cashmere yarn prices climbed 10 to 15 percent since late 2025 as producers absorbed higher production costs, climate-related pasture stress, and breeding constraints. These cost pressures test the pricing power of downstream manufacturers who must balance premium positioning with consumer willingness to pay.
Second, the regulatory and trade environment is actively reshaping sourcing strategies and value capture. Policy interventions aimed at encouraging domestic processing have altered traditional export patterns, while sustainability certification frameworks are gaining traction across major producing regions. These developments reward vertically integrated players and penalize suppliers reliant on fragmented, opaque supply chains.
Third, the market's moderate concentration means competitive advantage increasingly depends on technical differentiation rather than scale alone. With a relatively small number of established mills controlling meaningful market share, new entrants and existing manufacturers alike must navigate the tension between volume growth and the meticulous fiber selection, dehairing precision, and count consistency required for the highest-tier yarns. The result is a market where premium positioning, traceability, and processing capability will separate long-term winners from commoditized participants.
Key Drivers of Market Transformation
Technological Innovation and Fiber Processing Breakthroughs
Advancements in dehairing technology, fiber grading, and high-count spinning have fundamentally expanded the feasibility of ultra-fine cashmere yarns while improving consistency across large production runs. Modern ring and air-jet spinning systems, combined with refined worsted and semi-worsted processes, enable manufacturers to achieve finer deniers and higher uniformity with reduced pilling and enhanced color stability. These technical gains are particularly important for applications that demand lightweight, drape-forward constructions, where even minor fiber irregularities can compromise end-product performance.
Leading players are leveraging these capabilities to shift from generic premium positioning toward highly specific yarn architectures tailored to luxury apparel and high-end accessories. Firms that integrate fiber selection, dehairing, and spinning under one operational umbrella can control critical quality parameters, reducing variability and enabling repeatable performance at counts that once required painstaking manual intervention. This vertical integration also supports faster iteration cycles for seasonal collections and custom specifications, a growing expectation among luxury brand partners.
Policy and Regulatory Environment
Policy developments are increasingly steering raw material flows toward domestic processing and higher value addition. In mid-2025, Mongolia implemented a ban on exporting uncombed cashmere, a move designed to encourage local refining and capture more margin within the country of origin. This policy shift has reoriented trade patterns and prompted downstream buyers to reassess sourcing pathways, particularly for combed fiber used in high-count yarn production. At the same time, Mongolia's export milestone in 2025—reaching 4,000 tons of combed cashmere valued at $330.6 million, a 28.7 percent increase in value—demonstrates how targeted investments and processing incentives can accelerate value capture. Government commitments to expand processing capacity through substantial investment programs signal a longer-term structural change in how raw material value is distributed across the supply chain.
Parallel to trade policy, sustainability certification frameworks are becoming operational realities rather than aspirational markers. Standards addressing animal welfare, pasture management, and fiber quality are increasingly referenced by brands and retailers seeking to validate responsible sourcing claims. Certification programs that establish model farms and transparent practices in major producing regions are helping to stabilize supply relationships and reduce perceived risk for buyers. Over time, compliance with recognized standards will likely function as a baseline requirement rather than a differentiator, with early adopters benefiting from stronger brand partnerships and preferential access to premium fiber allocations.
Demand-Side Shifts in Consumer and Brand Behavior
Demand for super high count cashmere yarns is being propelled by a consumer base that increasingly associates fiber fineness and craftsmanship with enduring value. Luxury apparel remains the dominant application category, reflecting brand strategies that use ultra-fine yarn constructions to differentiate core collections and justify premium pricing. Beyond apparel, high-end accessories continue to grow as consumers seek tactile quality in smaller, higher-margin items that showcase material excellence without the footprint of full garments.
Brand behavior is also shifting toward responsible sourcing narratives that connect fiber origin to finished product. Traceability, provenance, and sustainability credentials are no longer secondary considerations; they influence design decisions, sourcing contracts, and consumer communication. This trend is particularly pronounced among heritage European houses and forward-looking contemporary brands alike, both of which are seeking yarns that deliver consistent quality while supporting verifiable sustainability claims. The result is a more discerning buyer base that values both performance and transparency, raising the bar for yarn suppliers across the value chain.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by the intersection of raw material constraints, processing incentives, and labor and energy considerations across producing regions. Soft but volatile fiber pricing creates planning complexity, while the 10 to 15 percent increase in yarn prices since late 2025 highlights the need for careful cost-pass-through strategies. Manufacturers that can secure stable fiber access through long-term relationships, vertically integrated operations, or certified sourcing models are better positioned to manage margin compression and maintain consistent output.
At the same time, the promotion of domestic processing in key sourcing countries is altering the economics of import dependency. Buyers who previously relied on imported semi-processed materials now face a landscape where refined combed fiber and finished yarns are increasingly available closer to origin, often accompanied by local investment in spinning capacity and technical know-how. This evolution offers new sourcing flexibility but also demands greater supplier assessment rigor, particularly as regional capacity expands and new entrants compete for premium fiber allocations.
Competitive Landscape and Leading Strategies
The market features a blend of heritage European mills, vertically integrated Chinese producers, and specialized suppliers whose strategies reflect distinct approaches to premium positioning. Italian and Scottish firms continue to leverage reputation, technical heritage, and tight integration with luxury brand relationships to command premium pricing for ultra-fine counts. These players emphasize fiber selection, count consistency, and aesthetic performance, often focusing on specific counts and constructions that align with luxury knitwear and apparel specifications. Their differentiation rests on proven quality, low-pilling performance, consistent coloration, and the ability to support bespoke development cycles for high-value collections.
Chinese producers have scaled capacity and technical capability to serve both domestic and international premium markets. Large-scale manufacturers with multi-thousand-ton annual capacity now offer pure cashmere, blends, recycled, and antibacterial yarns using advanced spinning techniques derived from European best practices. Their strategic advantage lies in scale, customization flexibility, and the ability to produce high-count worsted, woolen, and semi-worsted yarns across a broad specification range. By combining advanced spinning infrastructure with access to Inner Mongolian fibers, these producers can respond to diverse brand requirements while maintaining competitive cost structures.
Vertical integration remains a recurring theme among top performers. Major producers in Inner Mongolia combine fiber sourcing, dehairing, and spinning within integrated operations, enabling tighter control over fiber quality and count consistency. Some mills focus on dehaired cashmere yarns with dedicated capacity for both ring and air-jet spinning, supporting pure and blended offerings across multiple end markets. This integration helps manage volatility in raw material supply and provides a dependable foundation for sustained premium output.
The competitive dynamics are evolving along several axes. Consolidation is likely to continue as larger players acquire technical capabilities, fiber access, or downstream relationships to strengthen premium positioning. Simultaneously, fragmentation persists in niche segments where ultra-fine counts, limited-edition constructions, and sustainability credentials create space for specialized mills that serve a small number of high-value brand partners. New entrants are appearing where investment in processing capacity intersects with regional policy support, particularly in markets investing heavily in domestic refining and spinning infrastructure. Success in this environment requires clear strategic differentiation: either scale-enabled cost efficiency with consistent premium quality, or heritage-driven technical excellence with strong traceability and brand relationships.
Future Trends and Commercial Opportunities
Over the next three to five years, three interconnected trends will shape strategic opportunities in the super high count cashmere yarn market.
-
Sustainability and traceability become procurement prerequisites. Certification frameworks and brand-level sourcing policies will increasingly require documented fiber origin, animal welfare practices, and pasture management standards. Suppliers that can provide verifiable traceability and align with recognized standards will secure preferred access to premium buyers, while laggards face growing exclusion risk from luxury brand procurement processes.
-
Regional processing capacity reshapes sourcing geography. Continued investment in domestic refining and spinning near major fiber origins will expand the availability of high-quality combed fiber and finished yarns closer to source. This creates opportunities for buyers seeking diversified, resilient supply bases and for producers positioned to serve both local premium markets and international brand partners. However, it also raises the importance of supplier qualification, quality assurance, and long-term relationship management as new capacity enters the market.
-
Ultra-fine yarn architectures expand into adjacent premium categories. Advances in spinning consistency and fiber preparation will enable high-count yarns to penetrate new applications beyond luxury apparel and accessories, including lightweight technical knitwear and premium home textiles where softness, drape, and durability matter. Manufacturers that can tailor count, twist, and blend structures to specific end-use requirements will capture value in these expanding niches.
Fashion Luxury Cashmere Clothing Market
These trends carry inherent uncertainty. Raw material price volatility may persist if climate pressures, breeding constraints, and trade policy shifts continue to affect fiber supply. Rapid capacity expansion in processing centers could intensify competition for premium fiber allocations, compressing margins for suppliers unable to differentiate on quality or traceability. Additionally, brand consolidation and shifting consumer preferences toward resale, longevity, or alternative sustainable materials could alter demand intensity for premium yarns. Navigating these risks will require disciplined supplier selection, transparent sourcing narratives, and the ability to adapt product specifications as brand requirements evolve.
Fleece Knitting Yarn Market
Actionable Guidance for Decision Makers
For manufacturers and yarn producers: Prioritize technical differentiation and traceability as core strategic assets. Invest in dehairing precision, count consistency, and color stability to defend premium pricing, and build documented sustainability credentials that align with emerging brand requirements. Evaluate vertical integration opportunities or long-term fiber supply agreements that reduce exposure to raw material volatility and secure access to high-grade fibers. Where capacity expansion is underway, focus on quality assurance and application-specific yarn architectures rather than undifferentiated volume growth.
For investors and corporate strategy teams: Look for value creation in processing capacity supported by policy tailwinds and in suppliers with demonstrable traceability and quality control capabilities. The most resilient opportunities will combine stable fiber access with technical competence in high-count spinning and the ability to serve luxury brand specifications. Assess regional dynamics carefully, particularly where domestic processing incentives are reshaping value capture, and weigh the trade-offs between scale advantages and the premium pricing power that comes from differentiated quality and brand relationships.
For procurement and sourcing leaders: Diversify supply bases to balance quality, resilience, and cost, and embed sustainability and traceability criteria into supplier evaluation from the outset. Establish long-term relationships with mills capable of consistent ultra-fine output and clear documentation of fiber origin and processing practices. As regulations and brand expectations tighten, proactive supplier qualification and transparent sourcing will reduce disruption risk and strengthen brand credibility.
PW Consulting
Detailed segmentation data, regional volume and value breakdowns, and company-level profiles can clarify where to prioritize investment, sourcing, and product development. A comprehensive market assessment provides the granular context needed to evaluate capacity expansions, supplier suitability, and segment-level growth potential with greater precision.
For detailed analysis of this topic, please visit the official page: Worldwide Super High Count Cashmere Yarn Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Industrial Burden Carrier Market 2026: Why 4.95% CAGR Signals a $751M Shift
By pmarketresearch, 2026-09-18
Navigating the Worldwide Industrial Burden Carrier Market: Strategic Trends and Commercial Opportunities (2026–2032)
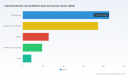
The global industrial burden carrier market has entered a decisive growth phase, defined by a structural shift from internal combustion to electric propulsion and by widening application scope across manufacturing, logistics, aviation, and healthcare environments. Market valuation climbed from approximately $420.5 million in 2020 to an estimated $535.4 million in 2025, and forward projections indicate sustained expansion toward $750.85 million by 2032.
This trajectory reflects a compound annual growth rate of roughly 4.95 percent across the forecast horizon, with revenue tracked in USD million. The expansion is not merely cyclical; it represents a fundamental recalibration of how facilities move materials, personnel, and equipment within constrained operational footprints. Burden carriers have evolved from niche utility vehicles into integral nodes of intra-facility logistics, bridging gaps between fixed infrastructure and mobile material handling.
Several interconnected challenges and inflection points are reshaping how organizations evaluate burden carrier investments and deployment strategies. First, the industry is navigating a cost and compliance paradox. Zero-emission mandates and indoor air-quality regulations across more than sixty countries are accelerating electrification, yet transition timelines vary significantly by jurisdiction, creating fragmented compliance landscapes and uneven capital planning cycles. Second, supply chain volatility in critical inputs continues to pressure pricing and lead times. Global iron ore benchmarks for China-imported 62% Fe fines are forecast to ease from approximately $100 per ton in 2025 to $90 per ton in 2026, influencing steel costs for chassis and frames. At the same time, US Midwest hot-rolled coil steel prices are expected to trade in the $980 to $1,060 per short ton range in early 2026, with flat to slightly rising trends shaped by tariff dynamics and manufacturing activity. These inputs directly affect build economics for heavy-duty frames, load beds, and structural components. Third, organizations face an operational integration challenge. Rising warehouse automation and persistent labor shortages in manufacturing and logistics sectors are increasing reliance on burden carriers to improve throughput and reduce manual handling, but integrating these vehicles into existing material flow architectures, charging infrastructure, and safety protocols requires disciplined change management.
The market’s concentration profile underscores both stability and opportunity. A core group of established manufacturers holds meaningful share, yet the growth trajectory leaves room for differentiated entrants that can address specialized payloads, ergonomics, and sector-specific compliance requirements.
Hand Trucks Market
Key Drivers Reshaping the Market
Electrification and Propulsion Technology Breakthroughs
Electrification stands as the most conspicuous accelerator in the market. Electric propulsion now commands the overwhelming majority of revenue, reflecting sustained advantages in total cost of ownership, indoor air quality, noise reduction, and simplified maintenance relative to internal combustion alternatives. The performance envelope of electric burden carriers is expanding, with manufacturers introducing flatbed designs, higher payload capacities, enhanced towing capabilities, and cabin configurations that support multi-operator use. Practical demonstrations at industry trade events highlight this shift. At the ARA Show, a new lithium-ion burden carrier featuring a four-seater option and an enclosed cabin option was exhibited, signaling growing demand for versatile, multi-purpose transport platforms. In parallel, enhanced warehouse-focused models are reaching availability, including electric burden carriers with carrying capacities in the 4,400 to 6,600 lb range and towing capacities up to 8,800 lb, tailored for tight pathways and high-throughput environments. These capabilities reduce the need for multiple specialized vehicles, enabling facilities to consolidate intra-facility transport around fewer, more adaptable assets.
Policy and Regulatory Momentum
Regulatory direction continues to reinforce electrification while raising the bar for safety and operational reliability. Zero-emission mandates and indoor air-quality regulations across more than sixty countries, including frameworks aligned with the EU Green Deal and US EPA guidelines, are steering procurement toward electric platforms and away from combustion-based alternatives. Concurrently, ISO 3691-1 safety requirements and verification for self-propelled industrial trucks remain the active standard governing design and operation of related equipment, reinforcing expectations around stability, operator protection, braking, and load handling. For manufacturers and buyers alike, these standards create a predictable compliance baseline but also demand rigorous validation, especially as vehicle designs diversify and operational contexts broaden. Organizations that align product development and procurement with these expectations can reduce time-to-deployment and lower lifecycle risk.
Demand-Side Shifts in Operational Behavior
Demand is being reshaped by changing facility economics and workforce dynamics. Warehouses, distribution centers, manufacturing plants, airports, and healthcare campuses increasingly require flexible, low-emission vehicles that can move both materials and personnel within constrained spaces. The rise of automation and persistent labor constraints heightens the value of burden carriers that improve throughput, reduce manual handling, and integrate cleanly with broader logistics systems. Operator experience is also receiving greater attention. Recent product introductions feature larger operator compartments and improved ergonomics designed specifically for burden carrier applications, reflecting a focus on comfort, visibility, and productivity during extended shifts. As facilities pursue tighter material flow and fewer process handoffs, they are gravitating toward platforms that combine payload flexibility with towing capacity and maneuverability, rather than single-purpose equipment.
Cost Structure and Supply Chain Realities
Cost dynamics are evolving as electrification reduces fuel and maintenance burdens while steel and component inputs continue to fluctuate. Declining iron ore benchmarks may ease some chassis and frame costs, but regional steel pricing remains sensitive to tariffs and manufacturing conditions, keeping build economics in flux. Manufacturers are responding with modular architectures, configurable payloads, and design choices that balance durability with cost efficiency. For buyers, the economic case increasingly centers on total cost of ownership, uptime, and integration rather than sticker price alone. This shifts the purchasing conversation toward lifecycle analysis, charging strategy, parts availability, and service support—factors that can determine whether an initial purchase translates into sustained operational value.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a mix of specialized manufacturers and broader material handling brands, each pursuing distinct value propositions. Motrec International Inc., based in Quebec, Canada, offers customizable electric flatbed burden carriers with load capacities up to 5,000 lbs, targeting heavy-duty material transport in industrial facilities, warehouses, and manufacturing plants. Taylor-Dunn Manufacturing Company, headquartered in Anaheim, California, specializes in electric burden carriers including Bigfoot series models with payloads up to 3,000 lbs and towing up to 10,000+ lbs, suited for warehouses, railyards, airports, and tight industrial pathways. Cushman, part of Textron Specialized Vehicles and based in Augusta, Georgia, provides electric burden carriers such as Titan HD, Minute Miser, and Stock Chaser models for personnel and material transport across warehouses, manufacturing, and commercial industrial settings. Pack Mule, operating under Capacity Trucks in the USA, manufactures heavy-duty NXG and ALPHA series electric burden carriers with high payload and towing capacities for manufacturing plants, warehouses, and distribution centers. Johnson Industries Inc., located in Kentucky, focuses on high-quality industrial burden carrier vehicles emphasizing operator safety and efficiency for mining and heavy industrial applications. Trowin Industries, based in the USA, offers flatbed burden carriers for maintenance, rescue, baggage handling, and passenger transport in industrial environments. Columbia ParCar Corp, in Reedsburg, Wisconsin, supplies Payloader Pro and other electric burden carriers for industrial material and personnel movement. Bobcat Company, headquartered in West Fargo, North Dakota, produces BBC23S-7 and BBC28S-7 electric burden carriers with carrying capacities of 4,400 to 6,600 lbs and towing up to 8,800 lbs for warehouse and construction facilities. Toyota Material Handling, in Columbus, Indiana, includes industrial burden carriers within its broader material handling portfolio for efficient intra-facility transport. HC Forklift America, based in the USA, introduces lithium-ion electric burden carriers with multi-seater options for material, equipment, and personnel transport in manufacturing, airports, and workshops.
Leading strategies reveal clear differentiation paths. One approach centers on customization and payload flexibility, enabling buyers to match vehicle configurations to specific aisle widths, load types, and towing requirements. Another emphasizes ergonomics and multi-purpose use, with larger operator compartments, enclosed cabin options, and multi-seater configurations that support mixed material and personnel transport. A third strategy leans into application specialization, with designs tuned for mining, heavy industrial environments, baggage handling, and rescue operations, where durability, safety, and operational resilience take precedence. Recent developments illustrate this competitive dynamism. Taylor-Dunn launched the Bigfoot S series with a larger operator compartment and improved ergonomics for burden carrier applications, reinforcing the ergonomic and comfort angle. Bobcat Company made the 2026 BBC28S-7 electric burden carrier available with enhanced warehouse capabilities, highlighting the ongoing push to adapt electric platforms for high-throughput logistics. HC Forklift America showcased a new lithium-ion burden carrier with a four-seater option and enclosed cabin option at the ARA Show, reflecting growing interest in versatile, enclosed, multi-operator platforms.
Market evolution appears to be moving along two parallel tracks. On one hand, established brands are extending their electric portfolios and integrating burden carriers into broader material handling ecosystems, creating one-stop sourcing advantages and cross-selling opportunities. On the other hand, specialization is intensifying as buyers seek vehicles optimized for specific workflows, payload profiles, and regulatory environments. This combination suggests a landscape that will continue to support both consolidation among broad-line providers and fragmentation around niche applications, with new entrants competing on configurability, safety features, and total cost of ownership rather than price alone.
Industrial UPS Market
Future Trends and Commercial Implications (2026–2032)
Looking ahead, three trends are likely to shape the next three to five years. First, electrification will deepen into a broader operational standard rather than a procurement preference. As zero-emission mandates and indoor air-quality regulations expand across more jurisdictions, and as lithium-ion technologies improve energy density and charging convenience, facilities will increasingly default to electric burden carriers for both material and personnel transport. This creates opportunity for providers that can deliver reliable charging integration, predictable uptime, and scalable fleet management.
Second, application convergence will accelerate. Vehicles that combine flatbed utility, higher towing capacity, multi-operator seating, and enclosed cabin options will become more valuable as facilities consolidate workflows and reduce the number of specialized assets. The commercial opportunity lies in designing platforms that can serve multiple roles without sacrificing safety, maneuverability, or payload integrity. Buyers will reward flexibility that lowers fleet complexity while maintaining operational resilience.
Third, cost and supply chain management will remain decisive. Even as iron ore price trajectories may ease some steel-related pressures, regional steel pricing, tariff effects, and component availability will continue to influence build economics and delivery timelines. Manufacturers that can stabilize input costs through modular design, strategic sourcing, and configurable options will gain an edge. For buyers, disciplined total cost of ownership analysis, charging infrastructure planning, and service network access will be essential to capturing value.
PW Consulting
Potential risks and uncertainties should not be overlooked. Regulatory timelines and enforcement intensity may diverge by region, creating uneven adoption curves. Supply chain disruptions could affect steel and component availability, influencing pricing and lead times. Safety and compliance expectations, anchored by standards such as ISO 3691-1, will continue to evolve, requiring ongoing validation and design discipline. Organizations that prepare for these dynamics—by diversifying sourcing, aligning procurement with regulatory trajectories, and investing in operator training and infrastructure—will be better positioned to navigate volatility and capitalize on growth.
Strategic Recommendations for Decision Makers
For manufacturers, the priority is to sharpen differentiation around payload flexibility, ergonomics, and application-specific safety while maintaining disciplined cost control. Modular architectures, configurable cabin and flatbed options, and clear compliance alignment can broaden addressable use cases without inflating complexity. Investing in charging compatibility, serviceability, and operator-centered design will strengthen long-term competitiveness as electrification becomes the default.
For investors, the growth profile suggests selective exposure to platforms that combine electric propulsion with multi-purpose capability and strong total cost of ownership narratives. Due diligence should focus on supply chain resilience, regulatory alignment, and the ability to serve high-growth application segments such as logistics, warehousing, and multi-role facility transport. Monitoring regional steel pricing, tariff dynamics, and component availability will help anticipate margin pressures and timing risks.
For procurement and operations leaders, the emphasis should shift from unit price to lifecycle value. Evaluating charging infrastructure needs, uptime expectations, maintenance models, and operator safety features will lead to more durable purchasing decisions. Aligning burden carrier selection with facility workflow, aisle constraints, and future expansion plans can reduce fleet complexity and improve throughput over time.
For organizations seeking deeper segmentation data, company-level benchmarking, and tailored guidance on deployment scenarios, a comprehensive research report is available to support detailed evaluation and planning.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Burden Carrier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Absorption Heat Pumps Market: Why Waste Heat Recovery Drives 5.62% CAGR
By pmarketresearch, 2026-09-18
The Worldwide Absorption Heat Pumps Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
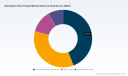
The global absorption heat pump market has demonstrated steady expansion over the past half-decade, moving from approximately 1.48 billion USD in 2020 to roughly 1.94 billion USD in 2025. The trajectory reflects a compound annual growth rate of about 5.6 percent through the 2026–2032 forecast horizon, with revenues projected to approach 2.85 billion USD by the end of the period. This growth is not uniform across time or geography; the market experienced a brief contraction in 2022 alongside broader industrial supply chain disruptions, followed by a rebound that accelerated into 2024 and 2025 as energy costs and decarbonization mandates reshaped procurement priorities. By 2032, the market is expected to cross the 2.8 billion USD threshold, signaling a structural shift rather than a cyclical upturn. The concentration of revenue among the top three players sits near 48 percent, while the top five collectively account for just over 62 percent, indicating a moderately consolidated landscape with room for specialized entrants and regional champions.
Despite the positive trajectory, the industry faces structural friction that will define competitive outcomes over the next several years. The first challenge is the uneven maturity of working fluid architectures. Water-lithium bromide systems dominate installed capacity because of their reliability and commercial availability, yet ammonia-water configurations offer distinct thermodynamic advantages for certain industrial and large-scale applications. The cost, handling requirements, and regulatory perception of these fluids create a bifurcated market where manufacturers must choose between standardization and performance differentiation. This split complicates scaling, because a platform optimized for one chemistry rarely translates seamlessly to the other without reworked components, certification, or service networks.
A second challenge is the dependency on heat source availability and infrastructure readiness. Absorption heat pumps are thermally driven, which means their economics hinge on access to waste heat, gas-fired inputs, solar thermal, or geothermal energy in forms that are predictable and cost-effective. Facilities with abundant industrial waste heat see rapid payback, but sites without such access must rely on fuel-based or solar-driven configurations, which introduce different cost profiles and operational assumptions. The mismatch between equipment capability and site conditions can stall projects even when efficiency targets are ambitious, turning what appears to be a straightforward retrofit into a feasibility exercise.
The third challenge is regulatory and incentive fragmentation. Energy efficiency programs, building codes, and tax provisions increasingly favor high-efficiency thermally driven systems and waste heat recovery, but the specifics vary by jurisdiction, project type, and compliance timeline. In some regions, updated HVAC efficiency requirements are reshaping which systems can be specified in new construction or major renovations, while in others, federal and state incentives create uneven adoption curves. This patchwork raises the cost of market entry and rewards players who can navigate local codes, documentation, and incentive structures with precision. The recent suspension of operations by a North American gas absorption heat pump manufacturer, while it explores strategic alternatives and asset sale options, illustrates how operational scale, partner ecosystems, and regional demand patterns can converge to create inflection points.
Key Drivers Behind Market Momentum
Technology innovation is reshaping the value proposition of absorption heat pumps by pushing efficiency boundaries and widening the range of usable heat sources. Multi-effect and high-efficiency absorption cycles are reducing primary energy consumption in applications where waste heat or gas-fired input is available, allowing operators to convert otherwise lost thermal energy into useful heating or cooling. Advances in heat exchanger design, control logic, and component durability are also improving part-load performance and reducing maintenance intensity, which matters increasingly for commercial and industrial operators who evaluate total cost of ownership rather than first cost alone. As manufacturers accumulate patent portfolios and field data across hundreds of installations, the credibility gap between absorption systems and conventional electric alternatives continues to narrow in niche applications where thermal integration is achievable.
Policy and regulatory momentum is another powerful driver. In markets that are tightening HVAC efficiency requirements or incentivizing decarbonized thermal systems, absorption heat pumps benefit from their ability to leverage waste heat, reduce electrical load, and lower direct emissions in specific configurations. Updated building codes that raise equipment efficiency thresholds can either create compliance pathways for thermally driven systems or raise the bar for integration and controls. Similarly, tax credits and efficiency programs that reward high-performance heat pump adoption provide a financial tailwind for projects that can demonstrate measurable energy savings. The strategic implication is that policy is not merely a background condition; it is becoming a design parameter. Manufacturers and project developers that align product roadmaps with evolving code cycles and incentive eligibility are better positioned to secure specification wins and shorten sales cycles.
Geothermal Heat Pump Market
Demand-side behavior is changing as well. Industrial operators are increasingly treating waste heat recovery as a strategic resource rather than a byproduct, especially where energy intensity and fuel volatility are persistent concerns. Commercial and residential segments are also showing greater interest in thermally driven options where gas availability, grid constraints, or decarbonization goals make electric compression systems less attractive in specific contexts. This demand evolution is shifting procurement discussions from narrow equipment comparisons to system-level outcomes: how much waste heat can be absorbed, how the system interacts with existing infrastructure, and how the operating profile aligns with long-term energy planning. The result is a more consultative buying process that rewards suppliers capable of engineering around site-specific heat sources and load profiles.
Supply chain and cost structure dynamics reinforce these shifts. The availability and pricing of key materials such as lithium bromide influence system economics, particularly for water-lithium bromide platforms that represent the larger share of installed capacity. At the same time, gas-fired and thermally driven configurations can become more attractive when electricity pricing is volatile or when waste heat is abundant enough to offset fuel input. Suppliers that can stabilize component sourcing, localize assembly where incentives favor it, and offer flexible drive configurations gain an advantage in projects where lead times and cost predictability are critical. The broader effect is a market in which cost leadership is increasingly tied to integration capability, material strategy, and the ability to match drive sources to local energy realities.
Competitive Landscape and Leading Strategies
The competitive field combines large global manufacturers with specialized leaders that have built deep expertise in particular working fluids, capacities, or end-use segments. Shuangliang Eco-Energy has established a strong position in industrial lithium bromide absorption heat pumps, accumulating a broad international installation base and a substantial patent portfolio focused on high-efficiency waste heat recovery and significant energy savings. Its strategy emphasizes long-cycle industrial deployments where proven performance and energy reduction claims are central to procurement decisions. Johnson Controls, through its YORK portfolio, offers a wide range of absorption chillers and heat pumps that can be driven by multiple heat sources, targeting commercial and industrial applications where waste heat utilization, water savings, and emissions reduction are priorities. Its long operating history gives it visibility across a broad set of building and facility types, which supports specification relationships and service continuity.
BROAD Group has scaled rapidly as one of the largest manufacturers of absorption chillers and heat pumps, with a product range that spans smaller commercial units to large industrial capacities and a strong focus on gas-fired and thermally driven systems. Its extensive global deployment base reflects an aggressive push into commercial, civil, and industrial markets, supported by volume manufacturing and a broad application footprint. Thermax Limited has carved out a position around advanced absorption chillers and triple-effect technology, emphasizing high-efficiency, multi-energy-driven systems for industrial use and exporting its capabilities across global markets. Robur S.p.A. distinguishes itself through gas absorption and ammonia-based heat pump and chiller solutions, with models designed to deliver high effective efficiency and a reduced carbon footprint in commercial and residential settings. Hope Deepblue, Ebara, and Berg Chilling Systems, including its partnership with World Energy, round out a field that spans lithium bromide systems, waste heat recovery pumps, and marine or exhaust-gas-driven configurations, each targeting specific performance, durability, or application requirements.
The strategic differentiation among these players is becoming clearer. Some compete primarily on proven industrial scale, patent depth, and waste heat recovery performance; others compete on portfolio breadth, multi-source drive capability, and brand recognition across commercial buildings; still others compete on specialized chemistries such as ammonia or on niche application engineering such as marine and offshore environments. The most resilient players are those that can translate technical differentiation into measurable operating outcomes and then support those claims with service, documentation, and local compliance knowledge. Price competition exists, but in many project categories the decisive factors are integration risk, heat source compatibility, and the ability to satisfy efficiency and code requirements without excessive customization.
The market structure is evolving along two converging paths. On one hand, consolidation pressure is rising among suppliers that need broader geographic coverage, service networks, and application libraries to win larger industrial and infrastructure projects. On the other hand, segmentation is deepening because working fluid choices, heat source types, and end-user requirements reward focused expertise. New entrants or asset-level moves, such as the recent North American situation involving a gas absorption heat pump manufacturer exploring a partner or asset sale, suggest that regional manufacturing footprints and brand continuity can become strategic assets in themselves. The likely outcome is a landscape where a handful of global platforms coexist with specialized leaders and regional capabilities, and where partnerships, distribution agreements, and selective acquisitions become common tools for expanding reach without abandoning technical focus.
Outlook for the Next Three to Five Years
Looking ahead, one defining trend will be the wider use of absorption heat pumps as part of integrated thermal hubs rather than standalone equipment purchases. Industrial facilities and large commercial campuses are increasingly viewed as systems where waste heat, cooling, heating, and sometimes solar or geothermal inputs can be coordinated. In that context, absorption heat pumps that can accept multiple drive sources and operate efficiently across variable loads will be favored, because they fit into broader energy orchestration strategies. The commercial opportunity lies in bundling equipment with feasibility assessment, control integration, and commissioning support, turning a hardware sale into a performance-based engagement with clearer payback certainty.
A second trend is the gradual expansion of ammonia-water and advanced multi-effect architectures in selected industrial and large-scale applications, alongside continued dominance of water-lithium bromide in mainstream commercial and many industrial settings. As operators seek higher effective efficiency or need to handle specific temperature and capacity ranges, the choice of working fluid will become more application-specific. This creates opportunities for suppliers that can offer certified, well-supported ammonia-based solutions where safety and handling requirements are manageable, as well as for manufacturers that continue to improve lithium bromide system efficiency and standardization. The uncertainty is that regulatory interpretation, operator familiarity, and service readiness will influence adoption speed, meaning that technical superiority alone will not guarantee market share without ecosystem support.
PW Consulting
A third trend is the widening but uneven impact of efficiency codes and incentives. As jurisdictions update HVAC requirements and extend fiscal support for high-efficiency heat pump applications, some regions will see faster project pipelines and stronger specification momentum, while others lag. This unevenness favors players who can localize documentation, support code compliance, and align product offerings with the incentive programs that matter locally. The main risk is that policy timing, program eligibility details, and equipment eligibility interpretations can shift, altering project economics after a pipeline has been planned. Companies that treat policy as a variable to monitor rather than a fixed assumption will be better able to sequence investments, adjust offerings, and protect margins.
Recommendations for Decision-Makers
For manufacturers, the strategic priority is to align product roadmaps with the most defensible demand pockets rather than chasing broad coverage. That means clarifying where waste heat recovery, gas-fired thermally driven systems, or solar/geothermal inputs provide a genuine economic edge, and then investing in the working fluid platforms, component supply stability, and application documentation that support those segments. Differentiation should be expressed in operating outcomes and integration ease, supported by service capacity and compliance knowledge that reduce project risk for buyers. Partnerships for regional distribution, asset continuity, or application-specific engineering can be more efficient than attempting to build every capability internally.
Air Source Heat Pumps Market
For investors, the opportunity is strongest where installed base, patent depth, and regional demand alignment converge, especially in industrial lithium bromide platforms, large-scale gas-fired systems, and specialized ammonia or multi-effect offerings that serve high-value niches. Due diligence should focus on heat source dependency risk, incentive exposure, material cost sensitivity, and the resilience of service and distribution networks, because those factors determine whether growth is sustainable through code cycles and energy price swings. Company-level transitions, such as asset reshuffling or relaunch efforts in specific regions, can create both risk and entry points, so valuation should weigh ecosystem continuity as heavily as technical claims.
For procurement and facility leaders, the priority is to evaluate absorption heat pump options on system-level economics rather than equipment-level specifications. Projects should be screened for heat source availability, compatibility with existing infrastructure, control integration needs, and eligibility for relevant efficiency incentives, with attention to the code cycles that affect new construction or major renovation. Where thermal integration is strong, absorption systems can deliver meaningful operational benefits; where heat source conditions are uncertain, the value proposition weakens quickly. In either case, engaging detailed market intelligence and segment-level data before committing to a technology path helps avoid overgeneralization and supports more accurate total cost of ownership comparisons across the options that matter for the project.
For detailed analysis of this topic, please visit the official page: Worldwide Absorption Heat Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
3D Printed Prosthetic Hands Market: Why 15.12% CAGR Drives $372M Growth by 2032
By pmarketresearch, 2026-09-18
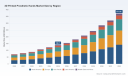
Global Strategic Outlook: The 3D Printed Prosthetic Hands Market
Market Current State and Core Challenges
The worldwide market for 3D printed prosthetic hands has entered a phase of accelerated expansion, driven by converging advances in additive manufacturing, growing clinical acceptance, and shifting reimbursement frameworks. Over the 2020 to 2025 period, the sector moved from a niche innovation space into a commercially viable segment within the broader prosthetic device industry. Market valuation climbed from approximately USD 71.4 million in 2020 to USD 138.7 million in 2025, reflecting sustained year-over-year growth that outpaces many traditional medical device categories. Looking ahead to the 2026 through 2032 forecast horizon, the trajectory points toward a valuation of roughly USD 371.66 million by 2032, supported by a projected compound annual growth rate of 15.12 percent. This momentum signals that additive fabrication is no longer an experimental alternative but a mainstream production pathway for upper-limb prosthetic solutions.
Several structural factors underpin this growth. The ability to produce patient-specific devices with reduced lead times and lower tooling costs has resonated across clinical and consumer channels. At the same time, advancements in printable materials, sensor integration, and lightweight design have expanded the functional envelope of what 3D printed hands can achieve. The market is also benefiting from broader alignment between technology readiness and healthcare system priorities, particularly the push toward personalized care, faster device delivery, and cost containment without sacrificing clinical quality.
Despite this favorable backdrop, the industry faces a set of interconnected challenges that will shape competitive outcomes over the next several years. The first challenge centers on standardization and regulatory clarity. While additive manufacturing has gained formal recognition as an acceptable fabrication method for custom prosthetic devices under major reimbursement programs, the operationalization of these approvals varies across jurisdictions and payer systems. Manufacturers must navigate device classification expectations, material biocompatibility documentation, and process validation requirements while maintaining the agility that makes 3D printing attractive in the first place. This creates a tension between rapid iteration and the documentation rigor demanded by healthcare procurement and reimbursement pathways.
The second challenge is the uneven distribution of clinical adoption and service infrastructure. High-growth potential in emerging regions is constrained by limited access to fitting expertise, post-delivery adjustments, and localized support networks. Even where devices are affordable to produce, the total cost of ownership for end users can rise sharply if follow-up care, sensor calibration, or socket modifications are difficult to access. This gap between manufacturing capability and service readiness remains a defining bottleneck, especially for body-powered and partial-hand solutions that depend heavily on precise fit and user training.
The third challenge relates to market fragmentation and competitive differentiation. With relatively low barriers to entering the design and printing space, a wide range of organizations—from startups and academic initiatives to established device makers—are pursuing overlapping value propositions. In such an environment, the winners are likely to be those who can combine clinical credibility, reimbursement fluency, and repeatable quality control rather than those who simply offer the lowest price or the most visually distinctive design. The market is therefore transitioning from an innovation-led phase into a maturity phase where execution discipline, evidence generation, and ecosystem partnerships will determine long-term positioning.
Prosthetic Foot Market
Key Growth Drivers Shaping the Market
Technology innovation remains the most visible driver of market expansion, but the nature of that innovation has shifted from proof-of-concept experimentation to clinically oriented engineering. Additive manufacturing now enables multi-grip mechanics, integrated sensing, and breathable or waterproof socket alternatives that improve comfort and usability. Components produced from specialized resins and engineered polymers support faster design cycles and more consistent mechanical performance. Touch-sensing capabilities and wireless electromyographic control illustrate how printed prosthetic hands are becoming more interactive and adaptable to daily tasks. These advancements are not merely cosmetic; they directly influence user satisfaction, adoption persistence, and the perceived value of prosthetic devices among clinicians and patients.
At the same time, material progress is reshaping cost and performance dynamics. Nylon-based and polyamide formulations processed through selective laser sintering and multi-jet fusion methods have become common in durable prosthetic hands and sockets because they offer a strong balance of mechanical resilience, reduced weight, and biocompatibility for patient-specific applications. The practical consequence is that manufacturers can move beyond prototype-grade outputs toward production-grade devices that withstand regular use while retaining customization flexibility. This material maturity reduces a long-standing barrier to adoption: the concern that additively manufactured devices may not match the durability expectations associated with conventionally fabricated prosthetics.
Regulatory and reimbursement developments are acting as a powerful accelerant. A pivotal shift occurred when additive manufacturing was formally recognized as an acceptable and reimbursable fabrication approach for custom prosthetic devices, including sockets, inserts, and additions, under Medicare alignment with existing coding structures. This recognition matters because it connects technological capability with commercial viability. For manufacturers and service providers, reimbursement eligibility transforms 3D printed prosthetics from a grant-dependent or out-of-pocket niche into a scalable clinical offering. It also encourages healthcare providers to incorporate additive fabrication into their procurement and fitting workflows, knowing that the method has been acknowledged within established coverage frameworks.
This regulatory tailwind does not eliminate compliance complexity, but it does reduce one of the largest sources of market uncertainty. Device makers still need to address quality system expectations, demonstrate substantial equivalence where applicable, and maintain product-specific documentation, yet the pathway for custom prosthetic devices produced through additive methods is now more clearly aligned with established reimbursement logic. The result is a more predictable environment for investment, production scaling, and clinical integration.
Demand-side changes are equally important. Patients and clinicians increasingly expect devices that are not only functional but also adaptable to individual anatomy, lifestyle, and aesthetic preferences. In pediatric and congenital limb difference populations, improved dexterity, range of motion, and reduced co-activation have been associated with better user experience and functional outcomes. These clinical observations reinforce demand for devices that can be refined quickly and fitted more precisely than many conventional alternatives. Meanwhile, individual users, families, and nonprofit organizations continue to seek lower-cost options that do not sacrifice essential function, expanding the addressable market beyond hospital and clinic settings.
Supply chain and cost structure shifts are reinforcing these demand trends. In-house additive manufacturing and targeted partnerships with printing technology providers allow companies to compress production cycles, reduce inventory risks, and respond more quickly to design refinements. Scaling up printing capacity within controlled manufacturing environments supports cost reduction while preserving the advantages of customization. For businesses, this means the traditional trade-off between mass production efficiency and individualized fit is becoming less severe. The organizations that can manage design standardization, repeatable printing processes, and post-processing quality will be best positioned to translate technical potential into reliable commercial output.
Competitive Landscape and Leading Strategies
The competitive field is diverse, but a clear pattern is emerging: successful players are differentiating through a combination of clinical approval, reimbursement alignment, material and sensor innovation, and service-oriented distribution models. One prominent approach is represented by companies focused on clinically approved, insurance-reimbursed multi-grip myoelectric hands and arms with customizable covers and activity attachments. Their emphasis on lightweight construction, expressive design, and clinically integrated sockets illustrates how commercial credibility and user experience can be pursued together. By maintaining a family of models suited to different environments and user needs, these players aim to broaden adoption while preserving a consistent brand and quality proposition.
A second strategic orientation emphasizes speed, durability, and sensory feedback. Some manufacturers are building lightweight bionic hands with touch-sensing capability using 3D printed major components, then scaling in-house printing capacity to drive down unit costs and accelerate iteration. The commercial logic here is compelling: faster production and lower cost can expand access, while touch feedback and rapid responsiveness enhance functional value. This model also benefits from strong alignment with reimbursement developments, since Medicare coverage for such devices supports broader deployment and reduces reliance on limited grant-based channels.
3D Printed Face Shields Market
A third orientation focuses on partial-hand and body-powered solutions for users who need targeted functional restoration rather than full-hand replacement. These offerings often rely on durable nylon-based additive manufacturing and emphasize custom fit, daily-task performance, and mechanical reliability. The strategic value lies in serving a specific patient population with a clear functional need, where fit precision and task-specific design can create strong clinical loyalty and repeat engagement through adjustments and accessory use.
Beyond commercial manufacturers, nonprofit and community-oriented models are also shaping the landscape. Some organizations center their work on low-cost fabrication and localized training in underserved regions, partnering with clinics to enable custom fitting and delivery. Others concentrate on personalized, EMG-powered devices for children and adults, frequently incorporating expressive designs and collaborating with hospitals through clinical trial and partnership frameworks. These initiatives broaden access and generate real-world usage data, while also highlighting the importance of service networks, training, and long-term support in markets where device cost is only one part of the adoption equation.
Taken together, the field is neither fully consolidated nor chaotically fragmented. Concentration metrics indicate that larger players hold meaningful but not dominant shares, leaving substantial room for differentiation and selective consolidation. The market is likely to evolve through a mix of vertical integration, partnership formation, and specialization. Vertical integration can reduce cost and improve quality consistency by consolidating socket, arm, and hand production within a controlled environment. Partnerships can extend reach into clinical networks, rehabilitation settings, and regional service ecosystems. Specialization will remain attractive for companies that can own a specific need segment, whether that is pediatric expression, partial-hand function, touch-enabled myoelectric control, or low-cost deployment in underserved areas.
The most consequential trend in competitive strategy is the shift from design novelty to deployment credibility. In a market where multiple organizations can produce visually impressive devices, durable advantage will increasingly depend on reimbursement competence, clinical evidence, regulatory readiness, and the ability to deliver consistent post-fit support. Companies that treat 3D printing as a complete operational system—encompassing design controls, material selection, production scaling, and service infrastructure—will be better positioned than those that treat it as a standalone fabrication shortcut.
Future Trends to Watch Over the Next 3 to 5 Years
One major trend is the continued convergence of reimbursement alignment and manufacturing scale-up. As additive fabrication becomes more firmly embedded in covered prosthetic workflows, companies that can demonstrate repeatable quality, appropriate documentation, and reliable supply will be able to expand more confidently. This should favor organizations that invest early in process validation, material traceability, and clinical integration rather than those relying primarily onDesign-led differentiation. Over time, the market is likely to reward players who can show that printed prosthetics can be delivered consistently across sites, user populations, and reimbursement environments.
A second trend is the widening role of smart features and user-centered customization. Touch sensing, improved electromyographic control, modular activity attachments, and comfort-focused socket designs are expected to become more common as manufacturers refine both hardware and user experience. The commercial implication is that value will shift not only from basic grasp function to broader quality-of-life benefits, including adaptability, comfort, and ease of use. This creates opportunities for companies that can package sensor, software, and design improvements into coherent products rather than isolated technical features.
PW Consulting
A third trend is the growth of hybrid delivery models that blend centralized manufacturing with localized fitting and support. In regions where reimbursement and clinical infrastructure are developing, the ability to train local partners, support regional printing or assembly, and maintain follow-up care can determine whether products achieve scale. This approach may also help address the service-readiness gap identified earlier, especially for body-powered and partial-hand devices where fit and user training strongly influence outcomes. At the same time, there is risk that uneven regulatory interpretation, material supply constraints, or inconsistent service quality could slow expansion if not managed carefully.
These trends point to a market that is moving toward broader clinical acceptance and more structured commercialization, but not without friction. Uncertainty remains around how quickly payers and providers will standardize around additive workflows, how consistently quality can be maintained across expanding production networks, and whether smart-feature enhancements will translate into measurable functional gains that justify premium positioning. Companies that monitor these dynamics closely will be better prepared to time investments and prioritize the most resilient opportunities.
Strategic Actions for Decision Makers
For manufacturers, the priority is to build a credible operating model around additive prosthetic production, not just a compelling product concept. That means investing in process standardization, material selection, quality documentation, and reimbursement fluency alongside design innovation. Companies should also assess whether they can strengthen positioning through vertical integration, clinical partnerships, or targeted specialization in a high-need segment such as partial-hand restoration, pediatric use, or touch-enabled myoelectric control. The businesses most likely to scale will be those that can prove repeatability and service reliability in addition to performance.
For investors, due diligence should focus on reimbursement readiness, regulatory pathway clarity, manufacturing scalability, and evidence of clinical adoption beyond early adopters. Interest in the sector should be calibrated to teams that understand the operational demands of custom medical device production and can show a realistic route from prototype to consistent delivery. Portfolio exposure may be most effective where it supports companies with clear differentiation, defensible quality systems, and credible plans for service delivery and post-fit support.
For procurement leaders and healthcare organizations, the practical task is to evaluate additive prosthetic options against total value rather than initial device cost alone. Factors such as fitting turnaround, adjustment support, sensor calibration, durability documentation, and alignment with reimbursement codes can materially affect outcomes and total cost of ownership. Engaging early with suppliers that can provide transparent process controls and service commitments will help organizations integrate 3D printed prosthetic hands into clinical pathways with greater confidence.
Given the pace of regulatory, reimbursement, and technology change, decision makers benefit from continuously updated segmentation, competitive mapping, and region-specific adoption dynamics. More detailed data on market size by segment, company positioning, and forward scenarios can support more precise planning and reduce exposure to blind spots in a rapidly evolving market. For that reason, accessing a comprehensive research report can provide the granular context needed to translate these high-level trends into actionable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide 3D Printed Prosthetic Hands Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Why Stainless Steel Vacuum Flasks Grow at 5.24% CAGR: Market Drivers Exposed
By pmarketresearch, 2026-09-18
Global Stainless Steel Vacuum Flask Market: Strategic Trends and Commercial Opportunities (2025–2032)
The worldwide market for stainless steel vacuum flasks has entered a phase of steady consolidation, with total revenue projected to reach approximately 5.6 billion USD in 2025. Over the historical window from 2020 through 2025, the sector expanded from roughly 4.35 billion USD to its current baseline, reflecting consistent demand across consumer, corporate, and outdoor segments. Looking ahead to the forecast period spanning 2026 through 2032, the market is expected to progress toward 8.04 billion USD by the end of the decade, translating to a compound annual growth rate of approximately 5.24 percent. This trajectory signals a maturing but still expanding category where volume growth increasingly intersects with premiumization, regulatory scrutiny, and supply chain recalibration. For executives and investors, the near-term opportunity lies not in chasing undifferentiated volume, but in aligning product architecture, distribution strategy, and risk management with the structural shifts reshaping end markets. The data points to a market where scale advantages remain valuable, yet differentiation in materials, safety compliance, and channel mix increasingly determines margin resilience.
Despite the constructive growth outlook, the industry faces a set of compounding challenges that will test operational agility. First, commodity volatility has placed sustained pressure on cost structures. Stainless steel and nickel price movements over the past year have compressed margins for producers who lack flexible procurement models or the ability to pass through costs without eroding volume. Second, consumer safety expectations and regulatory oversight are tightening, as evidenced by high-profile product recalls that underscore the operational and reputational risks embedded in mass-market insulated drinkware. Third, the competitive field remains highly fragmented at the top but concentrated enough in aggregate that pricing power is unevenly distributed. With the top three players accounting for roughly 18.45 percent of market revenue and the top five reaching approximately 26.32 percent, no single entity dominates the category outright. This fragmentation creates both opportunity for strategic consolidation and risk for brands that cannot sustain clear differentiation. Collectively, these dynamics mark a turning point where efficiency, compliance, and brand positioning must advance together rather than in isolation.
Key Drivers Shaping the Market Trajectory
Technological Innovation and Material Longevity
Innovation in insulation architecture, surface engineering, and assembly precision continues to redefine what consumers expect from a vacuum flask. Manufacturers are progressively integrating 304 and 316 stainless steel formulations, double-wall vacuum sealing refinements, and latch or lid mechanisms designed to improve durability under repeated use. These advances are not merely aesthetic; they directly affect heat retention, condensation control, and product lifecycle, which in turn influence repeat purchase behavior and brand loyalty. The recent showcase of updated 2025/26 collections featuring advanced insulation profiles and custom ODM/OEM configurations at major industry exhibitions highlights how producers are converting technical capability into commercial flexibility. For downstream brands, this means access to increasingly modular component sets that can be tailored for specific use cases, from desk-side hydration to expedition-grade applications. The strategic implication is clear: firms that treat material science and engineering as a core differentiator rather than a commodity input are better positioned to command price premiums and reduce sensitivity to raw material swings.
Policy, Safety Standards, and Regulatory Expectations
Regulatory attention around durable consumer goods is intensifying, particularly where product failure can result in injury. Recent recall actions involving food jars and beverage bottles due to impact and laceration hazards demonstrate how quickly compliance gaps can translate into financial exposure and reputational damage. In response, manufacturers and brand owners are re-evaluating quality assurance protocols, component sourcing, and post-market monitoring. This environment favors organizations that embed safety and traceability into the design and production cycle from the outset, rather than treating them as downstream checks. For market entrants and established players alike, the regulatory trajectory suggests that documentation, testing rigor, and transparent communication will become table stakes for sustained access to retail and e-commerce channels, especially in higher-scrutiny destinations. Companies that proactively align with evolving standards can convert compliance into a competitive moat, while those that rely on reactive corrections face mounting operational and brand risk.
Stainless Steel Bottle Market
Demand-Side Shifts and Consumption Patterns
Consumer behavior is shifting toward products that combine everyday utility with longer service life and lower environmental footprint. Hydration routines are increasingly integrated into work, travel, fitness, and outdoor lifestyles, and stainless steel vacuum flasks benefit from a perception of durability that aligns with broader sustainability preferences. This demand environment supports growth across multiple capacity ranges, with mid-to-large formats capturing meaningful usage in professional and family settings, smaller volumes sustaining portability-driven segments, and oversized options serving specialized outdoor and group-use contexts. Distribution dynamics reinforce this pattern: online retail channels have emerged as a dominant route to market, while supermarkets and hypermarkets continue to provide broad reach, and specialty stores contribute through curated, premium positioning. The result is a demand landscape where product design, channel strategy, and brand storytelling must operate in concert. Brands that understand how different consumer cohorts evaluate performance, aesthetics, and trust are better equipped to allocate marketing spend and inventory toward the highest-return combinations.
Stainless Steel Vacuum Bottle Market
Supply Chain, Sourcing, and Cost Structure Evolution
Trade flows and manufacturing geography remain central to the market’s cost and risk equation. A substantial share of vacuum flasks and related components continues to originate from a concentrated set of exporting economies, with China supplying the overwhelming majority of imports into key destination markets such as the United States. This concentration offers scale and speed but also exposes buyers and producers to logistics disruption, tariff uncertainty, and input price variability. At the same time, elevated stainless steel prices over the past year have challenged cost structures, prompting manufacturers to explore dual sourcing, negotiated contract terms, and design-for-cost adjustments without sacrificing insulation performance. The strategic response among leading producers has been to balance high-volume OEM/ODM capabilities with selective premium lines that can absorb cost pressures more effectively. For procurement leaders and brand owners, this environment rewards supply chain visibility, scenario planning, and relationships with manufacturers that can scale across both commodity and specialty requirements.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive field spans globally recognized brands, technology-oriented premium manufacturers, and large-scale OEM/ODM suppliers operating across multiple regions. Thermos maintains a strong presence through broad portfolio coverage and a heritage in vacuum insulation technology, serving consumer and outdoor segments with recognizable brand equity. Tiger Corporation and Zojirushi represent the premium Japanese end of the market, emphasizing high-performance retention, refined design, and durable construction that appeals to discerning buyers willing to pay for reliability. In the United States, Hydro Flask, Klean Kanteen, and YETI have carved out distinct positions: Hydro Flask leans into active-lifestyle aesthetics and powder-coated finishes; Klean Kanteen emphasizes recyclable stainless steel and eco-conscious positioning; and YETI targets the premium outdoor segment with rugged construction and strong brand cachet. On the manufacturing side, Zhejiang Haers and Guangdong Sibao reflect the scale and heritage of Chinese production, with Haers serving a broad base of global brands through high-volume insulated drinkware and Sibao drawing on early leadership in vacuum insulated and magnetization cup technologies. Shanghai Tiger Electronics, operating under Japanese investment, extends quality-focused production for domestic and export markets, while Turkish producer Steel Termos serves regional and cross-regional demand with an emphasis on OEM production for Turkey, the Middle East, Europe, and Latin America. Mountop Bottle and LAIKOE further illustrate the breadth of specialized manufacturing capabilities, with Mountop oriented toward premium ODM/OEM bottles for global distributors and LAIKoe focusing on 18/8 food-grade stainless steel for thermos-style flasks and bottles.
The strategic positioning of these players reveals a market where leadership is increasingly defined by the ability to balance scale, quality, and brand narrative. Premium manufacturers differentiate through insulation performance, finish quality, and design credibility, while high-volume producers compete on cost efficiency, customization capacity, and reliability across large orders. This dual structure creates a spectrum of opportunities: brands that want shelf impact and premium pricing tend to partner with or emulate the design-led, performance-focused segment, while retailers and distributors that prioritize breadth and margin stability often rely on manufacturers with robust OEM/ODM infrastructure. Recent market events have reinforced the importance of operational discipline. High-profile recall actions have drawn attention to the need for rigorous quality control, component validation, and post-sale responsiveness, particularly for products sold at scale in consumer channels. At the same time, the continued presentation of advanced 304/316 stainless steel insulation and custom design options at major trade exhibitions signals that manufacturing capabilities are becoming more adaptable, allowing brand owners to move faster on limited editions, regional variations, and co-developed specifications. The competitive trend points toward selective consolidation among manufacturers seeking broader geographic reach and greater customization capability, alongside continued fragmentation at the brand level as new entrants test niche positioning in outdoor, wellness, and sustainable consumption segments.
Future Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by three interrelated trends. First, premiumization will continue to gain share, but in a more disciplined form. Consumers are willing to pay for better retention, better finishes, and better durability, yet they are also more alert to product safety and brand credibility. This suggests that premium strategies will need to be supported by verifiable quality claims, consistent manufacturing standards, and transparent communication rather than marketing alone. The commercial opportunity lies in creating tiered portfolios that preserve accessible entry points while building higher-margin lines anchored in performance and design. Second, channel convergence will accelerate. Online retail will keep expanding its role in discovery and repeat purchase, but physical retail and specialty outlets will remain important for touch-and-feel evaluation and brand positioning. Companies that integrate inventory, merchandising, and customer data across channels will be better positioned to manage demand volatility and optimize promotion timing. Third, supply chain resilience will move from a cost center to a strategic asset. With concentrated sourcing in key exporting regions and persistent input cost pressure, firms that diversify supplier bases, lock in flexible contracts, and use design to moderate material intensity will enjoy more stable margins and faster response times. The associated risk is that any disruption in logistics, trade policy, or raw material availability can quickly ripple through pricing and fulfillment, especially for brands heavily reliant on a single sourcing corridor. Mitigation will therefore depend on scenario planning, safety stock discipline, and explicit coordination between product, procurement, and sales functions.
Strategic Recommendations for Decision Makers
For manufacturers and brand owners, the priority is to embed quality and differentiation into the product architecture before scale becomes the sole focus. This means investing in insulation consistency, lid and latch reliability, and finish durability, while building a tiered offering that can address both volume-driven and premium-oriented demand. Firms should also treat safety and compliance as core capabilities, with documentation, testing, and post-market monitoring aligned to the expectations of the most stringent retail environments. For investors, the attractive opportunities are likely to be found in companies that combine defensible brand equity with flexible manufacturing partnerships and a clear route-to-market strategy. Due diligence should weigh channel mix, margin resilience under input cost pressure, and the ability to scale custom programs without compromising quality. For procurement and distribution leaders, the goal is to reduce concentration risk while preserving access to innovation. That entails diversifying supplier relationships across regions and capacity types, clarifying service-level expectations, and partnering with manufacturers that can support both standard replenishment and specialized co-development. Across all roles, timely access to granular market, segment, and competitive data can sharpen prioritization and reduce blind spots. For decision makers seeking deeper segmentation detail, region-specific dynamics, and customized scenario analysis, the full PW Consulting research report provides a more comprehensive view of the market’s structure, competitive moves, and forward-looking opportunities.
For detailed analysis of this topic, please visit the official page: Worldwide Stainless Steel Vacuum Flask Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
FPD Lithography Systems Market: Why 5.71% CAGR and APAC's 85% Share Redefine Global Competition
By pmarketresearch, 2026-09-18
Worldwide FPD Lithography Systems Market: Strategic Trends and Commercial Opportunities Through 2032
Market Context and Core Challenges
The global market for flat panel display lithography systems has expanded steadily over the past five years, with total revenue reaching approximately $4.28 billion in 2025 and projected to grow at a compound annual growth rate of 5.71 percent through 2032. This trajectory reflects sustained capital investment in display manufacturing capacity, driven by demand for larger, higher-resolution, and more specialized screens across consumer electronics, automotive, and commercial applications. Asia Pacific dominates absolute market volume due to the concentration of panel fabrication facilities and equipment procurement clusters, while North America, Europe, and other regions maintain smaller but strategically important installations, often tied to specialized display formats, defense-related applications, or regional supply chain diversification efforts.
Within this landscape, the competitive structure remains highly concentrated. A small number of established suppliers account for the overwhelming majority of shipments, reflecting the capital intensity, precision engineering requirements, and long qualification cycles associated with lithography equipment. This concentration provides stability in service and support ecosystems but also constrains rapid price competition and slows the entry of alternative technology approaches. At the same time, the product mix continues to be shaped by the relative demand for steppers and scanners, with each architecture serving distinct patterning needs depending on panel size, resolution targets, and throughput requirements.
Several structural challenges define the current inflection point. First, panel manufacturers are navigating a period of mixed demand signals, where near-term investment timing is being reassessed as buyers evaluate the impact of trade policy shifts and downstream consumption patterns. This has introduced short-term volatility in equipment order books, even as the medium-term build-out of advanced display capacity continues. Second, environmental and chemical compliance frameworks are reshaping process choices. Regulatory pressure to reduce hazardous substances in lithography-related consumables and cleaning steps is increasing validation costs and influencing equipment design, particularly for suppliers serving multiple regulatory jurisdictions. Third, the boundary between display patterning and advanced packaging is blurring as multi-lens lithography concepts are adapted for back-end semiconductor processes. This cross-pollination creates both opportunity and complexity, as equipment roadmaps must increasingly account for applications that extend beyond traditional panel lines. These dynamics mean that market growth cannot be understood purely as a function of capacity expansion; it now depends on how well suppliers and buyers align technology choices with evolving regulatory, geopolitical, and application-specific requirements.
Key Drivers Shaping Market Change
Technology innovation remains the most direct catalyst for differentiation in FPD lithography. Multi-lens architectures, improved overlay control, and new light-source optimizations are enabling higher throughput and finer definition on larger substrates. Recent product announcements illustrate this direction clearly. In late 2025, Nikon began accepting orders for Gen 8 FPD lithography systems using UV-LED light sources, with a commercial launch planned for 2026. These models emphasize reduced power consumption alongside high-definition LCD and OLED panel production, signaling a shift toward energy efficiency as a competitive attribute rather than a secondary consideration. The same multi-lens lineage is also being extended into back-end semiconductor packaging, where a digital lithography system announced in mid-2025 targets one-micron resolution and high productivity. This dual-use technology strategy broadens the addressable market for core optical and mechanical competencies while reinforcing the value of established engineering know-how.
PW Consulting
Policy and regulatory conditions are equally influential. Export controls on advanced semiconductor manufacturing equipment have expanded to cover certain lithography systems and components, with restrictions targeting specific entities and broader categories such as DUV and advanced packaging tools. These measures reshape cross-border equipment flows, encourage regional sourcing strategies, and increase the importance of compliance infrastructure for both suppliers and end users. At the same time, European chemical regulations continue to constrain the use of certain hazardous materials in lithography-adjacent processes. While these frameworks do not directly ban FPD lithography machines, they raise compliance costs and influence material selection, cleaning protocols, and vendor qualification timelines. For global suppliers, the practical implication is that product support cannot be decoupled from jurisdictional readiness; systems that can be deployed with fewer material and documentation risks gain an advantage in multi-region programs.
Demand-side behavior is evolving as display applications diversify. Automotive dashboards, ruggedized interfaces, and specialty display formats are increasing interest in larger-area panel processing, while smartphone and portable device requirements continue to drive volume in smaller and medium panel segments. This split is not merely a matter of substrate size; it affects cycle times, yield expectations, and the relative importance of overlay precision versus throughput. Buyers are increasingly selecting equipment based on application fit and total cost of ownership rather than on headline specifications alone. As a result, suppliers that can demonstrate predictable performance across multiple panel formats, with flexible light sources and robust service networks, are better positioned to capture multi-year deployment cycles.
Worldwide Direct-write Photolithography Systems Market
Supply chain and cost structure considerations further shape the market. Panel makers are balancing the desire for cutting-edge capability with the need to manage capital exposure, especially when macroeconomic signals or tariff environments introduce uncertainty. This has led to more deliberate investment pacing, with buyers weighing whether to accelerate capacity, defer purchases, or select systems that offer broader compatibility across current and future panel generations. For equipment vendors, this environment rewards designs that reduce operating energy, simplify consumables handling, and provide modular upgrade paths. The net effect is a market where technical performance still matters profoundly, but commercial resilience—through lower running costs, flexible configuration, and regulatory adaptability—is becoming equally important in procurement decisions.
Competitive Landscape and Leading Strategies
The competitive structure in FPD lithography systems is anchored by a small group of incumbent suppliers with deep optical, mechanical, and process-integration expertise. Nikon maintains a prominent position through its FX-series platform for large-area plates, and its recent focus on UV-LED light sources reflects an effort to align performance with energy efficiency and high-definition panel requirements. The company's expansion of multi-lens technology into digital lithography for back-end packaging also illustrates a broader strategy: leverage core optical competencies across adjacent markets to extend revenue potential and amortize development costs. Canon continues to compete with mirror-projection systems designed for array, color filter, and touch panel processes, with recent releases supporting Gen 6 plates for dashboard displays and smartphones. This product emphasis highlights a strategy centered on application-specific productivity and overlay accuracy for high-volume consumer and automotive display segments.
A third dimension in the landscape comes from domestic equipment development in China, where suppliers are building FPD lithography capabilities as part of broader semiconductor and display equipment initiatives. This development introduces a longer-term dynamic around regional self-sufficiency and localized support ecosystems. While the established incumbents still dominate overall shipment value, the presence of new and expanding suppliers can influence pricing expectations, service competition, and the pace at which regional buyers diversify their vendor base. The practical outcome is a market that remains concentrated but is gradually being tested by localized capability building, especially where policy incentives and domestic panel expansion reinforce demand for homegrown equipment alternatives.
Looking at strategic positioning, the leading suppliers are differentiating along three axes. The first is platform versatility, where the ability to serve multiple panel sizes and light-source configurations reduces the risk of stranded investment for buyers. The second is application extension, where technology reuse across FPD and advanced packaging broadens the commercial base and creates cross-functional engineering leverage. The third is compliance and support readiness, where suppliers that can navigate export control frameworks, chemical regulations, and regional service expectations are better equipped to sustain multi-country programs. These axes matter because FPD lithography is not a purely specification-driven purchase; it is a long-cycle capital decision shaped by qualification timelines, process integration, and operational risk. In that context, suppliers that deliver predictable performance with lower regulatory and energy-related friction are likely to capture disproportionate share in multi-year deployment cycles.
Future Trends and Commercial Implications
Over the next three to five years, the market is likely to consolidate around a few durable trends. The first is the continued migration toward energy-efficient light sources and process optimizations that lower operating costs without sacrificing throughput or definition. As panel makers face both cost pressure and sustainability expectations, equipment that reduces power consumption while maintaining high-definition output will become a stronger differentiator in procurement evaluations. The second trend is the growing relevance of multi-lens and digital lithography concepts beyond traditional panel lines. As back-end packaging and specialty patterning applications adopt similar optical architectures, suppliers with adaptable platforms can capture incremental demand and create cross-market roadmap synergies. This expansion also increases the strategic importance of resolution, overlay stability, and productivity in a wider set of use cases.
Flat Panel Display (FPD) Inspection Equipment Market
The third trend is a more regionally differentiated market rhythm. Export controls, aligned policy actions, and shifting tariff environments are prompting panel manufacturers and equipment buyers to reassess procurement timing and vendor selection. In the near term, this can manifest as temporary pauses in investment as buyers gauge downstream demand and policy impacts. Over a longer horizon, it is likely to encourage more diversified sourcing strategies and greater emphasis on regional support, documentation readiness, and compliance-compatible configurations. The commercial opportunity here lies in aligning product roadmaps with deployment realities: systems that can be integrated quickly across multiple regulatory contexts, supported locally, and scaled across panel formats will be better positioned to win in a fragmented but still growing market.
Potential risks should not be underestimated. Demand timing remains sensitive to consumer electronics cycles, automotive display programs, and broader trade policy uncertainty. Chemical and environmental compliance costs may rise further, particularly for suppliers operating across multiple jurisdictions. And while platform versatility is valuable, overextension into adjacent applications can strain engineering resources if qualification and service commitments are not matched to market readiness. The commercial implication is that growth will increasingly accrue to participants who can balance technical ambition with operational pragmatism, selecting where to lead on performance and where to compete on total cost of ownership and deployment flexibility.
Strategic Actions for Decision Makers
For display and equipment manufacturers, the priority is to align product and capacity planning with the applications that offer the best balance of volume, margin, and regulatory compatibility. This means evaluating light-source efficiency, multi-panel flexibility, and service readiness as first-order decisions rather than secondary features. For investors, the opportunity lies in identifying participants with durable platform reuse, strong compliance infrastructure, and credible paths into adjacent packaging or specialty patterning applications, while monitoring demand-pacing signals that can affect near-term order visibility. For procurement teams and panel makers, the focus should be on total cost of ownership across the deployment lifecycle, including energy consumption, consumables and chemical compliance, qualification lead times, and regional support coverage. In a market where investment timing is increasingly sensitive to policy and demand uncertainty, detailed visibility into product roadmaps, regulatory impact, and application-specific requirements can materially improve capital allocation decisions. A closer review of the full market data set, including segmentation detail and company-level developments, can help decision makers sharpen those choices with greater precision.
For detailed analysis of this topic, please visit the official page: Worldwide FPD Lithography Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Graphene Electric Floor Heating Market: 14.85% CAGR and $1.67B Trajectory
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Graphene Electric Floor Heating Market
Market Overview and Core Challenges
The worldwide graphene electric floor heating market has entered a phase of accelerated expansion, moving from a niche technological concept to a commercially viable heating solution. Valued at approximately USD 634.52 million in 2025, the market has demonstrated consistent growth since 2020, when revenues stood at 315.6 million. The trajectory suggests a compound annual growth rate of 14.85 percent through 2032, with projected revenues reaching 1,672.41 million by the end of the forecast period. This growth curve indicates that graphene-based heating is no longer merely an alternative but is becoming a significant component of the broader electric heating ecosystem.
The market structure reveals a fragmented landscape despite the rapid revenue expansion. Concentration ratios remain relatively low, with the top three players holding approximately 18.25 percent of the market and the top five capturing 27.6 percent. This fragmentation suggests that while leading innovators are carving out strong positions, significant room remains for consolidation or for new entrants to capture share through differentiated technology or regional focus. The revenue base is heavily weighted toward specific product forms and applications, indicating where commercial adoption is currently most mature.
Several critical challenges define the current industry inflection point. First, the translation of laboratory-grade graphene performance into consistent, scalable manufacturing remains a hurdle. While thermal efficiency claims are strong, maintaining uniform dispersion of graphene within heating films or mats across large production runs requires precise process control. Variability in material quality can impact heating consistency and product longevity, creating a barrier for widespread adoption in commercial and industrial settings where reliability is paramount.
Second, the market faces a certification and standardization gap. Although multiple manufacturers hold international certifications such as RoHS, REACH, CE, UL, and TUV, the absence of a single unified global standard for graphene heating performance can complicate cross-border trade and procurement decisions. Buyers in regulated sectors often require extensive verification, slowing deployment cycles. As the market scales, harmonized standards will likely become a competitive differentiator rather than just a compliance checkbox.
Underfloor Heating Market
Third, the integration of graphene heating into existing building infrastructure presents both an opportunity and a friction point. Modular designs that enable retrofitting without significant floor height loss are emerging, yet widespread adoption requires alignment with construction workflows, electrical system capacities, and installer training. The labor cost savings associated with simplified installation are compelling, but realizing these savings at scale depends on industry-wide familiarity with the technology and reliable supply chains for compatible flooring and control systems.
Key Drivers of Market Dynamics
The expansion of the graphene electric floor heating market is propelled by a convergence of technological breakthroughs, regulatory momentum, shifting demand patterns, and evolving supply chain economics. Each driver reinforces the others, creating a self-accelerating adoption cycle in specific regions and applications.
Technological Innovation and Performance Breakthroughs
Graphene materials have enabled far-infrared conversion rates reaching up to 76 percent in electric floor heating systems, supporting high thermal efficiency with power density around 16W/m²/h for building-area calculations. This efficiency profile translates into faster heat-up times, more even heat distribution, and the potential for energy savings of 50 to 70 percent compared to conventional systems in real-world trials. These performance characteristics are not merely technical specifications; they directly address the core value proposition that building owners and occupants care about: comfort, control, and operating cost reduction.
Recent commercial milestones illustrate how technology is crossing the valley from prototype to deployed reality. In December 2024, a real-world deployment at Eden House respite care home demonstrated 50 percent less energy consumption than a gas boiler, providing tangible evidence of operational savings in a setting where heating reliability and efficiency are critical. The scientific and economic case for this approach was formalized in a white paper released in March 2025, strengthening the narrative for procurement teams and investors evaluating the technology's maturity.
Product certification progress further signals commercial readiness. The launch of a graphene underfloor heating system with UL certification in April 2025 removed a significant barrier for market entry in regions where safety and performance validation is mandatory. By mid-2025, the manufacturer had secured UL certification, positioning the product for broader commercialization in North American and other regulated markets.
Policy and Regulatory Environment
Regulatory frameworks and sustainability mandates are reshaping heating procurement decisions globally. Graphene underfloor heating systems comply with international standards including RoHS, REACH, CE, UL, and TUV certifications, ensuring no electromagnetic radiation or harmful emissions. This compliance profile aligns with tightening building codes and indoor air quality requirements, making graphene heating an attractive option for projects that must meet stringent environmental and safety criteria.
The broader macro trend toward net-zero goals provides additional tailwinds. Graphene-based electric floor heating supports decarbonization objectives through faster heat-up times, even distribution, and potential energy savings that reduce overall electricity demand. In regions where electrification of heat is being prioritized over fossil fuel systems, the efficiency advantages of graphene heating strengthen the economic case for adoption. Policy incentives for energy-efficient renovations, low-carbon heating installations, and smart building integration are likely to amplify demand, particularly in markets where retrofit activity is accelerating.
Demand-Side Shifts in Consumer and Enterprise Behavior
Demand is being shaped by a dual dynamic: residential consumers seeking comfortable, energy-efficient heating solutions and commercial entities under pressure to reduce operating costs while meeting sustainability targets. The residential segment currently represents the largest application base, reflecting the technology's suitability for homes where even heat distribution and zone-level control deliver noticeable comfort improvements. However, the commercial segment is gaining momentum as facility managers evaluate heating upgrades that can deliver measurable energy savings and align with corporate ESG commitments.
The industrial segment, while smaller in current revenue terms, represents a strategic frontier. Applications requiring uniform radiant heat in controlled environments, such as drying processes or specialized manufacturing spaces, could benefit from graphene heating's efficiency and modularity. As operators in these sectors look to reduce energy intensity and improve process control, graphene-based solutions may find niche but high-value deployments.
Consumer and buyer behavior is also being influenced by the growing availability of verified performance data. The shift from theoretical efficiency claims to documented case studies, such as the Eden House deployment, reduces perceived risk for early adopters. As more real-world evidence accumulates, procurement cycles are likely to shorten, particularly in sectors where heating costs are a significant line item.
Supply Chain and Cost Structure Evolution
The supply chain for graphene electric floor heating is evolving from fragmented, region-specific production toward more integrated value chains that emphasize material consistency, certification readiness, and installation simplicity. Modular graphene electric underfloor heating designs enable easy DIY or retrofit installation without occupying floor height, reducing labor requirements for installation and maintenance. These design advantages directly impact total cost of ownership by lowering both upfront installation expenses and long-term maintenance burdens.
At the same time, the cost structure of graphene materials and their integration into heating films, mats, and cables continues to mature. As production processes stabilize and demand scales, economies of scale are expected to improve margin profiles for manufacturers that can maintain quality control while expanding volume. Suppliers that invest in capacity, certification, and application-specific product variants are better positioned to capture value as the market transitions from early adoption to broader commercial penetration.
Competitive Landscape and Leading Strategies
The competitive landscape is characterized by a mix of specialized graphene technology firms, established heating manufacturers, and regional players with strong distribution networks. The market's low concentration ratios indicate that no single entity currently dominates, creating opportunities for companies that can combine technological differentiation with scalable commercial execution.
Strategic Positioning of Key Players
Haydale Graphene Industries, based in Ammanford, United Kingdom, has positioned itself at the intersection of material science and applied heating systems. Its Just Heat functionalised graphene underfloor heating system leverages patented HDPlas® technology to deliver low-voltage, energy-efficient electric floor heating with rapid response and even heat distribution. The company's recent activities reflect a deliberate progression from technical validation to commercial scaling. The release of a scientific and economic case white paper in March 2025, combined with a completed real-world deployment demonstrating 50 percent energy savings versus a gas boiler, strengthens its credibility with procurement teams and partners. The subsequent UL certification and a distribution agreement with Interfloor for an integrated flooring range, with commercial launch targeted for the first half of 2026, signal a shift toward channel-driven growth and broader market access.
In China, several manufacturers have established strong positions in graphene heating films and underfloor heating solutions. Clean Concept Technology Limited (CCT), operating from Shanghai and Jiangsu, manufactures and exports graphene floor heating films and underfloor heating solutions, including waterproof PE/PVC-encapsulated mats suitable for dry and wet environments. Its portfolio of certifications, including ISO9001, ISO14001, ISO45001, CE, RoHS, and TUV, supports its export-oriented strategy and reinforces trust in regulated markets. Wuxi BENELLI New Material Co., Ltd. supplies graphene electric heating floor systems that utilize advanced graphene materials for uniform, energy-efficient radiant heating suitable for various flooring types, emphasizing compatibility and versatility. Nuanjia Graphene Carbon New Energy (Qingdao) Co., Ltd. is one of the early entrants in clean energy heating in China and has played a role in setting graphene and electric heat film standards, giving it a foundational position in shaping industry norms. 2D Carbon (Changzhou) Tech Inc., Ltd. develops and supplies graphene underfloor heating films and systems with a focus on even heat distribution and energy efficiency, complemented by established graphene transparent conductive film production capabilities that may support broader material applications. Levson Tech (Levson Green Heating) offers graphene electric underfloor heating modules with rapid uniform heating, IPX7 waterproofing, and far-infrared radiation, holding certifications including UL, RoHS, CE, and TUV, and claims a role as a graphene floor heating industry standard setter in China. Shengxihong (Shengxihong Heat Tech) specializes in graphene heating film products and systems emphasizing energy efficiency and even heat distribution, rounding out a competitive field where product reliability and certification portfolios are central to winning bids.
ALIKO CO., LTD., based in South Korea, produces and exports graphene PTC carbon floor heating films for infrared radiant electric underfloor heating systems, highlighting the regional diversity of innovation and the importance of geographic reach in serving localized demand.
Differentiation and Competitive Advantages
Across this landscape, differentiation is emerging along several axes. Technology-led players emphasize patented material functionalization, low-voltage operation, and documented energy savings, targeting customers who prioritize performance verification and long-term operating cost reduction. Manufacturers with strong certification portfolios and waterproof or versatile product designs are better positioned for commercial and multi-environment applications where durability and compliance are non-negotiable. Early entrants that have contributed to standard-setting activities gain influence over product specifications and testing expectations, which can create barriers for later entrants and strengthen customer confidence.
Channel strategy is also becoming a critical differentiator. Partnerships with flooring integrators, distribution agreements, and integrated product ranges can accelerate adoption by reducing the friction of specifying and installing graphene heating as part of a broader building solution. Companies that align their products with existing construction and renovation workflows are likely to gain share more rapidly than those requiring entirely new installation paradigms.
Market Structure Evolution
The market is expected to evolve through a combination of consolidation, specialization, and new entry. As the technology matures, larger heating or building materials companies may seek to acquire or partner with specialized graphene heating firms to add efficient electric heating capabilities to their portfolios. Simultaneously, regional players with strong local certifications, distribution networks, and cost advantages will continue to compete effectively in their home markets and export channels. New entrants may find opportunities in adjacent applications, advanced control integration, or hybrid systems that combine graphene heating with smart building management platforms. The balance between consolidation and fragmentation will depend on how quickly standards harmonize, how rapidly demand scales in commercial and industrial segments, and whether material supply chains stabilize at scale.
PW Consulting
Future Trends and Commercial Implications
Looking ahead to the next three to five years, several trends are likely to shape the trajectory of the graphene electric floor heating market and define where commercial value is captured.
First, the transition from residential-led growth to broader commercial and light industrial adoption will accelerate as verified performance data accumulates and certification coverage expands. Projects that can demonstrate measurable energy savings, such as the 50 percent reduction observed in the Eden House deployment, will serve as reference points for procurement teams evaluating heating retrofits and new builds. Commercial opportunities will emerge for solution providers that can bundle graphene heating with energy management controls, flooring integration, and performance guarantees, reducing the perceived risk of adoption.
Second, standardization and certification harmonization will become a competitive battleground. As more manufacturers achieve UL, CE, TUV, and other certifications, buyers will increasingly compare not just compliance but the depth and relevance of testing to their specific applications. Companies that invest in application-specific validation and transparent performance reporting will be better positioned to win in regulated sectors and cross-border markets. This trend also creates an opportunity for industry associations and standards bodies to define consistent testing protocols, which could reduce procurement friction and accelerate mainstream adoption.
Third, integration with smart building ecosystems and modular retrofit designs will expand the addressable market. Modular graphene electric underfloor heating designs that enable easy installation without significant floor height loss align with the growing demand for renovation-friendly solutions. When combined with intelligent controls that optimize heating schedules, zone temperatures, and energy usage, graphene systems can deliver compound value through both efficiency and convenience. Manufacturers and partners that develop integrated offerings spanning heating, controls, and flooring will capture more of the project value chain.
Potential risks and uncertainties remain. Material cost volatility, scaling challenges in graphene dispersion and film production, and the pace of regulatory alignment could affect margin profiles and deployment timelines. In addition, competition from alternative low-carbon heating technologies, including heat pumps and other electric heating formats, will require graphene heating to continually demonstrate its comparative advantages in comfort, installation ease, and energy efficiency. Market participants should monitor these dynamics closely, as the relative attractiveness of graphene heating will depend on how it performs against alternatives in real-world cost, reliability, and user experience terms.
Graphene Chip Market
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to strengthen the link between material innovation and commercial execution. Investing in consistent production quality, expanding certification coverage, and developing application-specific product variants can differentiate offerings in a fragmented market. Partnerships with flooring integrators, distributors, and control system providers can accelerate adoption by embedding graphene heating into familiar procurement and installation pathways. Companies that can document real-world energy savings and reliability across diverse environments will be best positioned to move from early adoption to broader market penetration.
For investors, the market presents opportunities in companies with clear technological differentiation, credible certification portfolios, and demonstrated deployment evidence. Due diligence should focus on manufacturing scalability, material supply stability, and the ability to transition from pilot projects to repeatable commercial sales. Exposure to players that are building integrated product ranges or securing distribution agreements may offer stronger commercial momentum than those relying solely on standalone product sales. Monitoring standardization developments and regional policy incentives will also help identify where demand is likely to accelerate.
For procurement and facility decision-makers, the emphasis should be on evaluating total cost of ownership rather than upfront price alone. Requesting verified performance data, checking certification relevance to the intended application, and piloting installations in controlled settings can reduce adoption risk. Engaging with suppliers that offer modular, retrofit-friendly designs and clear integration pathways with existing electrical and flooring systems can lower installation complexity and labor costs. As the market matures, early engagement with vendors that provide transparent documentation and performance guarantees will support more confident investment decisions.
For stakeholders seeking deeper segmentation data, regional breakdowns, and customized strategic guidance, the full research report provides detailed figures and scenario analysis to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Graphene Electric Floor Heating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com