

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Why Stainless Steel Vacuum Flasks Grow at 5.24% CAGR: Market Drivers Exposed

Global Stainless Steel Vacuum Flask Market: Strategic Trends and Commercial Opportunities (2025–2032)
The worldwide market for stainless steel vacuum flasks has entered a phase of steady consolidation, with total revenue projected to reach approximately 5.6 billion USD in 2025. Over the historical window from 2020 through 2025, the sector expanded from roughly 4.35 billion USD to its current baseline, reflecting consistent demand across consumer, corporate, and outdoor segments. Looking ahead to the forecast period spanning 2026 through 2032, the market is expected to progress toward 8.04 billion USD by the end of the decade, translating to a compound annual growth rate of approximately 5.24 percent. This trajectory signals a maturing but still expanding category where volume growth increasingly intersects with premiumization, regulatory scrutiny, and supply chain recalibration. For executives and investors, the near-term opportunity lies not in chasing undifferentiated volume, but in aligning product architecture, distribution strategy, and risk management with the structural shifts reshaping end markets. The data points to a market where scale advantages remain valuable, yet differentiation in materials, safety compliance, and channel mix increasingly determines margin resilience.
Despite the constructive growth outlook, the industry faces a set of compounding challenges that will test operational agility. First, commodity volatility has placed sustained pressure on cost structures. Stainless steel and nickel price movements over the past year have compressed margins for producers who lack flexible procurement models or the ability to pass through costs without eroding volume. Second, consumer safety expectations and regulatory oversight are tightening, as evidenced by high-profile product recalls that underscore the operational and reputational risks embedded in mass-market insulated drinkware. Third, the competitive field remains highly fragmented at the top but concentrated enough in aggregate that pricing power is unevenly distributed. With the top three players accounting for roughly 18.45 percent of market revenue and the top five reaching approximately 26.32 percent, no single entity dominates the category outright. This fragmentation creates both opportunity for strategic consolidation and risk for brands that cannot sustain clear differentiation. Collectively, these dynamics mark a turning point where efficiency, compliance, and brand positioning must advance together rather than in isolation.
Key Drivers Shaping the Market Trajectory
Technological Innovation and Material Longevity
Innovation in insulation architecture, surface engineering, and assembly precision continues to redefine what consumers expect from a vacuum flask. Manufacturers are progressively integrating 304 and 316 stainless steel formulations, double-wall vacuum sealing refinements, and latch or lid mechanisms designed to improve durability under repeated use. These advances are not merely aesthetic; they directly affect heat retention, condensation control, and product lifecycle, which in turn influence repeat purchase behavior and brand loyalty. The recent showcase of updated 2025/26 collections featuring advanced insulation profiles and custom ODM/OEM configurations at major industry exhibitions highlights how producers are converting technical capability into commercial flexibility. For downstream brands, this means access to increasingly modular component sets that can be tailored for specific use cases, from desk-side hydration to expedition-grade applications. The strategic implication is clear: firms that treat material science and engineering as a core differentiator rather than a commodity input are better positioned to command price premiums and reduce sensitivity to raw material swings.
Policy, Safety Standards, and Regulatory Expectations
Regulatory attention around durable consumer goods is intensifying, particularly where product failure can result in injury. Recent recall actions involving food jars and beverage bottles due to impact and laceration hazards demonstrate how quickly compliance gaps can translate into financial exposure and reputational damage. In response, manufacturers and brand owners are re-evaluating quality assurance protocols, component sourcing, and post-market monitoring. This environment favors organizations that embed safety and traceability into the design and production cycle from the outset, rather than treating them as downstream checks. For market entrants and established players alike, the regulatory trajectory suggests that documentation, testing rigor, and transparent communication will become table stakes for sustained access to retail and e-commerce channels, especially in higher-scrutiny destinations. Companies that proactively align with evolving standards can convert compliance into a competitive moat, while those that rely on reactive corrections face mounting operational and brand risk.
Stainless Steel Bottle Market
Demand-Side Shifts and Consumption Patterns
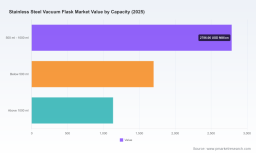
Consumer behavior is shifting toward products that combine everyday utility with longer service life and lower environmental footprint. Hydration routines are increasingly integrated into work, travel, fitness, and outdoor lifestyles, and stainless steel vacuum flasks benefit from a perception of durability that aligns with broader sustainability preferences. This demand environment supports growth across multiple capacity ranges, with mid-to-large formats capturing meaningful usage in professional and family settings, smaller volumes sustaining portability-driven segments, and oversized options serving specialized outdoor and group-use contexts. Distribution dynamics reinforce this pattern: online retail channels have emerged as a dominant route to market, while supermarkets and hypermarkets continue to provide broad reach, and specialty stores contribute through curated, premium positioning. The result is a demand landscape where product design, channel strategy, and brand storytelling must operate in concert. Brands that understand how different consumer cohorts evaluate performance, aesthetics, and trust are better equipped to allocate marketing spend and inventory toward the highest-return combinations.
Stainless Steel Vacuum Bottle Market
Supply Chain, Sourcing, and Cost Structure Evolution
Trade flows and manufacturing geography remain central to the market’s cost and risk equation. A substantial share of vacuum flasks and related components continues to originate from a concentrated set of exporting economies, with China supplying the overwhelming majority of imports into key destination markets such as the United States. This concentration offers scale and speed but also exposes buyers and producers to logistics disruption, tariff uncertainty, and input price variability. At the same time, elevated stainless steel prices over the past year have challenged cost structures, prompting manufacturers to explore dual sourcing, negotiated contract terms, and design-for-cost adjustments without sacrificing insulation performance. The strategic response among leading producers has been to balance high-volume OEM/ODM capabilities with selective premium lines that can absorb cost pressures more effectively. For procurement leaders and brand owners, this environment rewards supply chain visibility, scenario planning, and relationships with manufacturers that can scale across both commodity and specialty requirements.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive field spans globally recognized brands, technology-oriented premium manufacturers, and large-scale OEM/ODM suppliers operating across multiple regions. Thermos maintains a strong presence through broad portfolio coverage and a heritage in vacuum insulation technology, serving consumer and outdoor segments with recognizable brand equity. Tiger Corporation and Zojirushi represent the premium Japanese end of the market, emphasizing high-performance retention, refined design, and durable construction that appeals to discerning buyers willing to pay for reliability. In the United States, Hydro Flask, Klean Kanteen, and YETI have carved out distinct positions: Hydro Flask leans into active-lifestyle aesthetics and powder-coated finishes; Klean Kanteen emphasizes recyclable stainless steel and eco-conscious positioning; and YETI targets the premium outdoor segment with rugged construction and strong brand cachet. On the manufacturing side, Zhejiang Haers and Guangdong Sibao reflect the scale and heritage of Chinese production, with Haers serving a broad base of global brands through high-volume insulated drinkware and Sibao drawing on early leadership in vacuum insulated and magnetization cup technologies. Shanghai Tiger Electronics, operating under Japanese investment, extends quality-focused production for domestic and export markets, while Turkish producer Steel Termos serves regional and cross-regional demand with an emphasis on OEM production for Turkey, the Middle East, Europe, and Latin America. Mountop Bottle and LAIKOE further illustrate the breadth of specialized manufacturing capabilities, with Mountop oriented toward premium ODM/OEM bottles for global distributors and LAIKoe focusing on 18/8 food-grade stainless steel for thermos-style flasks and bottles.
The strategic positioning of these players reveals a market where leadership is increasingly defined by the ability to balance scale, quality, and brand narrative. Premium manufacturers differentiate through insulation performance, finish quality, and design credibility, while high-volume producers compete on cost efficiency, customization capacity, and reliability across large orders. This dual structure creates a spectrum of opportunities: brands that want shelf impact and premium pricing tend to partner with or emulate the design-led, performance-focused segment, while retailers and distributors that prioritize breadth and margin stability often rely on manufacturers with robust OEM/ODM infrastructure. Recent market events have reinforced the importance of operational discipline. High-profile recall actions have drawn attention to the need for rigorous quality control, component validation, and post-sale responsiveness, particularly for products sold at scale in consumer channels. At the same time, the continued presentation of advanced 304/316 stainless steel insulation and custom design options at major trade exhibitions signals that manufacturing capabilities are becoming more adaptable, allowing brand owners to move faster on limited editions, regional variations, and co-developed specifications. The competitive trend points toward selective consolidation among manufacturers seeking broader geographic reach and greater customization capability, alongside continued fragmentation at the brand level as new entrants test niche positioning in outdoor, wellness, and sustainable consumption segments.
Future Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by three interrelated trends. First, premiumization will continue to gain share, but in a more disciplined form. Consumers are willing to pay for better retention, better finishes, and better durability, yet they are also more alert to product safety and brand credibility. This suggests that premium strategies will need to be supported by verifiable quality claims, consistent manufacturing standards, and transparent communication rather than marketing alone. The commercial opportunity lies in creating tiered portfolios that preserve accessible entry points while building higher-margin lines anchored in performance and design. Second, channel convergence will accelerate. Online retail will keep expanding its role in discovery and repeat purchase, but physical retail and specialty outlets will remain important for touch-and-feel evaluation and brand positioning. Companies that integrate inventory, merchandising, and customer data across channels will be better positioned to manage demand volatility and optimize promotion timing. Third, supply chain resilience will move from a cost center to a strategic asset. With concentrated sourcing in key exporting regions and persistent input cost pressure, firms that diversify supplier bases, lock in flexible contracts, and use design to moderate material intensity will enjoy more stable margins and faster response times. The associated risk is that any disruption in logistics, trade policy, or raw material availability can quickly ripple through pricing and fulfillment, especially for brands heavily reliant on a single sourcing corridor. Mitigation will therefore depend on scenario planning, safety stock discipline, and explicit coordination between product, procurement, and sales functions.
Strategic Recommendations for Decision Makers
For manufacturers and brand owners, the priority is to embed quality and differentiation into the product architecture before scale becomes the sole focus. This means investing in insulation consistency, lid and latch reliability, and finish durability, while building a tiered offering that can address both volume-driven and premium-oriented demand. Firms should also treat safety and compliance as core capabilities, with documentation, testing, and post-market monitoring aligned to the expectations of the most stringent retail environments. For investors, the attractive opportunities are likely to be found in companies that combine defensible brand equity with flexible manufacturing partnerships and a clear route-to-market strategy. Due diligence should weigh channel mix, margin resilience under input cost pressure, and the ability to scale custom programs without compromising quality. For procurement and distribution leaders, the goal is to reduce concentration risk while preserving access to innovation. That entails diversifying supplier relationships across regions and capacity types, clarifying service-level expectations, and partnering with manufacturers that can support both standard replenishment and specialized co-development. Across all roles, timely access to granular market, segment, and competitive data can sharpen prioritization and reduce blind spots. For decision makers seeking deeper segmentation detail, region-specific dynamics, and customized scenario analysis, the full PW Consulting research report provides a more comprehensive view of the market’s structure, competitive moves, and forward-looking opportunities.
For detailed analysis of this topic, please visit the official page: Worldwide Stainless Steel Vacuum Flask Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com