

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Absorption Heat Pumps Market: Why Waste Heat Recovery Drives 5.62% CAGR

The Worldwide Absorption Heat Pumps Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global absorption heat pump market has demonstrated steady expansion over the past half-decade, moving from approximately 1.48 billion USD in 2020 to roughly 1.94 billion USD in 2025. The trajectory reflects a compound annual growth rate of about 5.6 percent through the 2026–2032 forecast horizon, with revenues projected to approach 2.85 billion USD by the end of the period. This growth is not uniform across time or geography; the market experienced a brief contraction in 2022 alongside broader industrial supply chain disruptions, followed by a rebound that accelerated into 2024 and 2025 as energy costs and decarbonization mandates reshaped procurement priorities. By 2032, the market is expected to cross the 2.8 billion USD threshold, signaling a structural shift rather than a cyclical upturn. The concentration of revenue among the top three players sits near 48 percent, while the top five collectively account for just over 62 percent, indicating a moderately consolidated landscape with room for specialized entrants and regional champions.
Despite the positive trajectory, the industry faces structural friction that will define competitive outcomes over the next several years. The first challenge is the uneven maturity of working fluid architectures. Water-lithium bromide systems dominate installed capacity because of their reliability and commercial availability, yet ammonia-water configurations offer distinct thermodynamic advantages for certain industrial and large-scale applications. The cost, handling requirements, and regulatory perception of these fluids create a bifurcated market where manufacturers must choose between standardization and performance differentiation. This split complicates scaling, because a platform optimized for one chemistry rarely translates seamlessly to the other without reworked components, certification, or service networks.
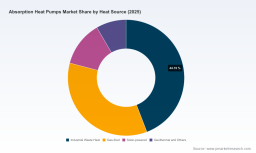
A second challenge is the dependency on heat source availability and infrastructure readiness. Absorption heat pumps are thermally driven, which means their economics hinge on access to waste heat, gas-fired inputs, solar thermal, or geothermal energy in forms that are predictable and cost-effective. Facilities with abundant industrial waste heat see rapid payback, but sites without such access must rely on fuel-based or solar-driven configurations, which introduce different cost profiles and operational assumptions. The mismatch between equipment capability and site conditions can stall projects even when efficiency targets are ambitious, turning what appears to be a straightforward retrofit into a feasibility exercise.
The third challenge is regulatory and incentive fragmentation. Energy efficiency programs, building codes, and tax provisions increasingly favor high-efficiency thermally driven systems and waste heat recovery, but the specifics vary by jurisdiction, project type, and compliance timeline. In some regions, updated HVAC efficiency requirements are reshaping which systems can be specified in new construction or major renovations, while in others, federal and state incentives create uneven adoption curves. This patchwork raises the cost of market entry and rewards players who can navigate local codes, documentation, and incentive structures with precision. The recent suspension of operations by a North American gas absorption heat pump manufacturer, while it explores strategic alternatives and asset sale options, illustrates how operational scale, partner ecosystems, and regional demand patterns can converge to create inflection points.
Key Drivers Behind Market Momentum
Technology innovation is reshaping the value proposition of absorption heat pumps by pushing efficiency boundaries and widening the range of usable heat sources. Multi-effect and high-efficiency absorption cycles are reducing primary energy consumption in applications where waste heat or gas-fired input is available, allowing operators to convert otherwise lost thermal energy into useful heating or cooling. Advances in heat exchanger design, control logic, and component durability are also improving part-load performance and reducing maintenance intensity, which matters increasingly for commercial and industrial operators who evaluate total cost of ownership rather than first cost alone. As manufacturers accumulate patent portfolios and field data across hundreds of installations, the credibility gap between absorption systems and conventional electric alternatives continues to narrow in niche applications where thermal integration is achievable.
Policy and regulatory momentum is another powerful driver. In markets that are tightening HVAC efficiency requirements or incentivizing decarbonized thermal systems, absorption heat pumps benefit from their ability to leverage waste heat, reduce electrical load, and lower direct emissions in specific configurations. Updated building codes that raise equipment efficiency thresholds can either create compliance pathways for thermally driven systems or raise the bar for integration and controls. Similarly, tax credits and efficiency programs that reward high-performance heat pump adoption provide a financial tailwind for projects that can demonstrate measurable energy savings. The strategic implication is that policy is not merely a background condition; it is becoming a design parameter. Manufacturers and project developers that align product roadmaps with evolving code cycles and incentive eligibility are better positioned to secure specification wins and shorten sales cycles.
Geothermal Heat Pump Market
Demand-side behavior is changing as well. Industrial operators are increasingly treating waste heat recovery as a strategic resource rather than a byproduct, especially where energy intensity and fuel volatility are persistent concerns. Commercial and residential segments are also showing greater interest in thermally driven options where gas availability, grid constraints, or decarbonization goals make electric compression systems less attractive in specific contexts. This demand evolution is shifting procurement discussions from narrow equipment comparisons to system-level outcomes: how much waste heat can be absorbed, how the system interacts with existing infrastructure, and how the operating profile aligns with long-term energy planning. The result is a more consultative buying process that rewards suppliers capable of engineering around site-specific heat sources and load profiles.
Supply chain and cost structure dynamics reinforce these shifts. The availability and pricing of key materials such as lithium bromide influence system economics, particularly for water-lithium bromide platforms that represent the larger share of installed capacity. At the same time, gas-fired and thermally driven configurations can become more attractive when electricity pricing is volatile or when waste heat is abundant enough to offset fuel input. Suppliers that can stabilize component sourcing, localize assembly where incentives favor it, and offer flexible drive configurations gain an advantage in projects where lead times and cost predictability are critical. The broader effect is a market in which cost leadership is increasingly tied to integration capability, material strategy, and the ability to match drive sources to local energy realities.
Competitive Landscape and Leading Strategies
The competitive field combines large global manufacturers with specialized leaders that have built deep expertise in particular working fluids, capacities, or end-use segments. Shuangliang Eco-Energy has established a strong position in industrial lithium bromide absorption heat pumps, accumulating a broad international installation base and a substantial patent portfolio focused on high-efficiency waste heat recovery and significant energy savings. Its strategy emphasizes long-cycle industrial deployments where proven performance and energy reduction claims are central to procurement decisions. Johnson Controls, through its YORK portfolio, offers a wide range of absorption chillers and heat pumps that can be driven by multiple heat sources, targeting commercial and industrial applications where waste heat utilization, water savings, and emissions reduction are priorities. Its long operating history gives it visibility across a broad set of building and facility types, which supports specification relationships and service continuity.
BROAD Group has scaled rapidly as one of the largest manufacturers of absorption chillers and heat pumps, with a product range that spans smaller commercial units to large industrial capacities and a strong focus on gas-fired and thermally driven systems. Its extensive global deployment base reflects an aggressive push into commercial, civil, and industrial markets, supported by volume manufacturing and a broad application footprint. Thermax Limited has carved out a position around advanced absorption chillers and triple-effect technology, emphasizing high-efficiency, multi-energy-driven systems for industrial use and exporting its capabilities across global markets. Robur S.p.A. distinguishes itself through gas absorption and ammonia-based heat pump and chiller solutions, with models designed to deliver high effective efficiency and a reduced carbon footprint in commercial and residential settings. Hope Deepblue, Ebara, and Berg Chilling Systems, including its partnership with World Energy, round out a field that spans lithium bromide systems, waste heat recovery pumps, and marine or exhaust-gas-driven configurations, each targeting specific performance, durability, or application requirements.
The strategic differentiation among these players is becoming clearer. Some compete primarily on proven industrial scale, patent depth, and waste heat recovery performance; others compete on portfolio breadth, multi-source drive capability, and brand recognition across commercial buildings; still others compete on specialized chemistries such as ammonia or on niche application engineering such as marine and offshore environments. The most resilient players are those that can translate technical differentiation into measurable operating outcomes and then support those claims with service, documentation, and local compliance knowledge. Price competition exists, but in many project categories the decisive factors are integration risk, heat source compatibility, and the ability to satisfy efficiency and code requirements without excessive customization.
The market structure is evolving along two converging paths. On one hand, consolidation pressure is rising among suppliers that need broader geographic coverage, service networks, and application libraries to win larger industrial and infrastructure projects. On the other hand, segmentation is deepening because working fluid choices, heat source types, and end-user requirements reward focused expertise. New entrants or asset-level moves, such as the recent North American situation involving a gas absorption heat pump manufacturer exploring a partner or asset sale, suggest that regional manufacturing footprints and brand continuity can become strategic assets in themselves. The likely outcome is a landscape where a handful of global platforms coexist with specialized leaders and regional capabilities, and where partnerships, distribution agreements, and selective acquisitions become common tools for expanding reach without abandoning technical focus.
Outlook for the Next Three to Five Years
Looking ahead, one defining trend will be the wider use of absorption heat pumps as part of integrated thermal hubs rather than standalone equipment purchases. Industrial facilities and large commercial campuses are increasingly viewed as systems where waste heat, cooling, heating, and sometimes solar or geothermal inputs can be coordinated. In that context, absorption heat pumps that can accept multiple drive sources and operate efficiently across variable loads will be favored, because they fit into broader energy orchestration strategies. The commercial opportunity lies in bundling equipment with feasibility assessment, control integration, and commissioning support, turning a hardware sale into a performance-based engagement with clearer payback certainty.
A second trend is the gradual expansion of ammonia-water and advanced multi-effect architectures in selected industrial and large-scale applications, alongside continued dominance of water-lithium bromide in mainstream commercial and many industrial settings. As operators seek higher effective efficiency or need to handle specific temperature and capacity ranges, the choice of working fluid will become more application-specific. This creates opportunities for suppliers that can offer certified, well-supported ammonia-based solutions where safety and handling requirements are manageable, as well as for manufacturers that continue to improve lithium bromide system efficiency and standardization. The uncertainty is that regulatory interpretation, operator familiarity, and service readiness will influence adoption speed, meaning that technical superiority alone will not guarantee market share without ecosystem support.
PW Consulting
A third trend is the widening but uneven impact of efficiency codes and incentives. As jurisdictions update HVAC requirements and extend fiscal support for high-efficiency heat pump applications, some regions will see faster project pipelines and stronger specification momentum, while others lag. This unevenness favors players who can localize documentation, support code compliance, and align product offerings with the incentive programs that matter locally. The main risk is that policy timing, program eligibility details, and equipment eligibility interpretations can shift, altering project economics after a pipeline has been planned. Companies that treat policy as a variable to monitor rather than a fixed assumption will be better able to sequence investments, adjust offerings, and protect margins.
Recommendations for Decision-Makers
For manufacturers, the strategic priority is to align product roadmaps with the most defensible demand pockets rather than chasing broad coverage. That means clarifying where waste heat recovery, gas-fired thermally driven systems, or solar/geothermal inputs provide a genuine economic edge, and then investing in the working fluid platforms, component supply stability, and application documentation that support those segments. Differentiation should be expressed in operating outcomes and integration ease, supported by service capacity and compliance knowledge that reduce project risk for buyers. Partnerships for regional distribution, asset continuity, or application-specific engineering can be more efficient than attempting to build every capability internally.
Air Source Heat Pumps Market
For investors, the opportunity is strongest where installed base, patent depth, and regional demand alignment converge, especially in industrial lithium bromide platforms, large-scale gas-fired systems, and specialized ammonia or multi-effect offerings that serve high-value niches. Due diligence should focus on heat source dependency risk, incentive exposure, material cost sensitivity, and the resilience of service and distribution networks, because those factors determine whether growth is sustainable through code cycles and energy price swings. Company-level transitions, such as asset reshuffling or relaunch efforts in specific regions, can create both risk and entry points, so valuation should weigh ecosystem continuity as heavily as technical claims.
For procurement and facility leaders, the priority is to evaluate absorption heat pump options on system-level economics rather than equipment-level specifications. Projects should be screened for heat source availability, compatibility with existing infrastructure, control integration needs, and eligibility for relevant efficiency incentives, with attention to the code cycles that affect new construction or major renovation. Where thermal integration is strong, absorption systems can deliver meaningful operational benefits; where heat source conditions are uncertain, the value proposition weakens quickly. In either case, engaging detailed market intelligence and segment-level data before committing to a technology path helps avoid overgeneralization and supports more accurate total cost of ownership comparisons across the options that matter for the project.
For detailed analysis of this topic, please visit the official page: Worldwide Absorption Heat Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com