

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Graphene Electric Floor Heating Market: 14.85% CAGR and $1.67B Trajectory

Strategic Trends and Commercial Opportunities in the Worldwide Graphene Electric Floor Heating Market
Market Overview and Core Challenges
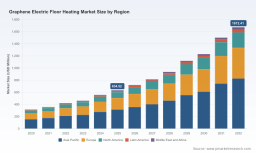
The worldwide graphene electric floor heating market has entered a phase of accelerated expansion, moving from a niche technological concept to a commercially viable heating solution. Valued at approximately USD 634.52 million in 2025, the market has demonstrated consistent growth since 2020, when revenues stood at 315.6 million. The trajectory suggests a compound annual growth rate of 14.85 percent through 2032, with projected revenues reaching 1,672.41 million by the end of the forecast period. This growth curve indicates that graphene-based heating is no longer merely an alternative but is becoming a significant component of the broader electric heating ecosystem.
The market structure reveals a fragmented landscape despite the rapid revenue expansion. Concentration ratios remain relatively low, with the top three players holding approximately 18.25 percent of the market and the top five capturing 27.6 percent. This fragmentation suggests that while leading innovators are carving out strong positions, significant room remains for consolidation or for new entrants to capture share through differentiated technology or regional focus. The revenue base is heavily weighted toward specific product forms and applications, indicating where commercial adoption is currently most mature.
Several critical challenges define the current industry inflection point. First, the translation of laboratory-grade graphene performance into consistent, scalable manufacturing remains a hurdle. While thermal efficiency claims are strong, maintaining uniform dispersion of graphene within heating films or mats across large production runs requires precise process control. Variability in material quality can impact heating consistency and product longevity, creating a barrier for widespread adoption in commercial and industrial settings where reliability is paramount.
Second, the market faces a certification and standardization gap. Although multiple manufacturers hold international certifications such as RoHS, REACH, CE, UL, and TUV, the absence of a single unified global standard for graphene heating performance can complicate cross-border trade and procurement decisions. Buyers in regulated sectors often require extensive verification, slowing deployment cycles. As the market scales, harmonized standards will likely become a competitive differentiator rather than just a compliance checkbox.
Underfloor Heating Market
Third, the integration of graphene heating into existing building infrastructure presents both an opportunity and a friction point. Modular designs that enable retrofitting without significant floor height loss are emerging, yet widespread adoption requires alignment with construction workflows, electrical system capacities, and installer training. The labor cost savings associated with simplified installation are compelling, but realizing these savings at scale depends on industry-wide familiarity with the technology and reliable supply chains for compatible flooring and control systems.
Key Drivers of Market Dynamics
The expansion of the graphene electric floor heating market is propelled by a convergence of technological breakthroughs, regulatory momentum, shifting demand patterns, and evolving supply chain economics. Each driver reinforces the others, creating a self-accelerating adoption cycle in specific regions and applications.
Technological Innovation and Performance Breakthroughs
Graphene materials have enabled far-infrared conversion rates reaching up to 76 percent in electric floor heating systems, supporting high thermal efficiency with power density around 16W/m²/h for building-area calculations. This efficiency profile translates into faster heat-up times, more even heat distribution, and the potential for energy savings of 50 to 70 percent compared to conventional systems in real-world trials. These performance characteristics are not merely technical specifications; they directly address the core value proposition that building owners and occupants care about: comfort, control, and operating cost reduction.
Recent commercial milestones illustrate how technology is crossing the valley from prototype to deployed reality. In December 2024, a real-world deployment at Eden House respite care home demonstrated 50 percent less energy consumption than a gas boiler, providing tangible evidence of operational savings in a setting where heating reliability and efficiency are critical. The scientific and economic case for this approach was formalized in a white paper released in March 2025, strengthening the narrative for procurement teams and investors evaluating the technology's maturity.
Product certification progress further signals commercial readiness. The launch of a graphene underfloor heating system with UL certification in April 2025 removed a significant barrier for market entry in regions where safety and performance validation is mandatory. By mid-2025, the manufacturer had secured UL certification, positioning the product for broader commercialization in North American and other regulated markets.
Policy and Regulatory Environment
Regulatory frameworks and sustainability mandates are reshaping heating procurement decisions globally. Graphene underfloor heating systems comply with international standards including RoHS, REACH, CE, UL, and TUV certifications, ensuring no electromagnetic radiation or harmful emissions. This compliance profile aligns with tightening building codes and indoor air quality requirements, making graphene heating an attractive option for projects that must meet stringent environmental and safety criteria.
The broader macro trend toward net-zero goals provides additional tailwinds. Graphene-based electric floor heating supports decarbonization objectives through faster heat-up times, even distribution, and potential energy savings that reduce overall electricity demand. In regions where electrification of heat is being prioritized over fossil fuel systems, the efficiency advantages of graphene heating strengthen the economic case for adoption. Policy incentives for energy-efficient renovations, low-carbon heating installations, and smart building integration are likely to amplify demand, particularly in markets where retrofit activity is accelerating.
Demand-Side Shifts in Consumer and Enterprise Behavior
Demand is being shaped by a dual dynamic: residential consumers seeking comfortable, energy-efficient heating solutions and commercial entities under pressure to reduce operating costs while meeting sustainability targets. The residential segment currently represents the largest application base, reflecting the technology's suitability for homes where even heat distribution and zone-level control deliver noticeable comfort improvements. However, the commercial segment is gaining momentum as facility managers evaluate heating upgrades that can deliver measurable energy savings and align with corporate ESG commitments.
The industrial segment, while smaller in current revenue terms, represents a strategic frontier. Applications requiring uniform radiant heat in controlled environments, such as drying processes or specialized manufacturing spaces, could benefit from graphene heating's efficiency and modularity. As operators in these sectors look to reduce energy intensity and improve process control, graphene-based solutions may find niche but high-value deployments.
Consumer and buyer behavior is also being influenced by the growing availability of verified performance data. The shift from theoretical efficiency claims to documented case studies, such as the Eden House deployment, reduces perceived risk for early adopters. As more real-world evidence accumulates, procurement cycles are likely to shorten, particularly in sectors where heating costs are a significant line item.
Supply Chain and Cost Structure Evolution
The supply chain for graphene electric floor heating is evolving from fragmented, region-specific production toward more integrated value chains that emphasize material consistency, certification readiness, and installation simplicity. Modular graphene electric underfloor heating designs enable easy DIY or retrofit installation without occupying floor height, reducing labor requirements for installation and maintenance. These design advantages directly impact total cost of ownership by lowering both upfront installation expenses and long-term maintenance burdens.
At the same time, the cost structure of graphene materials and their integration into heating films, mats, and cables continues to mature. As production processes stabilize and demand scales, economies of scale are expected to improve margin profiles for manufacturers that can maintain quality control while expanding volume. Suppliers that invest in capacity, certification, and application-specific product variants are better positioned to capture value as the market transitions from early adoption to broader commercial penetration.
Competitive Landscape and Leading Strategies
The competitive landscape is characterized by a mix of specialized graphene technology firms, established heating manufacturers, and regional players with strong distribution networks. The market's low concentration ratios indicate that no single entity currently dominates, creating opportunities for companies that can combine technological differentiation with scalable commercial execution.
Strategic Positioning of Key Players
Haydale Graphene Industries, based in Ammanford, United Kingdom, has positioned itself at the intersection of material science and applied heating systems. Its Just Heat functionalised graphene underfloor heating system leverages patented HDPlas® technology to deliver low-voltage, energy-efficient electric floor heating with rapid response and even heat distribution. The company's recent activities reflect a deliberate progression from technical validation to commercial scaling. The release of a scientific and economic case white paper in March 2025, combined with a completed real-world deployment demonstrating 50 percent energy savings versus a gas boiler, strengthens its credibility with procurement teams and partners. The subsequent UL certification and a distribution agreement with Interfloor for an integrated flooring range, with commercial launch targeted for the first half of 2026, signal a shift toward channel-driven growth and broader market access.
In China, several manufacturers have established strong positions in graphene heating films and underfloor heating solutions. Clean Concept Technology Limited (CCT), operating from Shanghai and Jiangsu, manufactures and exports graphene floor heating films and underfloor heating solutions, including waterproof PE/PVC-encapsulated mats suitable for dry and wet environments. Its portfolio of certifications, including ISO9001, ISO14001, ISO45001, CE, RoHS, and TUV, supports its export-oriented strategy and reinforces trust in regulated markets. Wuxi BENELLI New Material Co., Ltd. supplies graphene electric heating floor systems that utilize advanced graphene materials for uniform, energy-efficient radiant heating suitable for various flooring types, emphasizing compatibility and versatility. Nuanjia Graphene Carbon New Energy (Qingdao) Co., Ltd. is one of the early entrants in clean energy heating in China and has played a role in setting graphene and electric heat film standards, giving it a foundational position in shaping industry norms. 2D Carbon (Changzhou) Tech Inc., Ltd. develops and supplies graphene underfloor heating films and systems with a focus on even heat distribution and energy efficiency, complemented by established graphene transparent conductive film production capabilities that may support broader material applications. Levson Tech (Levson Green Heating) offers graphene electric underfloor heating modules with rapid uniform heating, IPX7 waterproofing, and far-infrared radiation, holding certifications including UL, RoHS, CE, and TUV, and claims a role as a graphene floor heating industry standard setter in China. Shengxihong (Shengxihong Heat Tech) specializes in graphene heating film products and systems emphasizing energy efficiency and even heat distribution, rounding out a competitive field where product reliability and certification portfolios are central to winning bids.
ALIKO CO., LTD., based in South Korea, produces and exports graphene PTC carbon floor heating films for infrared radiant electric underfloor heating systems, highlighting the regional diversity of innovation and the importance of geographic reach in serving localized demand.
Differentiation and Competitive Advantages
Across this landscape, differentiation is emerging along several axes. Technology-led players emphasize patented material functionalization, low-voltage operation, and documented energy savings, targeting customers who prioritize performance verification and long-term operating cost reduction. Manufacturers with strong certification portfolios and waterproof or versatile product designs are better positioned for commercial and multi-environment applications where durability and compliance are non-negotiable. Early entrants that have contributed to standard-setting activities gain influence over product specifications and testing expectations, which can create barriers for later entrants and strengthen customer confidence.
Channel strategy is also becoming a critical differentiator. Partnerships with flooring integrators, distribution agreements, and integrated product ranges can accelerate adoption by reducing the friction of specifying and installing graphene heating as part of a broader building solution. Companies that align their products with existing construction and renovation workflows are likely to gain share more rapidly than those requiring entirely new installation paradigms.
Market Structure Evolution
The market is expected to evolve through a combination of consolidation, specialization, and new entry. As the technology matures, larger heating or building materials companies may seek to acquire or partner with specialized graphene heating firms to add efficient electric heating capabilities to their portfolios. Simultaneously, regional players with strong local certifications, distribution networks, and cost advantages will continue to compete effectively in their home markets and export channels. New entrants may find opportunities in adjacent applications, advanced control integration, or hybrid systems that combine graphene heating with smart building management platforms. The balance between consolidation and fragmentation will depend on how quickly standards harmonize, how rapidly demand scales in commercial and industrial segments, and whether material supply chains stabilize at scale.
PW Consulting
Future Trends and Commercial Implications
Looking ahead to the next three to five years, several trends are likely to shape the trajectory of the graphene electric floor heating market and define where commercial value is captured.
First, the transition from residential-led growth to broader commercial and light industrial adoption will accelerate as verified performance data accumulates and certification coverage expands. Projects that can demonstrate measurable energy savings, such as the 50 percent reduction observed in the Eden House deployment, will serve as reference points for procurement teams evaluating heating retrofits and new builds. Commercial opportunities will emerge for solution providers that can bundle graphene heating with energy management controls, flooring integration, and performance guarantees, reducing the perceived risk of adoption.
Second, standardization and certification harmonization will become a competitive battleground. As more manufacturers achieve UL, CE, TUV, and other certifications, buyers will increasingly compare not just compliance but the depth and relevance of testing to their specific applications. Companies that invest in application-specific validation and transparent performance reporting will be better positioned to win in regulated sectors and cross-border markets. This trend also creates an opportunity for industry associations and standards bodies to define consistent testing protocols, which could reduce procurement friction and accelerate mainstream adoption.
Third, integration with smart building ecosystems and modular retrofit designs will expand the addressable market. Modular graphene electric underfloor heating designs that enable easy installation without significant floor height loss align with the growing demand for renovation-friendly solutions. When combined with intelligent controls that optimize heating schedules, zone temperatures, and energy usage, graphene systems can deliver compound value through both efficiency and convenience. Manufacturers and partners that develop integrated offerings spanning heating, controls, and flooring will capture more of the project value chain.
Potential risks and uncertainties remain. Material cost volatility, scaling challenges in graphene dispersion and film production, and the pace of regulatory alignment could affect margin profiles and deployment timelines. In addition, competition from alternative low-carbon heating technologies, including heat pumps and other electric heating formats, will require graphene heating to continually demonstrate its comparative advantages in comfort, installation ease, and energy efficiency. Market participants should monitor these dynamics closely, as the relative attractiveness of graphene heating will depend on how it performs against alternatives in real-world cost, reliability, and user experience terms.
Graphene Chip Market
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to strengthen the link between material innovation and commercial execution. Investing in consistent production quality, expanding certification coverage, and developing application-specific product variants can differentiate offerings in a fragmented market. Partnerships with flooring integrators, distributors, and control system providers can accelerate adoption by embedding graphene heating into familiar procurement and installation pathways. Companies that can document real-world energy savings and reliability across diverse environments will be best positioned to move from early adoption to broader market penetration.
For investors, the market presents opportunities in companies with clear technological differentiation, credible certification portfolios, and demonstrated deployment evidence. Due diligence should focus on manufacturing scalability, material supply stability, and the ability to transition from pilot projects to repeatable commercial sales. Exposure to players that are building integrated product ranges or securing distribution agreements may offer stronger commercial momentum than those relying solely on standalone product sales. Monitoring standardization developments and regional policy incentives will also help identify where demand is likely to accelerate.
For procurement and facility decision-makers, the emphasis should be on evaluating total cost of ownership rather than upfront price alone. Requesting verified performance data, checking certification relevance to the intended application, and piloting installations in controlled settings can reduce adoption risk. Engaging with suppliers that offer modular, retrofit-friendly designs and clear integration pathways with existing electrical and flooring systems can lower installation complexity and labor costs. As the market matures, early engagement with vendors that provide transparent documentation and performance guarantees will support more confident investment decisions.
For stakeholders seeking deeper segmentation data, regional breakdowns, and customized strategic guidance, the full research report provides detailed figures and scenario analysis to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Graphene Electric Floor Heating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com