

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Enalapril Market CAGR Insights: What the 2032 Growth Path Means

Strategic Trends and Commercial Opportunities in the Worldwide Enalapril Market
Market Overview and Core Challenges
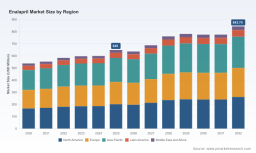
The global enalapril market has demonstrated steady expansion over the past half-decade, reflecting the persistent demand for effective cardiovascular therapeutics. From 2020 to 2025, the market evolved from a base of approximately 538 million USD to an estimated 649 million USD in the current year, indicating a compound annual growth rate of 3.82 percent through the forecast horizon extending to 2032. This trajectory suggests that while the molecule is well-established, the addressable market continues to expand alongside broader epidemiological shifts and healthcare accessibility improvements. The growth pattern, however, is not linear, with projected fluctuations in the late 2020s highlighting the sensitivity of revenue streams to regulatory approvals, generic erosion, and regional pricing pressures.
Despite this foundational stability, the industry is navigating several structural challenges that threaten to reshape competitive dynamics. First, the maturation of generic penetration has intensified price competition, compressing margins for formulators who lack differentiated supply chain capabilities or regulatory agility. With the market characterized by moderate concentration, where the top three firms capture roughly 38 percent of revenue and the top five account for over half, smaller players must rely on niche capabilities or regional partnerships to maintain relevance. Second, supply chain fragility remains a persistent risk, particularly given the heavy reliance on imported active pharmaceutical ingredients for cardiovascular therapies in major consumption markets. This dependency exposes manufacturers to geopolitical disruptions, regulatory audits, and cost volatility that can ripple through finished product pricing. Third, reimbursement scrutiny and formulary management in developed healthcare systems are increasingly favoring cost-optimized procurement, forcing suppliers to demonstrate value beyond molecule efficacy alone. These intersecting pressures create a pivotal moment where operational efficiency, regulatory foresight, and market access strategy determine long-term positioning.
Key Drivers of Market Evolution
Technological and manufacturing innovation continues to influence how enalapril is produced, formulated, and delivered. Advances in process chemistry and continuous manufacturing principles have enabled more consistent API quality and reduced batch variability, which is especially relevant for narrowly therapeutic molecules where impurities or potency drift can trigger regulatory action. A practical illustration of shifting formulation priorities emerged in early 2024, when a major generic manufacturer received FDA clearance for an enalapril maleate oral solution. This approval expanded the available dosage forms beyond conventional tablets, addressing patient populations with swallowing difficulties or pediatric needs and signaling that incremental formulation innovation remains a viable pathway to differentiation even in a mature generic landscape.
Regulatory and policy frameworks are simultaneously reshaping market access and competitive entry. The authorization landscape has shown renewed openness to specialized indications, as evidenced by a 2023 European Medicines Agency decision clearing a pediatric heart failure indication for an enalapril-based product. Such regulatory milestones matter because they extend the clinical utility of the molecule into underserved patient groups, create labeling distinctions that can support market segmentation, and encourage manufacturers to invest in targeted clinical or regulatory submissions rather than competing solely on bulk generic volume. At the same time, regulatory scrutiny on supply chain integrity continues to tighten, reinforcing the importance of documented quality systems and traceability for both API producers and finished dosage manufacturers.
Demand-side behavior is shifting as healthcare systems and patients navigate long-term cardiovascular management. Hypertension and heart failure remain dominant indications for enalapril, supported by its established clinical profile and broad generic availability. Yet the demand narrative is increasingly shaped by adherence considerations, chronic care management programs, and the preference for therapies that integrate smoothly into multiprescriber regimens. In this environment, products that offer reliable supply, consistent bioequivalence performance, and supportive packaging or delivery formats can gain outsized attention from procurement teams and clinical stakeholders who prioritize continuity of care over marginal unit-cost differences.
Cost structure dynamics, particularly around API procurement, add another layer of complexity. Reported pricing disparities across sourcing regions underscore how regulatory compliance requirements, local demand from formulation manufacturers, and regional production costs influence input economics. These variations create opportunities for companies that can secure stable, compliant supply at competitive terms, while also elevating the risk for players dependent on single-source procurement or exposed to currency and logistics volatility.
- Process and formulation innovation can unlock incremental value even after patent expiry, particularly when it addresses adherence or population-specific needs.
- Regulatory approvals for new indications or dosage forms can create temporary differentiation windows and support targeted market access strategies.
- Demand patterns are increasingly influenced by adherence, chronic care integration, and procurement priorities that weigh supply reliability alongside price.
- API cost dispersion across regions encourages diversified sourcing strategies and emphasizes the value of compliant, audit-ready suppliers.
Competitive Landscape and Leading Strategies
The competitive field is defined by a mix of large multinational generic suppliers and specialized API manufacturers concentrated in India, China, Europe, and the United States. This geographic spread reflects both historical manufacturing strengths and the way regulatory pathways shape market entry. Companies with integrated API and formulation capabilities tend to hold an advantage in managing cost, quality, and lead times, while API-focused producers often compete on regulatory filings, export reach, and customization for formulation partners. The presence of multiple suppliers for finished dosage forms indicates a mature competitive environment where scale, regulatory track record, and distribution relationships are central to sustaining share.
Strategic positioning among leading players often hinges on regulatory asset accumulation and market-specific execution. A notable example occurred in mid-2025, when one company expanded its U.S. market footprint by acquiring an FDA-approved abbreviated new drug application for enalapril maleate tablets in multiple strengths from another established manufacturer. Transactions of this type illustrate how regulatory assets can serve as strategic currency, enabling faster commercial entry, portfolio expansion, or geographic rebalancing without the lead time of de novo filings. In parallel, the broader pattern of multiple firms maintaining broad generic tablet portfolios across strengths suggests that competitive advantage increasingly depends on operational reliability, supply continuity, and the ability to serve procurement programs that value predictability.
Epinephrine Market
The market structure appears to be moving through a phase where consolidation and selective diversification coexist. On one hand, acquisition of approved applications and partnerships between API producers and formulators can consolidate capability among players seeking to reduce dependency on external suppliers. On the other hand, specialized entrants continue to find openings in narrower segments, such as alternative formulations or indication-specific supply arrangements. This duality means that incumbents must defend share through cost discipline and quality assurance, while new and expanding participants can pursue differentiated routes tied to regulatory assets, formulation variants, or regional supply agreements.
Several strategic themes recur among stronger performers. First, maintaining a diversified regulatory footprint reduces exposure to single-market pricing pressure and creates options for portfolio optimization. Second, investing in supply chain resilience, including multi-source API strategies and audit-ready quality systems, supports both commercial continuity and customer confidence. Third, building capability around non-tablet formats or specialized indications can create pockets of differentiation in an otherwise crowded field. The interplay of these approaches suggests that long-term success will depend less on molecule novelty and more on execution excellence across regulation, manufacturing, and market access.
- Leading players combine regulatory asset strength with formulation breadth to sustain presence across multiple markets and dosage strengths.
- Acquisition of approved applications and partnership-based supply models are becoming common mechanisms for accelerating market entry and rebalancing portfolios.
- Competitive differentiation is shifting toward supply reliability, quality documentation, and targeted formulation or indication strategies rather than volume alone.
- The coexistence of consolidation activity and niche expansion indicates a market where operational agility and regulatory readiness determine competitive outcomes.
Future Trends and Outlook
Over the next three to five years, the market is likely to be shaped by the interplay of sustained cardiovascular demand, continued generic competition, and incremental regulatory and formulation evolution. One key trend is the ongoing rationalization of supply chains toward greater resilience and documentation rigor. As procurement organizations in major markets place increasing weight on supply continuity and auditable quality, suppliers that can demonstrate robust sourcing, validated processes, and transparent compliance records will be better positioned to secure long-term contracts and withstand price competition. This trend creates commercial opportunities for manufacturers that invest early in supply chain diversification and regulatory readiness, especially where API sourcing is concentrated or vulnerable to external shocks.
A second trend concerns the gradual broadening of usage contexts through formulation and indication refinement. Even in a well-established generic category, approvals that address specific patient populations or delivery preferences can create meaningful commercial differentiation. Products aligned with pediatric, geriatric, or adherence-sensitive use cases may command more favorable positioning in certain procurement and clinical settings, particularly where healthcare providers seek to reduce administration barriers and support long-term therapy continuity. The opportunity here lies not in discovering new therapeutic territory, but in translating existing molecule utility into formats and labeling that better fit practical care delivery.
A third trend is the intensification of pricing discipline as more competitors compete in mature generic segments. With a wide field of suppliers, margin preservation will increasingly depend on operational efficiency, mix management, and value-added services such as reliable delivery, batch consistency, and responsive regulatory support. This environment favors organizations that can manage cost structures without sacrificing quality, and that understand the local procurement dynamics of each market they serve. At the same time, uncertainty remains around reimbursement pressure, regulatory enforcement intensity, and the potential for supply disruptions to alter short-term pricing and availability. Companies that treat these variables as manageable risks rather than external surprises will be better prepared to capture share when conditions shift.
Worldwide Enfuvirtide Market
- Supply chain resilience and documented quality will become more commercially relevant as procurement prioritizes continuity and compliance.
- Formulation and indication refinements offer realistic differentiation opportunities that support adherence and specific patient groups.
- Pricing pressure will reward operational efficiency and market-specific execution, while exposing firms that rely on single-channel volume strategies.
- Regulatory, reimbursement, and supply-side uncertainties will require scenario-aware planning rather than static forecasts.
Actionable Insights for Decision-Makers
For manufacturers, the priority is to strengthen the operational foundations that translate into commercial reliability. Diversifying API sourcing, reinforcing quality documentation, and investing in formulation flexibility can reduce exposure to input cost swings and regulatory interruptions while improving the ability to serve differentiated customer needs. Companies should also evaluate regulatory asset strategies, including the potential to acquire or partner around approved applications, as a means to accelerate entry or expand strength coverage in target markets.
PW Consulting
For investors, the market rewards disciplined exposure to participants with credible supply chains, broad regulatory footprints, and the ability to compete on reliability as much as price. Due diligence should focus on sourcing dependencies, approval pipelines for additional indications or formulations, and the extent to which a company’s portfolio mix supports margin stability in a competitive generic environment. Monitoring transaction activity around regulatory assets can also provide early signals about where capability is consolidating.
For procurement and market access teams, the emphasis should be on qualifying suppliers that can deliver consistent supply and auditable quality without sacrificing cost efficiency. Balancing multi-source strategies with long-term partnership structures can help mitigate disruption risk while preserving negotiating leverage. Where possible, aligning product selection with adherence-friendly formats and reliable delivery performance can support both clinical continuity and total cost-of-care objectives.
For stakeholders seeking a deeper view of regional revenue splits, formulation and indication dynamics, concentration metrics, and company-level strategic profiles, a more comprehensive research resource is available to support detailed planning and scenario modeling.
For detailed analysis of this topic, please visit the official page: Worldwide Enalapril Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com