

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Industrial Burden Carrier Market 2026: Why 4.95% CAGR Signals a $751M Shift

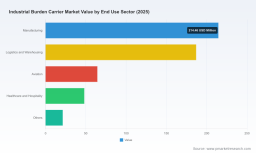
Navigating the Worldwide Industrial Burden Carrier Market: Strategic Trends and Commercial Opportunities (2026–2032)
The global industrial burden carrier market has entered a decisive growth phase, defined by a structural shift from internal combustion to electric propulsion and by widening application scope across manufacturing, logistics, aviation, and healthcare environments. Market valuation climbed from approximately $420.5 million in 2020 to an estimated $535.4 million in 2025, and forward projections indicate sustained expansion toward $750.85 million by 2032.
This trajectory reflects a compound annual growth rate of roughly 4.95 percent across the forecast horizon, with revenue tracked in USD million. The expansion is not merely cyclical; it represents a fundamental recalibration of how facilities move materials, personnel, and equipment within constrained operational footprints. Burden carriers have evolved from niche utility vehicles into integral nodes of intra-facility logistics, bridging gaps between fixed infrastructure and mobile material handling.
Several interconnected challenges and inflection points are reshaping how organizations evaluate burden carrier investments and deployment strategies. First, the industry is navigating a cost and compliance paradox. Zero-emission mandates and indoor air-quality regulations across more than sixty countries are accelerating electrification, yet transition timelines vary significantly by jurisdiction, creating fragmented compliance landscapes and uneven capital planning cycles. Second, supply chain volatility in critical inputs continues to pressure pricing and lead times. Global iron ore benchmarks for China-imported 62% Fe fines are forecast to ease from approximately $100 per ton in 2025 to $90 per ton in 2026, influencing steel costs for chassis and frames. At the same time, US Midwest hot-rolled coil steel prices are expected to trade in the $980 to $1,060 per short ton range in early 2026, with flat to slightly rising trends shaped by tariff dynamics and manufacturing activity. These inputs directly affect build economics for heavy-duty frames, load beds, and structural components. Third, organizations face an operational integration challenge. Rising warehouse automation and persistent labor shortages in manufacturing and logistics sectors are increasing reliance on burden carriers to improve throughput and reduce manual handling, but integrating these vehicles into existing material flow architectures, charging infrastructure, and safety protocols requires disciplined change management.
The market’s concentration profile underscores both stability and opportunity. A core group of established manufacturers holds meaningful share, yet the growth trajectory leaves room for differentiated entrants that can address specialized payloads, ergonomics, and sector-specific compliance requirements.
Hand Trucks Market
Key Drivers Reshaping the Market
Electrification and Propulsion Technology Breakthroughs
Electrification stands as the most conspicuous accelerator in the market. Electric propulsion now commands the overwhelming majority of revenue, reflecting sustained advantages in total cost of ownership, indoor air quality, noise reduction, and simplified maintenance relative to internal combustion alternatives. The performance envelope of electric burden carriers is expanding, with manufacturers introducing flatbed designs, higher payload capacities, enhanced towing capabilities, and cabin configurations that support multi-operator use. Practical demonstrations at industry trade events highlight this shift. At the ARA Show, a new lithium-ion burden carrier featuring a four-seater option and an enclosed cabin option was exhibited, signaling growing demand for versatile, multi-purpose transport platforms. In parallel, enhanced warehouse-focused models are reaching availability, including electric burden carriers with carrying capacities in the 4,400 to 6,600 lb range and towing capacities up to 8,800 lb, tailored for tight pathways and high-throughput environments. These capabilities reduce the need for multiple specialized vehicles, enabling facilities to consolidate intra-facility transport around fewer, more adaptable assets.
Policy and Regulatory Momentum
Regulatory direction continues to reinforce electrification while raising the bar for safety and operational reliability. Zero-emission mandates and indoor air-quality regulations across more than sixty countries, including frameworks aligned with the EU Green Deal and US EPA guidelines, are steering procurement toward electric platforms and away from combustion-based alternatives. Concurrently, ISO 3691-1 safety requirements and verification for self-propelled industrial trucks remain the active standard governing design and operation of related equipment, reinforcing expectations around stability, operator protection, braking, and load handling. For manufacturers and buyers alike, these standards create a predictable compliance baseline but also demand rigorous validation, especially as vehicle designs diversify and operational contexts broaden. Organizations that align product development and procurement with these expectations can reduce time-to-deployment and lower lifecycle risk.
Demand-Side Shifts in Operational Behavior
Demand is being reshaped by changing facility economics and workforce dynamics. Warehouses, distribution centers, manufacturing plants, airports, and healthcare campuses increasingly require flexible, low-emission vehicles that can move both materials and personnel within constrained spaces. The rise of automation and persistent labor constraints heightens the value of burden carriers that improve throughput, reduce manual handling, and integrate cleanly with broader logistics systems. Operator experience is also receiving greater attention. Recent product introductions feature larger operator compartments and improved ergonomics designed specifically for burden carrier applications, reflecting a focus on comfort, visibility, and productivity during extended shifts. As facilities pursue tighter material flow and fewer process handoffs, they are gravitating toward platforms that combine payload flexibility with towing capacity and maneuverability, rather than single-purpose equipment.
Cost Structure and Supply Chain Realities
Cost dynamics are evolving as electrification reduces fuel and maintenance burdens while steel and component inputs continue to fluctuate. Declining iron ore benchmarks may ease some chassis and frame costs, but regional steel pricing remains sensitive to tariffs and manufacturing conditions, keeping build economics in flux. Manufacturers are responding with modular architectures, configurable payloads, and design choices that balance durability with cost efficiency. For buyers, the economic case increasingly centers on total cost of ownership, uptime, and integration rather than sticker price alone. This shifts the purchasing conversation toward lifecycle analysis, charging strategy, parts availability, and service support—factors that can determine whether an initial purchase translates into sustained operational value.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a mix of specialized manufacturers and broader material handling brands, each pursuing distinct value propositions. Motrec International Inc., based in Quebec, Canada, offers customizable electric flatbed burden carriers with load capacities up to 5,000 lbs, targeting heavy-duty material transport in industrial facilities, warehouses, and manufacturing plants. Taylor-Dunn Manufacturing Company, headquartered in Anaheim, California, specializes in electric burden carriers including Bigfoot series models with payloads up to 3,000 lbs and towing up to 10,000+ lbs, suited for warehouses, railyards, airports, and tight industrial pathways. Cushman, part of Textron Specialized Vehicles and based in Augusta, Georgia, provides electric burden carriers such as Titan HD, Minute Miser, and Stock Chaser models for personnel and material transport across warehouses, manufacturing, and commercial industrial settings. Pack Mule, operating under Capacity Trucks in the USA, manufactures heavy-duty NXG and ALPHA series electric burden carriers with high payload and towing capacities for manufacturing plants, warehouses, and distribution centers. Johnson Industries Inc., located in Kentucky, focuses on high-quality industrial burden carrier vehicles emphasizing operator safety and efficiency for mining and heavy industrial applications. Trowin Industries, based in the USA, offers flatbed burden carriers for maintenance, rescue, baggage handling, and passenger transport in industrial environments. Columbia ParCar Corp, in Reedsburg, Wisconsin, supplies Payloader Pro and other electric burden carriers for industrial material and personnel movement. Bobcat Company, headquartered in West Fargo, North Dakota, produces BBC23S-7 and BBC28S-7 electric burden carriers with carrying capacities of 4,400 to 6,600 lbs and towing up to 8,800 lbs for warehouse and construction facilities. Toyota Material Handling, in Columbus, Indiana, includes industrial burden carriers within its broader material handling portfolio for efficient intra-facility transport. HC Forklift America, based in the USA, introduces lithium-ion electric burden carriers with multi-seater options for material, equipment, and personnel transport in manufacturing, airports, and workshops.
Leading strategies reveal clear differentiation paths. One approach centers on customization and payload flexibility, enabling buyers to match vehicle configurations to specific aisle widths, load types, and towing requirements. Another emphasizes ergonomics and multi-purpose use, with larger operator compartments, enclosed cabin options, and multi-seater configurations that support mixed material and personnel transport. A third strategy leans into application specialization, with designs tuned for mining, heavy industrial environments, baggage handling, and rescue operations, where durability, safety, and operational resilience take precedence. Recent developments illustrate this competitive dynamism. Taylor-Dunn launched the Bigfoot S series with a larger operator compartment and improved ergonomics for burden carrier applications, reinforcing the ergonomic and comfort angle. Bobcat Company made the 2026 BBC28S-7 electric burden carrier available with enhanced warehouse capabilities, highlighting the ongoing push to adapt electric platforms for high-throughput logistics. HC Forklift America showcased a new lithium-ion burden carrier with a four-seater option and enclosed cabin option at the ARA Show, reflecting growing interest in versatile, enclosed, multi-operator platforms.
Market evolution appears to be moving along two parallel tracks. On one hand, established brands are extending their electric portfolios and integrating burden carriers into broader material handling ecosystems, creating one-stop sourcing advantages and cross-selling opportunities. On the other hand, specialization is intensifying as buyers seek vehicles optimized for specific workflows, payload profiles, and regulatory environments. This combination suggests a landscape that will continue to support both consolidation among broad-line providers and fragmentation around niche applications, with new entrants competing on configurability, safety features, and total cost of ownership rather than price alone.
Industrial UPS Market
Future Trends and Commercial Implications (2026–2032)
Looking ahead, three trends are likely to shape the next three to five years. First, electrification will deepen into a broader operational standard rather than a procurement preference. As zero-emission mandates and indoor air-quality regulations expand across more jurisdictions, and as lithium-ion technologies improve energy density and charging convenience, facilities will increasingly default to electric burden carriers for both material and personnel transport. This creates opportunity for providers that can deliver reliable charging integration, predictable uptime, and scalable fleet management.
Second, application convergence will accelerate. Vehicles that combine flatbed utility, higher towing capacity, multi-operator seating, and enclosed cabin options will become more valuable as facilities consolidate workflows and reduce the number of specialized assets. The commercial opportunity lies in designing platforms that can serve multiple roles without sacrificing safety, maneuverability, or payload integrity. Buyers will reward flexibility that lowers fleet complexity while maintaining operational resilience.
Third, cost and supply chain management will remain decisive. Even as iron ore price trajectories may ease some steel-related pressures, regional steel pricing, tariff effects, and component availability will continue to influence build economics and delivery timelines. Manufacturers that can stabilize input costs through modular design, strategic sourcing, and configurable options will gain an edge. For buyers, disciplined total cost of ownership analysis, charging infrastructure planning, and service network access will be essential to capturing value.
PW Consulting
Potential risks and uncertainties should not be overlooked. Regulatory timelines and enforcement intensity may diverge by region, creating uneven adoption curves. Supply chain disruptions could affect steel and component availability, influencing pricing and lead times. Safety and compliance expectations, anchored by standards such as ISO 3691-1, will continue to evolve, requiring ongoing validation and design discipline. Organizations that prepare for these dynamics—by diversifying sourcing, aligning procurement with regulatory trajectories, and investing in operator training and infrastructure—will be better positioned to navigate volatility and capitalize on growth.
Strategic Recommendations for Decision Makers
For manufacturers, the priority is to sharpen differentiation around payload flexibility, ergonomics, and application-specific safety while maintaining disciplined cost control. Modular architectures, configurable cabin and flatbed options, and clear compliance alignment can broaden addressable use cases without inflating complexity. Investing in charging compatibility, serviceability, and operator-centered design will strengthen long-term competitiveness as electrification becomes the default.
For investors, the growth profile suggests selective exposure to platforms that combine electric propulsion with multi-purpose capability and strong total cost of ownership narratives. Due diligence should focus on supply chain resilience, regulatory alignment, and the ability to serve high-growth application segments such as logistics, warehousing, and multi-role facility transport. Monitoring regional steel pricing, tariff dynamics, and component availability will help anticipate margin pressures and timing risks.
For procurement and operations leaders, the emphasis should shift from unit price to lifecycle value. Evaluating charging infrastructure needs, uptime expectations, maintenance models, and operator safety features will lead to more durable purchasing decisions. Aligning burden carrier selection with facility workflow, aisle constraints, and future expansion plans can reduce fleet complexity and improve throughput over time.
For organizations seeking deeper segmentation data, company-level benchmarking, and tailored guidance on deployment scenarios, a comprehensive research report is available to support detailed evaluation and planning.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Burden Carrier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com