

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
3D Printed Prosthetic Hands Market: Why 15.12% CAGR Drives $372M Growth by 2032

Global Strategic Outlook: The 3D Printed Prosthetic Hands Market
Market Current State and Core Challenges
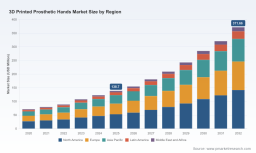
The worldwide market for 3D printed prosthetic hands has entered a phase of accelerated expansion, driven by converging advances in additive manufacturing, growing clinical acceptance, and shifting reimbursement frameworks. Over the 2020 to 2025 period, the sector moved from a niche innovation space into a commercially viable segment within the broader prosthetic device industry. Market valuation climbed from approximately USD 71.4 million in 2020 to USD 138.7 million in 2025, reflecting sustained year-over-year growth that outpaces many traditional medical device categories. Looking ahead to the 2026 through 2032 forecast horizon, the trajectory points toward a valuation of roughly USD 371.66 million by 2032, supported by a projected compound annual growth rate of 15.12 percent. This momentum signals that additive fabrication is no longer an experimental alternative but a mainstream production pathway for upper-limb prosthetic solutions.
Several structural factors underpin this growth. The ability to produce patient-specific devices with reduced lead times and lower tooling costs has resonated across clinical and consumer channels. At the same time, advancements in printable materials, sensor integration, and lightweight design have expanded the functional envelope of what 3D printed hands can achieve. The market is also benefiting from broader alignment between technology readiness and healthcare system priorities, particularly the push toward personalized care, faster device delivery, and cost containment without sacrificing clinical quality.
Despite this favorable backdrop, the industry faces a set of interconnected challenges that will shape competitive outcomes over the next several years. The first challenge centers on standardization and regulatory clarity. While additive manufacturing has gained formal recognition as an acceptable fabrication method for custom prosthetic devices under major reimbursement programs, the operationalization of these approvals varies across jurisdictions and payer systems. Manufacturers must navigate device classification expectations, material biocompatibility documentation, and process validation requirements while maintaining the agility that makes 3D printing attractive in the first place. This creates a tension between rapid iteration and the documentation rigor demanded by healthcare procurement and reimbursement pathways.
The second challenge is the uneven distribution of clinical adoption and service infrastructure. High-growth potential in emerging regions is constrained by limited access to fitting expertise, post-delivery adjustments, and localized support networks. Even where devices are affordable to produce, the total cost of ownership for end users can rise sharply if follow-up care, sensor calibration, or socket modifications are difficult to access. This gap between manufacturing capability and service readiness remains a defining bottleneck, especially for body-powered and partial-hand solutions that depend heavily on precise fit and user training.
The third challenge relates to market fragmentation and competitive differentiation. With relatively low barriers to entering the design and printing space, a wide range of organizations—from startups and academic initiatives to established device makers—are pursuing overlapping value propositions. In such an environment, the winners are likely to be those who can combine clinical credibility, reimbursement fluency, and repeatable quality control rather than those who simply offer the lowest price or the most visually distinctive design. The market is therefore transitioning from an innovation-led phase into a maturity phase where execution discipline, evidence generation, and ecosystem partnerships will determine long-term positioning.
Prosthetic Foot Market
Key Growth Drivers Shaping the Market
Technology innovation remains the most visible driver of market expansion, but the nature of that innovation has shifted from proof-of-concept experimentation to clinically oriented engineering. Additive manufacturing now enables multi-grip mechanics, integrated sensing, and breathable or waterproof socket alternatives that improve comfort and usability. Components produced from specialized resins and engineered polymers support faster design cycles and more consistent mechanical performance. Touch-sensing capabilities and wireless electromyographic control illustrate how printed prosthetic hands are becoming more interactive and adaptable to daily tasks. These advancements are not merely cosmetic; they directly influence user satisfaction, adoption persistence, and the perceived value of prosthetic devices among clinicians and patients.
At the same time, material progress is reshaping cost and performance dynamics. Nylon-based and polyamide formulations processed through selective laser sintering and multi-jet fusion methods have become common in durable prosthetic hands and sockets because they offer a strong balance of mechanical resilience, reduced weight, and biocompatibility for patient-specific applications. The practical consequence is that manufacturers can move beyond prototype-grade outputs toward production-grade devices that withstand regular use while retaining customization flexibility. This material maturity reduces a long-standing barrier to adoption: the concern that additively manufactured devices may not match the durability expectations associated with conventionally fabricated prosthetics.
Regulatory and reimbursement developments are acting as a powerful accelerant. A pivotal shift occurred when additive manufacturing was formally recognized as an acceptable and reimbursable fabrication approach for custom prosthetic devices, including sockets, inserts, and additions, under Medicare alignment with existing coding structures. This recognition matters because it connects technological capability with commercial viability. For manufacturers and service providers, reimbursement eligibility transforms 3D printed prosthetics from a grant-dependent or out-of-pocket niche into a scalable clinical offering. It also encourages healthcare providers to incorporate additive fabrication into their procurement and fitting workflows, knowing that the method has been acknowledged within established coverage frameworks.
This regulatory tailwind does not eliminate compliance complexity, but it does reduce one of the largest sources of market uncertainty. Device makers still need to address quality system expectations, demonstrate substantial equivalence where applicable, and maintain product-specific documentation, yet the pathway for custom prosthetic devices produced through additive methods is now more clearly aligned with established reimbursement logic. The result is a more predictable environment for investment, production scaling, and clinical integration.
Demand-side changes are equally important. Patients and clinicians increasingly expect devices that are not only functional but also adaptable to individual anatomy, lifestyle, and aesthetic preferences. In pediatric and congenital limb difference populations, improved dexterity, range of motion, and reduced co-activation have been associated with better user experience and functional outcomes. These clinical observations reinforce demand for devices that can be refined quickly and fitted more precisely than many conventional alternatives. Meanwhile, individual users, families, and nonprofit organizations continue to seek lower-cost options that do not sacrifice essential function, expanding the addressable market beyond hospital and clinic settings.
Supply chain and cost structure shifts are reinforcing these demand trends. In-house additive manufacturing and targeted partnerships with printing technology providers allow companies to compress production cycles, reduce inventory risks, and respond more quickly to design refinements. Scaling up printing capacity within controlled manufacturing environments supports cost reduction while preserving the advantages of customization. For businesses, this means the traditional trade-off between mass production efficiency and individualized fit is becoming less severe. The organizations that can manage design standardization, repeatable printing processes, and post-processing quality will be best positioned to translate technical potential into reliable commercial output.
Competitive Landscape and Leading Strategies
The competitive field is diverse, but a clear pattern is emerging: successful players are differentiating through a combination of clinical approval, reimbursement alignment, material and sensor innovation, and service-oriented distribution models. One prominent approach is represented by companies focused on clinically approved, insurance-reimbursed multi-grip myoelectric hands and arms with customizable covers and activity attachments. Their emphasis on lightweight construction, expressive design, and clinically integrated sockets illustrates how commercial credibility and user experience can be pursued together. By maintaining a family of models suited to different environments and user needs, these players aim to broaden adoption while preserving a consistent brand and quality proposition.
A second strategic orientation emphasizes speed, durability, and sensory feedback. Some manufacturers are building lightweight bionic hands with touch-sensing capability using 3D printed major components, then scaling in-house printing capacity to drive down unit costs and accelerate iteration. The commercial logic here is compelling: faster production and lower cost can expand access, while touch feedback and rapid responsiveness enhance functional value. This model also benefits from strong alignment with reimbursement developments, since Medicare coverage for such devices supports broader deployment and reduces reliance on limited grant-based channels.
3D Printed Face Shields Market
A third orientation focuses on partial-hand and body-powered solutions for users who need targeted functional restoration rather than full-hand replacement. These offerings often rely on durable nylon-based additive manufacturing and emphasize custom fit, daily-task performance, and mechanical reliability. The strategic value lies in serving a specific patient population with a clear functional need, where fit precision and task-specific design can create strong clinical loyalty and repeat engagement through adjustments and accessory use.
Beyond commercial manufacturers, nonprofit and community-oriented models are also shaping the landscape. Some organizations center their work on low-cost fabrication and localized training in underserved regions, partnering with clinics to enable custom fitting and delivery. Others concentrate on personalized, EMG-powered devices for children and adults, frequently incorporating expressive designs and collaborating with hospitals through clinical trial and partnership frameworks. These initiatives broaden access and generate real-world usage data, while also highlighting the importance of service networks, training, and long-term support in markets where device cost is only one part of the adoption equation.
Taken together, the field is neither fully consolidated nor chaotically fragmented. Concentration metrics indicate that larger players hold meaningful but not dominant shares, leaving substantial room for differentiation and selective consolidation. The market is likely to evolve through a mix of vertical integration, partnership formation, and specialization. Vertical integration can reduce cost and improve quality consistency by consolidating socket, arm, and hand production within a controlled environment. Partnerships can extend reach into clinical networks, rehabilitation settings, and regional service ecosystems. Specialization will remain attractive for companies that can own a specific need segment, whether that is pediatric expression, partial-hand function, touch-enabled myoelectric control, or low-cost deployment in underserved areas.
The most consequential trend in competitive strategy is the shift from design novelty to deployment credibility. In a market where multiple organizations can produce visually impressive devices, durable advantage will increasingly depend on reimbursement competence, clinical evidence, regulatory readiness, and the ability to deliver consistent post-fit support. Companies that treat 3D printing as a complete operational system—encompassing design controls, material selection, production scaling, and service infrastructure—will be better positioned than those that treat it as a standalone fabrication shortcut.
Future Trends to Watch Over the Next 3 to 5 Years
One major trend is the continued convergence of reimbursement alignment and manufacturing scale-up. As additive fabrication becomes more firmly embedded in covered prosthetic workflows, companies that can demonstrate repeatable quality, appropriate documentation, and reliable supply will be able to expand more confidently. This should favor organizations that invest early in process validation, material traceability, and clinical integration rather than those relying primarily onDesign-led differentiation. Over time, the market is likely to reward players who can show that printed prosthetics can be delivered consistently across sites, user populations, and reimbursement environments.
A second trend is the widening role of smart features and user-centered customization. Touch sensing, improved electromyographic control, modular activity attachments, and comfort-focused socket designs are expected to become more common as manufacturers refine both hardware and user experience. The commercial implication is that value will shift not only from basic grasp function to broader quality-of-life benefits, including adaptability, comfort, and ease of use. This creates opportunities for companies that can package sensor, software, and design improvements into coherent products rather than isolated technical features.
PW Consulting
A third trend is the growth of hybrid delivery models that blend centralized manufacturing with localized fitting and support. In regions where reimbursement and clinical infrastructure are developing, the ability to train local partners, support regional printing or assembly, and maintain follow-up care can determine whether products achieve scale. This approach may also help address the service-readiness gap identified earlier, especially for body-powered and partial-hand devices where fit and user training strongly influence outcomes. At the same time, there is risk that uneven regulatory interpretation, material supply constraints, or inconsistent service quality could slow expansion if not managed carefully.
These trends point to a market that is moving toward broader clinical acceptance and more structured commercialization, but not without friction. Uncertainty remains around how quickly payers and providers will standardize around additive workflows, how consistently quality can be maintained across expanding production networks, and whether smart-feature enhancements will translate into measurable functional gains that justify premium positioning. Companies that monitor these dynamics closely will be better prepared to time investments and prioritize the most resilient opportunities.
Strategic Actions for Decision Makers
For manufacturers, the priority is to build a credible operating model around additive prosthetic production, not just a compelling product concept. That means investing in process standardization, material selection, quality documentation, and reimbursement fluency alongside design innovation. Companies should also assess whether they can strengthen positioning through vertical integration, clinical partnerships, or targeted specialization in a high-need segment such as partial-hand restoration, pediatric use, or touch-enabled myoelectric control. The businesses most likely to scale will be those that can prove repeatability and service reliability in addition to performance.
For investors, due diligence should focus on reimbursement readiness, regulatory pathway clarity, manufacturing scalability, and evidence of clinical adoption beyond early adopters. Interest in the sector should be calibrated to teams that understand the operational demands of custom medical device production and can show a realistic route from prototype to consistent delivery. Portfolio exposure may be most effective where it supports companies with clear differentiation, defensible quality systems, and credible plans for service delivery and post-fit support.
For procurement leaders and healthcare organizations, the practical task is to evaluate additive prosthetic options against total value rather than initial device cost alone. Factors such as fitting turnaround, adjustment support, sensor calibration, durability documentation, and alignment with reimbursement codes can materially affect outcomes and total cost of ownership. Engaging early with suppliers that can provide transparent process controls and service commitments will help organizations integrate 3D printed prosthetic hands into clinical pathways with greater confidence.
Given the pace of regulatory, reimbursement, and technology change, decision makers benefit from continuously updated segmentation, competitive mapping, and region-specific adoption dynamics. More detailed data on market size by segment, company positioning, and forward scenarios can support more precise planning and reduce exposure to blind spots in a rapidly evolving market. For that reason, accessing a comprehensive research report can provide the granular context needed to translate these high-level trends into actionable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide 3D Printed Prosthetic Hands Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com