

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
FPD Lithography Systems Market: Why 5.71% CAGR and APAC's 85% Share Redefine Global Competition

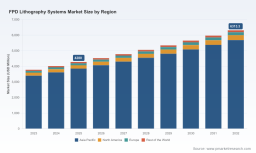
Worldwide FPD Lithography Systems Market: Strategic Trends and Commercial Opportunities Through 2032
Market Context and Core Challenges
The global market for flat panel display lithography systems has expanded steadily over the past five years, with total revenue reaching approximately $4.28 billion in 2025 and projected to grow at a compound annual growth rate of 5.71 percent through 2032. This trajectory reflects sustained capital investment in display manufacturing capacity, driven by demand for larger, higher-resolution, and more specialized screens across consumer electronics, automotive, and commercial applications. Asia Pacific dominates absolute market volume due to the concentration of panel fabrication facilities and equipment procurement clusters, while North America, Europe, and other regions maintain smaller but strategically important installations, often tied to specialized display formats, defense-related applications, or regional supply chain diversification efforts.
Within this landscape, the competitive structure remains highly concentrated. A small number of established suppliers account for the overwhelming majority of shipments, reflecting the capital intensity, precision engineering requirements, and long qualification cycles associated with lithography equipment. This concentration provides stability in service and support ecosystems but also constrains rapid price competition and slows the entry of alternative technology approaches. At the same time, the product mix continues to be shaped by the relative demand for steppers and scanners, with each architecture serving distinct patterning needs depending on panel size, resolution targets, and throughput requirements.
Several structural challenges define the current inflection point. First, panel manufacturers are navigating a period of mixed demand signals, where near-term investment timing is being reassessed as buyers evaluate the impact of trade policy shifts and downstream consumption patterns. This has introduced short-term volatility in equipment order books, even as the medium-term build-out of advanced display capacity continues. Second, environmental and chemical compliance frameworks are reshaping process choices. Regulatory pressure to reduce hazardous substances in lithography-related consumables and cleaning steps is increasing validation costs and influencing equipment design, particularly for suppliers serving multiple regulatory jurisdictions. Third, the boundary between display patterning and advanced packaging is blurring as multi-lens lithography concepts are adapted for back-end semiconductor processes. This cross-pollination creates both opportunity and complexity, as equipment roadmaps must increasingly account for applications that extend beyond traditional panel lines. These dynamics mean that market growth cannot be understood purely as a function of capacity expansion; it now depends on how well suppliers and buyers align technology choices with evolving regulatory, geopolitical, and application-specific requirements.
Key Drivers Shaping Market Change
Technology innovation remains the most direct catalyst for differentiation in FPD lithography. Multi-lens architectures, improved overlay control, and new light-source optimizations are enabling higher throughput and finer definition on larger substrates. Recent product announcements illustrate this direction clearly. In late 2025, Nikon began accepting orders for Gen 8 FPD lithography systems using UV-LED light sources, with a commercial launch planned for 2026. These models emphasize reduced power consumption alongside high-definition LCD and OLED panel production, signaling a shift toward energy efficiency as a competitive attribute rather than a secondary consideration. The same multi-lens lineage is also being extended into back-end semiconductor packaging, where a digital lithography system announced in mid-2025 targets one-micron resolution and high productivity. This dual-use technology strategy broadens the addressable market for core optical and mechanical competencies while reinforcing the value of established engineering know-how.
PW Consulting
Policy and regulatory conditions are equally influential. Export controls on advanced semiconductor manufacturing equipment have expanded to cover certain lithography systems and components, with restrictions targeting specific entities and broader categories such as DUV and advanced packaging tools. These measures reshape cross-border equipment flows, encourage regional sourcing strategies, and increase the importance of compliance infrastructure for both suppliers and end users. At the same time, European chemical regulations continue to constrain the use of certain hazardous materials in lithography-adjacent processes. While these frameworks do not directly ban FPD lithography machines, they raise compliance costs and influence material selection, cleaning protocols, and vendor qualification timelines. For global suppliers, the practical implication is that product support cannot be decoupled from jurisdictional readiness; systems that can be deployed with fewer material and documentation risks gain an advantage in multi-region programs.
Demand-side behavior is evolving as display applications diversify. Automotive dashboards, ruggedized interfaces, and specialty display formats are increasing interest in larger-area panel processing, while smartphone and portable device requirements continue to drive volume in smaller and medium panel segments. This split is not merely a matter of substrate size; it affects cycle times, yield expectations, and the relative importance of overlay precision versus throughput. Buyers are increasingly selecting equipment based on application fit and total cost of ownership rather than on headline specifications alone. As a result, suppliers that can demonstrate predictable performance across multiple panel formats, with flexible light sources and robust service networks, are better positioned to capture multi-year deployment cycles.
Worldwide Direct-write Photolithography Systems Market
Supply chain and cost structure considerations further shape the market. Panel makers are balancing the desire for cutting-edge capability with the need to manage capital exposure, especially when macroeconomic signals or tariff environments introduce uncertainty. This has led to more deliberate investment pacing, with buyers weighing whether to accelerate capacity, defer purchases, or select systems that offer broader compatibility across current and future panel generations. For equipment vendors, this environment rewards designs that reduce operating energy, simplify consumables handling, and provide modular upgrade paths. The net effect is a market where technical performance still matters profoundly, but commercial resilience—through lower running costs, flexible configuration, and regulatory adaptability—is becoming equally important in procurement decisions.
Competitive Landscape and Leading Strategies
The competitive structure in FPD lithography systems is anchored by a small group of incumbent suppliers with deep optical, mechanical, and process-integration expertise. Nikon maintains a prominent position through its FX-series platform for large-area plates, and its recent focus on UV-LED light sources reflects an effort to align performance with energy efficiency and high-definition panel requirements. The company's expansion of multi-lens technology into digital lithography for back-end packaging also illustrates a broader strategy: leverage core optical competencies across adjacent markets to extend revenue potential and amortize development costs. Canon continues to compete with mirror-projection systems designed for array, color filter, and touch panel processes, with recent releases supporting Gen 6 plates for dashboard displays and smartphones. This product emphasis highlights a strategy centered on application-specific productivity and overlay accuracy for high-volume consumer and automotive display segments.
A third dimension in the landscape comes from domestic equipment development in China, where suppliers are building FPD lithography capabilities as part of broader semiconductor and display equipment initiatives. This development introduces a longer-term dynamic around regional self-sufficiency and localized support ecosystems. While the established incumbents still dominate overall shipment value, the presence of new and expanding suppliers can influence pricing expectations, service competition, and the pace at which regional buyers diversify their vendor base. The practical outcome is a market that remains concentrated but is gradually being tested by localized capability building, especially where policy incentives and domestic panel expansion reinforce demand for homegrown equipment alternatives.
Looking at strategic positioning, the leading suppliers are differentiating along three axes. The first is platform versatility, where the ability to serve multiple panel sizes and light-source configurations reduces the risk of stranded investment for buyers. The second is application extension, where technology reuse across FPD and advanced packaging broadens the commercial base and creates cross-functional engineering leverage. The third is compliance and support readiness, where suppliers that can navigate export control frameworks, chemical regulations, and regional service expectations are better equipped to sustain multi-country programs. These axes matter because FPD lithography is not a purely specification-driven purchase; it is a long-cycle capital decision shaped by qualification timelines, process integration, and operational risk. In that context, suppliers that deliver predictable performance with lower regulatory and energy-related friction are likely to capture disproportionate share in multi-year deployment cycles.
Future Trends and Commercial Implications
Over the next three to five years, the market is likely to consolidate around a few durable trends. The first is the continued migration toward energy-efficient light sources and process optimizations that lower operating costs without sacrificing throughput or definition. As panel makers face both cost pressure and sustainability expectations, equipment that reduces power consumption while maintaining high-definition output will become a stronger differentiator in procurement evaluations. The second trend is the growing relevance of multi-lens and digital lithography concepts beyond traditional panel lines. As back-end packaging and specialty patterning applications adopt similar optical architectures, suppliers with adaptable platforms can capture incremental demand and create cross-market roadmap synergies. This expansion also increases the strategic importance of resolution, overlay stability, and productivity in a wider set of use cases.
Flat Panel Display (FPD) Inspection Equipment Market
The third trend is a more regionally differentiated market rhythm. Export controls, aligned policy actions, and shifting tariff environments are prompting panel manufacturers and equipment buyers to reassess procurement timing and vendor selection. In the near term, this can manifest as temporary pauses in investment as buyers gauge downstream demand and policy impacts. Over a longer horizon, it is likely to encourage more diversified sourcing strategies and greater emphasis on regional support, documentation readiness, and compliance-compatible configurations. The commercial opportunity here lies in aligning product roadmaps with deployment realities: systems that can be integrated quickly across multiple regulatory contexts, supported locally, and scaled across panel formats will be better positioned to win in a fragmented but still growing market.
Potential risks should not be underestimated. Demand timing remains sensitive to consumer electronics cycles, automotive display programs, and broader trade policy uncertainty. Chemical and environmental compliance costs may rise further, particularly for suppliers operating across multiple jurisdictions. And while platform versatility is valuable, overextension into adjacent applications can strain engineering resources if qualification and service commitments are not matched to market readiness. The commercial implication is that growth will increasingly accrue to participants who can balance technical ambition with operational pragmatism, selecting where to lead on performance and where to compete on total cost of ownership and deployment flexibility.
Strategic Actions for Decision Makers
For display and equipment manufacturers, the priority is to align product and capacity planning with the applications that offer the best balance of volume, margin, and regulatory compatibility. This means evaluating light-source efficiency, multi-panel flexibility, and service readiness as first-order decisions rather than secondary features. For investors, the opportunity lies in identifying participants with durable platform reuse, strong compliance infrastructure, and credible paths into adjacent packaging or specialty patterning applications, while monitoring demand-pacing signals that can affect near-term order visibility. For procurement teams and panel makers, the focus should be on total cost of ownership across the deployment lifecycle, including energy consumption, consumables and chemical compliance, qualification lead times, and regional support coverage. In a market where investment timing is increasingly sensitive to policy and demand uncertainty, detailed visibility into product roadmaps, regulatory impact, and application-specific requirements can materially improve capital allocation decisions. A closer review of the full market data set, including segmentation detail and company-level developments, can help decision makers sharpen those choices with greater precision.
For detailed analysis of this topic, please visit the official page: Worldwide FPD Lithography Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com