

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: PEG Market Hits $5.78B in 2025, Projects 6% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Navigation in the Polyethylene Glycol (PEG) Market: A 2026 Decision-Maker's Guide
The global chemical landscape is undergoing a period of recalibration, and few intermediates illustrate this complexity better than polyethylene glycol. As a versatile polymer used across pharmaceuticals, personal care, and industrial processing, PEG sits at the intersection of supply chain dynamics, regulatory scrutiny, and evolving end-use demand. For executives and strategic planners operating in 2026, understanding the trajectory of this market is not merely an academic exercise; it is a prerequisite for resilient supply chain design, product portfolio optimization, and competitive positioning. PW Consulting's latest market research on the Polyethylene Glycol (PEG) Market delivers the granular intelligence required to navigate these shifting currents. This article outlines the strategic horizon, contextualizes the macroeconomic environment, and demonstrates how the full report translates data into actionable foresight.
Macro Trajectory and the 2026 Inflection Point
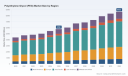
The PEG market has demonstrated consistent organic expansion, with revenue climbing from 4.4 thousand million USD in 2020 to approximately 5.78 thousand million USD by 2025. This historical progression establishes a clear baseline of demand resilience, but the true strategic signal lies in the forward-looking forecast. From 2026 through 2032, the market is projected to advance at a compound annual growth rate of 6.0 percent, reaching an estimated valuation of 8.66 thousand million USD by the close of the forecast window. This trajectory reflects more than incremental growth; it signals structural demand shifts that will reward operators who can align capacity, formulation capabilities, and regional logistics ahead of the curve.
For 2026 decision-makers, the immediate takeaway is that the market is entering a phase where volume growth competes with margin preservation. The historical record shows that between 2020 and 2025, the market compounded at a rate that outpaced many adjacent specialty chemical segments, driven by persistent pharmaceutical excipient requirements and expanding personal care formulations. Looking forward, the forecast period embeds assumptions about capacity additions, trade flow adjustments, and the gradual integration of emerging applications. Executives who rely on headline figures alone risk missing the underlying volatility of input costs, regional supply tightness, and the strategic implications of concentration among top-tier producers.
Concentration, Competitive Density, and the Barrier to Entry
Market structure matters as much as market size. The PEG sector is moderately concentrated, with the top three producers collectively accounting for approximately 45 percent of global revenue and the top five commanding roughly 58 percent. This concentration pattern creates a dual reality for market participants. On one hand, established incumbents benefit from scale advantages, formulation know-how, and regulatory compliance track records that raise the barrier to entry. On the other hand, the remaining market share leaves meaningful room for specialized players, regional entrants, and niche application providers to capture value through differentiated molecular weight offerings, GMP-compliant production, or application-specific service models.
Polypropylene Glycol Market
Strategic planners should recognize that concentration metrics are not static. They reflect historical investment decisions, technology licensing, and geographic footprint choices that continue to shape competitive dynamics. The full report dissects how these concentration patterns interact with regional capacity deployment, pricing power, and the strategic behavior of both integrated majors and focused specialty producers. Understanding where scale confers advantage and where agility creates opportunity is essential for assessing partnership opportunities, vertical integration scenarios, and potential displacement risks.
Competitive Landscape: Strategic Profiles of Key Players
The PEG market is contested by a diverse set of global and regional operators, each pursuing distinct value propositions across molecular weight ranges, application verticals, and compliance standards. The following profiles illustrate how leading companies are positioning themselves for the 2026 environment. The complete report extends this analysis with detailed strategic assessments, capacity footprints, and competitive response scenarios.
BASF SE
Headquartered in Ludwigshafen, Germany, BASF maintains a focused offering around its Kollisolv portfolio of ethoxylated polymer-solubilizers designed for oral and topical pharmaceutical formulations. Beyond solubilizers, the company provides reactive PEGs such as Pluriol alongside USP-compliant grades for excipient use. This combination allows BASF to serve formulators who require both functional performance and regulatory-grade consistency. In May 2025, the company expanded its European specialty PEG portfolio with the introduction of reactive polyethylene glycol Pluriol A 2400 I, reinforcing its emphasis on industrial formulators seeking tailored reactivity and solubility profiles. This move underscores a broader strategy of deepening application relevance rather than competing solely on commodity volume.
Dow Inc.
Based in Midland, United States, Dow competes through the CARBOWAX series of PEGs, spanning industrial and pharmaceutical grades. The product line is positioned around solvency, lubricity, and formulation support, making it relevant across personal care, pharma, and industrial applications. Dow's approach leverages a broad brand presence and an application-oriented narrative that connects performance characteristics to end-customer outcomes. For buyers evaluating suppliers, Dow's portfolio breadth offers a reference point for multi-application sourcing strategies, even as regional sourcing preferences and regulatory requirements continue to influence procurement decisions.
Clariant
Headquartered in Muttenz, Switzerland, Clariant offers Polyglykol excipient grades manufactured under IPEC GMP standards, serving pharmaceutical and personal care markets with an emphasis on compliance and quality assurance. A significant strategic development occurred in March 2026, when Clariant expanded its Clear Lake site in Texas to add GMP-compliant manufacturing of pharmaceutical-grade PEG excipients. This expansion created the first U.S. facility dedicated to pharma-grade PEG and extends the company's reach toward Latin American customers. For 2026 planners, this milestone illustrates the growing importance of geographic proximity to regulated end markets and the strategic value of localized GMP capacity in reducing lead times, mitigating supply risk, and supporting regional procurement mandates.
INEOS
London-based INEOS produces PEG 3350 PH and related grades via ethylene oxide polymerization, targeting industrial and personal care applications. The company's positioning reflects the broader relevance of polymer-grade PEG in formulations where cost-performance balance and supply reliability are central. INEOS's participation in the market highlights the enduring role of ethylene oxide-based production routes and the importance of upstream integration for operators seeking to manage feedstock exposure and throughput efficiency.
Lotte Chemical and Sanyo Chemical Industries
Lotte Chemical, based in Seoul, South Korea, supplies PEG products across industrial, personal care, and pharmaceutical applications, reflecting the diversified demand profile of the Asian market. Sanyo Chemical Industries, headquartered in Kyoto, Japan, offers PEG products for a range of industrial and specialty uses. Both companies exemplify how regional manufacturers can compete by aligning product portfolios with local formulation preferences, customer service expectations, and application-specific technical support. Their presence reinforces the reality that the PEG market is not only global in scale but also regionally nuanced in execution.
India Glycols
Noida-based India Glycols focuses on PEG for industrial and personal care markets, representing the growing significance of South Asian production in cost-sensitive application segments. As demand expands in personal care formulations and industrial processing, suppliers positioned in this region can capture share through competitive cost structures and proximity to emerging formulation clusters. The strategic implication for global buyers is the need to balance cost optimization with qualification timelines, regulatory documentation, and supply assurance.
Croda International
Croda International, headquartered in Watford, United Kingdom, provides PEG excipients and additives relevant to personal care and pharmaceutical applications. The company's emphasis on specialty additives and excipient-grade materials aligns with the market's ongoing shift toward formulation performance, regulatory compliance, and ingredient transparency. In an environment where downstream formulators increasingly demand documented quality and application support, Croda's positioning illustrates the value of combining material science with customer-facing technical expertise.
Chinese Producers: Jiangsu Haian Petrochemical Plant and Liaoning Oxiranchem
Jiangsu Haian Petrochemical Plant, located in Jiangsu, China, operates large-scale PEG production oriented toward industrial applications. Liaoning Oxiranchem, based in Liaoning, China, supplies PEG and derivatives for industrial and personal care uses. Together, these companies reflect the scale and cost discipline of Chinese manufacturing in segments where industrial throughput and derivative diversity are competitive differentiators. At the same time, regulatory visibility, sustainability expectations, and qualification requirements continue to shape how international buyers engage with Chinese-sourced PEG, making supply chain due diligence an integral part of procurement strategy in 2026.
Market Dynamics: Feedstock Volatility, Regulation, and Structural Shifts
Strategic planning for PEG in 2026 must account for forces that extend beyond demand forecasting. Feedstock conditions, regulatory evolution, and environmental considerations are reshaping the operating environment and influencing both cost structures and product roadmaps.
Feedstock and Input Cost Environment
Ethylene glycol prices in Asia moved in a mostly downward direction during the second half of 2025 due to strong supply pressure. This development matters for PEG economics because ethylene oxide-derived production remains the foundational route for much of global supply. Input cost movements of this nature can compress margins for producers who lack pricing flexibility, while simultaneously creating negotiation windows for downstream buyers with disciplined procurement strategies. The strategic challenge is not simply to react to price direction, but to build sourcing architectures that can accommodate volatility without compromising supply assurance or qualification status.
Regulatory Pressure and Environmental Considerations
Simultaneously, the European Chemicals Agency has tightened restrictions on polymers that demonstrate persistence in aquatic ecosystems, including PEG derivatives. This regulatory direction reflects broader scrutiny of petroleum-based ethylene oxide derivatives, which are not biodegradable and may contribute to pollution, prompting stricter requirements in some countries. Although PEG remains essential across multiple applications, the regulatory environment is pushing industry participants to evaluate formulation alternatives, lifecycle considerations, and compliance readiness more carefully than before.
For market participants, the implication is twofold. First, regulatory dynamics can influence demand patterns in sensitive application areas, particularly where downstream brands face consumer expectations and sustainability commitments. Second, they elevate the importance of documentation, traceability, and proactive engagement with evolving chemical policy. Companies that treat regulatory change as a static compliance task risk being caught off guard; those that integrate it into product strategy, supplier selection, and regional market planning will be better positioned to sustain access and reputation.
Application Pull and Cross-Segment Interdependencies
Beyond feedstock and regulation, the PEG market is shaped by the varying intensity of demand across medical, personal care, and industrial uses. The medical segment continues to anchor a significant portion of value, driven by the need for well-qualified excipients and formulation consistency. Personal care applications contribute strong volume and formulation innovation, while industrial uses remain essential for solvency, lubricity, and process performance. These segments do not evolve in isolation. A shift in pharmaceutical manufacturing geography, a change in personal care ingredient preferences, or an industrial capacity adjustment can create ripple effects across the entire value chain.
The full report analyzes how these application segments interact with molecular weight preferences and regional demand patterns, providing decision-makers with a framework for scenario planning. For example, formulators targeting pharmaceutical-grade performance must evaluate not only material specifications but also supplier compliance records, audit readiness, and geographic supply continuity. Similarly, industrial users focused on cost efficiency must weigh the trade-offs between large-scale sourcing and the risk of regional tightness or regulatory disruption.
Polyethylene Glycol (PEG) Market
What the Full Report Delivers for 2026 Decision-Making
PW Consulting's Polyethylene Glycol (PEG) Market research is designed to move beyond descriptive market sizing and into the operational and strategic territory where executives make trade-offs. The report combines macro-level trajectory with segment-level context, competitive analysis, and dynamic market forces, all structured to support practical decision-making in a complex environment.
Segment and Application Context Without Operational Blind Spots
The research examines the market through multiple segmentation lenses, including molecular weight ranges, application categories, and regional demand patterns. Rather than presenting these splits as isolated statistics, the report interprets them as indicators of formulation preferences, qualification requirements, and purchasing behavior. This approach helps planners understand where demand is concentrated, which molecular weight ranges carry disproportionate strategic importance, and how application categories influence supplier selection.
Because the market is not uniform, executives need to know not only where growth is occurring, but also which segments are exposed to input volatility, regulatory pressure, or regional capacity constraints. The report maps these sensitivities so that strategy teams can prioritize the most consequential variables instead of treating the market as a single homogeneous opportunity.
Competitive Positioning and Strategic Response Scenarios
A core strength of the research is its treatment of the competitive landscape as a strategic system rather than a list of players. By profiling leading companies and recent developments, the report clarifies how incumbents are expanding compliant capacity, introducing reactive or specialty grades, and aligning production footprints with regional demand and regulation. It also provides the analytical foundation for evaluating potential competitive responses to feedstock shifts, regulatory changes, and new capacity entry.
For strategy teams, this means the report supports use cases such as supplier qualification prioritization, partnership evaluation, capacity planning assumptions, and risk assessment around concentration and regional sourcing. Instead of forcing teams to reconstruct the competitive environment from fragmented sources, the research consolidates the relevant context into a decision-ready structure.
Dynamic Market Forces: Feedstock, Regulation, and Environmental Risk
The report integrates the operational realities that shape margin and access in the PEG market. It addresses the impact of feedstock pricing direction, especially the downward pressure observed in Asia during late 2025, and frames how this environment affects procurement timing, contract strategy, and cost planning. It also examines the trajectory of regulatory tightening around polymer persistence and petroleum-derived derivatives, translating these developments into practical considerations for product roadmap decisions, compliance readiness, and market access planning.
By placing these dynamics in the same analytical frame as demand and competition, the research helps leaders weigh trade-offs more effectively. A procurement decision that appears favorable on price may have hidden exposure to regulatory or supply continuity risk. A capacity investment that seems justified by demand growth may require a stronger compliance and sustainability narrative to withstand scrutiny in regulated end markets. The report provides the context needed to evaluate such choices with greater confidence.
Forecast Discipline for Long-Range Planning
The forecast period from 2026 through 2032 is not presented as a single deterministic path. Instead, the research uses the 6.0 percent compound annual growth rate and the related revenue trajectory as a baseline for stress-testing assumptions about capacity, regional expansion, and application adoption. This discipline is particularly important for capital-intensive decisions and multi-year sourcing commitments, where the difference between a base-case forecast and an overconfident extrapolation can be material.
Executives can use the forecast structure to align internal planning horizons, assess the timing of strategic initiatives, and identify the range of outcomes that would change a decision. In that sense, the research functions as both an intelligence resource and a planning scaffold, helping teams connect market signals to concrete actions.
Conclusion: Turning Market Intelligence into Strategic Advantage
The Polyethylene Glycol (PEG) Market in 2026 is defined by steady medium-term growth, a moderately concentrated competitive field, and an operating environment shaped by feedstock conditions, regulatory scrutiny, and application-specific demand dynamics. The headline trajectory suggests continued expansion, but the strategic value lies in understanding how that expansion is distributed, how competitors are positioning, and where risk and opportunity concentrate across segments and regions.
PW Consulting's full market research translates this complexity into a structured intelligence platform for executives who must make sourcing, partnership, capacity, and portfolio decisions under uncertainty. It connects historical performance to forward-looking scenarios, profiles the strategic behavior of key producers, and embeds the regulatory and feedstock forces that will influence margins and market access. For decision-makers seeking more than macro-level estimates, the report offers the depth required to act with precision.
To access the complete segmentation analysis, competitive assessments, regional demand context, and scenario-ready forecast detail, readers are invited to explore the full PW Consulting Polyethylene Glycol (PEG) Market research. The source report provides the operational granularity necessary to convert industry insight into confident, evidence-based strategy.
For detailed analysis of this topic, please visit the official page: Polyethylene Glycol (PEG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electronics Components Market to Hit $717.6B by 2032, Growing at 7.36% CAGR
By pmarketresearch, 2026-09-15
Navigating the Next Phase: Strategic Intelligence for the Electronic Components Market 2026–2032
The global electronic components industry stands at a decisive inflection point. After five years of steady expansion, the market has transitioned from post-pandemic normalization to a new cycle defined by technological specialization, supply chain recalibration, and accelerating demand from high-growth end-use sectors. For executives, procurement leaders, and R&D strategists, the window to align product roadmaps, capacity planning, and partnership ecosystems with this shift is narrow. This introduction outlines how our newly released Electronic Components Market study translates raw market signals into actionable intelligence, equipping your organization with the foresight required to navigate 2026 and beyond.
Market Trajectory: From Recovery to Structural Growth
The historical trajectory of the electronic components sector reveals a market that has consistently outpaced broader industrial benchmarks. Between 2020 and 2025, global revenue climbed from approximately 300 billion USD to 438.5 billion USD, reflecting a compounding pattern of demand recovery, design cycle maturation, and geographic diversification. Our research projects this momentum to accelerate through the 2026–2032 forecast period, with the total addressable market expected to surpass 717 billion USD by 2032. This equates to a compound annual growth rate of 7.36 percent, a figure that underscores not only cyclical recovery but also the structural embedding of advanced electronics into previously underserved sectors.
The speed and scale of this expansion, however, mask underlying volatility. Demand is no longer distributed uniformly across product categories or geographies. Instead, it concentrates in applications demanding higher performance tolerances, longer lifecycle reliability, and tighter integration with software-defined architectures. Organizations that rely on legacy supply arrangements or single-source procurement models will find themselves exposed as lead times fluctuate, material constraints emerge, and regional manufacturing footprints shift. Understanding these dynamics requires more than top-line forecasts; it demands granular visibility into how value flows through the component ecosystem.
Competitive Architecture: Consolidation, Differentiation, and Ecosystem Control
The competitive landscape of the electronic components sector is characterized by a tiered structure of integrated manufacturers, specialized technology leaders, and global distribution networks. At the upper end of the value chain, a concentrated group of firms controls a measurable share of total industry revenue, with the top five players collectively accounting for over half of market output. This concentration reflects deliberate strategies around portfolio breadth, process technology leadership, and long-term customer lock-in through reference designs and firmware ecosystem integration.
Among the most influential manufacturers are firms anchored in analog and mixed-signal innovation, precision sensing, and power conversion. Companies such as Texas Instruments and Analog Devices have built formidable positions by aligning their product roadmaps with industrial automation, medical instrumentation, and automotive electrification. Their competitive advantage stems not merely from volume, but from the ability to deliver silicon solutions that reduce system-level complexity while maintaining stringent reliability standards.
Parallel to this analog-centric tier, European and Japanese power semiconductor leaders have carved out dominant positions in wide-bandgap technologies and automotive-grade discretes. Infineon Technologies, STMicroelectronics, and NXP Semiconductors continue to expand their footprints through targeted capacity investments and application-specific architectures, particularly in electric vehicle powertrains, battery management, and secure connectivity. Renesas Electronics and ON Semiconductor reinforce this momentum with deep portfolios in microcontrollers, intelligent sensing, and high-efficiency power management designed for harsh operating environments.
In the passive and electromechanical domain, Japanese manufacturers remain foundational to global supply. Murata Manufacturing and TDK Corporation drive volume leadership in capacitors, inductors, RF modules, and sensor-integrated components, serving consumer electronics, industrial controls, and infrastructure systems. Amphenol Corporation and TE Connectivity extend the value chain into interconnect systems, where miniaturization, high-speed signal integrity, and durable power transmission increasingly dictate end-product performance. Littelfuse, Vishay Intertechnology, and Panasonic round out the component landscape with specialized contributions in circuit protection, discrete devices, and electronic materials that support system resilience.
Complementing manufacturing concentration is a robust distribution layer that shapes how components reach design engineering teams and production lines. Mouser Electronics, Arrow Electronics, Digi-Key Electronics, Future Electronics, and Avnet operate as critical nodes in the innovation pipeline, frequently serving as the first point of contact for new product introductions and hard-to-source revisions. Regional distributors such as Smith, TTI, RS Components, WPG Holdings, and WT Microelectronics provide localized inventory depth, technical support, and supply chain risk mitigation. The strategic relevance of this distribution tier has intensified as semiconductor lead times fluctuate and engineering teams demand rapid prototyping access without compromising qualification standards.
Recent Developments Shaping the Competitive Landscape
Recent activity among leading players illustrates how quickly strategic priorities can shift in response to capacity, technology, and market signals. In May 2026, Nexperia announced a strategic partnership with Polar Semiconductor to strengthen global production stability for power MOSFETs, a move that directly addresses supply continuity in discrete semiconductor segments. The same month, Infineon Technologies showcased advances in physical AI security solutions tailored for NVIDIA Jetson Thor platforms at PCIM Europe, signaling a deeper convergence between component-level security architecture and edge artificial intelligence deployments. Infineon also reinforced its manufacturing expansion strategy through the operational launch of a new semiconductor plant in Thailand dedicated to power modules, adding geographic diversity to its production base.
On the distribution and service side, Mouser Electronics added more than 9,000 new parts to its catalog in the first quarter of 2026, including over 1,200 semiconductors and electronic components, expanding access to next-generation design options. Future Electronics launched a quarterly digital campaign centered on industrial automation innovation, reinforcing its positioning in automation-heavy verticals. These actions, taken together, highlight a market where speed-to-market, regional capacity balancing, and ecosystem engagement increasingly determine competitive advantage.
Demand Architecture: Where Growth Is Concentrated
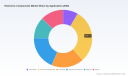
The composition of market demand reveals a landscape far more nuanced than aggregate revenue figures suggest. Consumer electronics continue to represent the largest single application block, driven by iterative upgrades in smart devices, connectivity infrastructure, and high-integration subsystems. Telecommunications maintain a substantial footprint, supported by network modernization, edge processing requirements, and the relentless push toward higher bandwidth and lower latency. Industrial applications contribute a robust and increasingly resilient demand base, as automation, robotics, electrification of plant equipment, and condition monitoring systems integrate more sophisticated control and sensing architectures.
Electronics Market
Automotive remains a critical growth engine, though its component demand profile differs markedly from consumer volumes. Vehicles now function as distributed computing platforms, requiring microcontrollers, power semiconductors, security-enabled connectivity ICs, and reliable passive networks that can withstand extended lifecycle conditions. Medical electronics represent another structurally attractive segment, where precision analog performance, sensor integration, and regulatory-grade reliability command premium positioning. Other application areas contribute additional demand layers, each with distinct qualification requirements, volume patterns, and supplier relationship dynamics.
By component category, active devices dominate total market value, reflecting the centrality of analog ICs, microcontrollers, power management, and precision components across modern systems. Passive and electromechanical components form an essential complementary layer, underpinning signal conditioning, power distribution, noise suppression, and mechanical-electrical interconnection. The interplay between these categories determines system cost, thermal performance, and board-level layout efficiency, making broad classification an insufficient lens for strategic planning.
Operational Forces Redefining Supply and Planning Assumptions
Behind the top-line growth narrative lies a set of operational realities that will shape procurement and engineering decisions in 2026. Memory chip production has struggled to keep pace with rapidly expanding demand, a supply-demand imbalance reflected in trade flows from major producing economies across South Korea, mainland China, Japan, and Taiwan. This constraint influences not only memory pricing but also the availability of integrated modules and systems that depend on tight component coordination.
Lead time variability remains a persistent concern for design and production planning. Extended availability windows for certain high-demand series, including automotive-grade microcontrollers, have been reported at multi-month ranges, forcing manufacturers to hold deeper safety stock, qualify alternate sources earlier, and adjust bill-of-materials strategies. At the same time, regional manufacturing developments continue to reshape the supply base. New production capacity coming online in Southeast Asia, alongside continued concentration of advanced semiconductor fabrication in Taiwan, introduces both diversification benefits and geopolitical dependencies that procurement teams must monitor continuously.
Regulatory pressure is also entering the cost and sourcing calculus. The European Union's Carbon Border Adjustment Mechanism has begun publishing quarterly certificate pricing data, adding a new dimension to cross-border component flows and encouraging suppliers and buyers alike to account for embedded emissions in sourcing decisions. In parallel, localized chip production initiatives in China and evolving manufacturing strategies among discrete device producers are creating ripple effects across commoditized and mid-tier component segments. These developments are not isolated events; they are structural inputs that influence lead time predictability, total cost of ownership, and supplier selection criteria.
What the Full Study Delivers: Turning Intelligence into Execution
Our comprehensive Electronic Components Market study is designed to move beyond headline forecasts and provide decision-makers with a structured, execution-ready intelligence framework. The report examines market size evolution across the historical baseline and the 2026–2032 forecast horizon, linking growth trajectories to demand intensity, component type dynamics, and application-specific adoption patterns. It maps the strategic positioning of leading manufacturers and distribution partners, highlighting portfolio focus, technology emphasis, and the competitive logic that shapes pricing power and customer retention.
Beyond competitive profiling, the study dissects the macro and micro forces currently driving the market: raw material and memory capacity conditions, lead time volatility, regulatory mechanisms such as carbon-related border measures, and the persistent importance of geographic manufacturing concentration. These dynamics are evaluated in the context of procurement risk, engineering design windows, and long-term supply continuity. The report also provides scenario-aware guidance for capacity planning, alternate sourcing strategies, and innovation timing, enabling teams to translate market signals into operational controls rather than reactive adjustments.
Importantly, the study deliberately avoids one-size-fits-all conclusions. Instead, it isolates where strategic leverage exists for different organizational roles: product strategy, supply chain resilience, regional sourcing, and technology investment. By connecting market size pathways with competitive behavior and operational constraints, the report gives leadership a coherent view of where margin protection, growth capture, and risk mitigation intersect.
Why This Research Matters Now
Market intelligence in the electronic components sector only creates value when it is precise enough to reshape decisions. The trajectory toward a 717 billion USD market by 2032 is not simply a validation of growth; it is a signal that competition for differentiated components, qualified supply relationships, and engineering bandwidth will intensify. Organizations that wait for quarterly updates to interpret structural shifts will find themselves reacting to conditions already priced into the market. Those that combine application-level foresight with disciplined sourcing and design strategy will be positioned to capture disproportionate value from the same environment.
The full research report expands on every dimension outlined here, delivering the detailed segmentation analysis, competitive benchmarking, dynamics assessment, and actionable strategic guidance necessary to support 2026 planning cycles and multi-year investment decisions. The complete dataset, scenario-based interpretation, and executive frameworks are available through the full market report. To access the complete intelligence suite and integrate it directly into your strategic planning, explore the full study at the source page.
Electronic Components Market
For detailed analysis of this topic, please visit the official page: Electronic Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Treadmill Market Hits $101M in 2025, Projects 6.8% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Outlook: The Treadmill Machines Market in 2026 and Beyond
The fitness equipment industry is currently navigating a complex landscape defined by post-pandemic habit stabilization, technological integration, and shifting supply chain dynamics. For stakeholders looking to capitalize on the upcoming fiscal years, understanding the trajectory of the treadmill segment is not merely about tracking sales figures—it is about recognizing where capital efficiency meets consumer behavior. This introduction outlines the strategic value of our latest comprehensive market research on the Treadmill Machines Market, designed to equip decision-makers with the intelligence needed to thrive between 2026 and 2032.
Macro-Economic Trajectory and Growth Signals
Our analysis begins with a clear view of the historical context and future potential. The market has demonstrated resilience and steady expansion over the last half-decade. In 2020, the global revenue base stood at approximately 80.0 million USD, a figure that has since catalyzed growth through 2025, reaching an estimated 101.0 million USD. This historical progression sets the stage for the forecast period, where the market is projected to ascend to 105.39 million USD in 2026 and continue its upward march toward 159.0 million USD by 2032.
Driving this expansion is a Compound Annual Growth Rate (CAGR) of 6.8 percent. For strategic planners, this rate indicates a mature yet vigorous sector where organic growth is sustained by consistent demand rather than speculative bubbles. However, the aggregate numbers only tell part of the story. The real value for corporate strategy lies in understanding the velocity of this growth across different vectors and the external pressures that might accelerate or decelerate these figures. Our report dissects these macro trends to reveal where the opportunities for margin expansion and market share acquisition truly reside.
Segmentation Dynamics: Residential Dominance and Functional Shifts
A critical component of our research involves the segmentation of the market by application and product type. The data indicates a pronounced preference for residential usage, which continues to command the lion's share of the market revenue. This dominance underscores the enduring shift toward home-based fitness solutions that began gaining momentum in previous years and has now settled into a stable equilibrium. For manufacturers and retailers, this suggests that product development strategies focused on home usability, noise reduction, and aesthetic integration remain high-priority investment areas.
Conversely, the commercial sector, while smaller in relative revenue contribution, represents a high-value niche with distinct operational requirements. The type segmentation further reveals a market heavily weighted toward single-function treadmills, though multifunctional units maintain a significant presence. The strategic implication here is nuanced. While single-function units drive volume, the multifunctional segment offers opportunities for premium pricing and deeper customer engagement through versatility. Our report delves into the specific drivers behind these splits without exposing the sensitive percentage breakdowns available in the full dataset, ensuring that clients who access the complete study gain a distinct informational advantage over competitors relying on surface-level industry summaries.
Regional Performance and Market Concentration
Geography plays a pivotal role in revenue distribution. North America remains a cornerstone of the industry, reflecting high disposable income levels and a deeply entrenched fitness culture. Europe and Asia Pacific also contribute substantial portions of the global revenue, each facing unique regulatory and economic environments that influence purchasing power and product specifications. The report provides a granular look at how these regional dynamics interact with supply chain logistics and local competition.
Market concentration is another vital metric for assessing risk and opportunity. The industry exhibits a moderate level of consolidation, with the top three players holding a significant portion of the market share and the top five commanding an even larger footprint. This concentration suggests that while there is room for agile newcomers, the incumbents possess substantial moats in terms of brand loyalty, distribution networks, and manufacturing scale. Understanding the exact concentration ratios and the specific revenue contributions of key regions is essential for entry strategy planning, details of which are preserved within the proprietary sections of our full study.
Competitive Landscape: Key Players and Strategic Moves
The competitive arena is populated by established entities with strong operational bases, primarily in the United States, alongside global innovators pushing the boundaries of connected fitness. Our report profiles several key companies that define the current standards of quality and innovation.
-
Life Fitness , based in Chicago, continues to set the benchmark for commercial and home equipment with its Club Series+ and Atmos models, catering to both high-traffic gyms and private residences.
-
TRUE Fitness , headquartered in St. Louis, stands as the largest privately-held U.S. producer. Their commercial-grade Launch and Stryker series are integral to many fitness facilities, emphasizing durability and performance.
-
SOLE Fitness , operating out of Salt Lake City, focuses on durability and value for home and light commercial users. Their F80, F85, and TT8 series are noted for lifetime warranties on key components, a strong differentiator in the residential segment.
-
Precor , from Bothell, specializes in the premium commercial tier. Their Breakaway slat-belt design is a hallmark feature for fitness facilities and health clubs seeking to reduce maintenance costs and enhance user experience.
-
NordicTrack , also based in Utah, dominates the high-performance home sector. Known for incline technology and interactive training, their X16 and Commercial 1750/2450 series appeal to users seeking gym-quality workouts at home.
-
Johnson Fitness & Wellness , located in Cottage Grove, serves as a retailer and provider leveraging its parent company Johnson Health Tech. Their Horizon Fitness subsidiary models cover both home and commercial applications, utilizing a broad distribution network.
Beyond the incumbents, the landscape is evolving through targeted product launches and strategic pivots. A notable recent development occurred in October 2025, when Peloton launched the Peloton Pro Series commercial equipment line, including the Tread+ Pro treadmill. This move targets hotels, residential gyms, and corporate wellness centers, signaling a convergence between high-end home tech and commercial durability. Such developments indicate that the boundaries between residential and commercial specifications are blurring, creating new cross-market opportunities that our report analyzes in depth.
Industry Dynamics: Regulatory, Supply Chain, and Spatial Constraints
External factors are increasingly dictating market behavior. In May 2025, the European Union approved new regulations on the energy efficiency of fitness equipment. The goal is to reduce energy consumption by 20 percent by 2030. This regulatory shift forces manufacturers to reconsider motor efficiency and standby power usage, potentially altering cost structures and product design priorities for any entity targeting the European market.
Supply chain volatility remains a persistent challenge. In June 2025, tariff increases on imported steel and aluminum spiked shipping costs for household appliances. This situation resulted in significant financial impacts, including a reported 250,000 USD overcharge fee paid by a U.S.-based fitness equipment maker for 1,000 treadmills and stationary bikes manufactured in China. Such incidents highlight the sensitivity of the market to raw material costs and trade policies, underscoring the need for diversified sourcing strategies or localized manufacturing considerations.
Furthermore, the physical reality of the product presents a barrier to entry for some consumers. High-quality treadmills require substantial dedicated floor space, a significant constraint for potential home users in smaller living spaces. This spatial requirement influences product design trends toward foldability and compact engineering, as well as marketing strategies that address urban housing limitations.
Technology and compliance are also intersecting. Connected fitness equipment manufacturers face increasing regulatory demands relating to cybersecurity and personal data protection for EU market access. This was demonstrated in February 2026 when Centr obtained the SGS RED Cybersecurity Certification. For market participants, compliance is no longer just a legal checkbox but a competitive differentiator that builds trust with privacy-conscious consumers and institutional buyers.
Operational Intelligence Within the Full Report
This overview serves as a primer to the comprehensive intelligence contained in our full market research publication. The complete document goes beyond these high-level trends to provide actionable frameworks for strategic planning. Readers who access the source material will find detailed breakdowns of market sizing across all forecast years, allowing for precise financial modeling and capacity planning.
The full study includes deep dives into the segmentation splits, offering clarity on how regional preferences and application needs diverge. It provides an exhaustive competitive profiling section that evaluates market positioning, product portfolios, and recent strategic maneuvers of key players. Additionally, the report contextualizes the industry dynamics within specific regional regulatory environments, helping compliance officers and product managers anticipate future constraints.
By securing access to the complete dataset, enterprises can benchmark their performance against market averages, identify white spaces for product innovation, and refine their go-to-market strategies in light of the 6.8 percent CAGR trajectory. The report is designed to function as a living document for strategy teams, supporting decisions ranging from capital expenditure on manufacturing lines to marketing spend allocation across digital and physical channels.
Treadmill Machines Market
Conclusion: Positioning for the 2026-2032 Cycle
The treadmill machines market is entering a phase where growth is predictable yet complex. The projected revenue climb to 159.0 million USD by 2032 offers a compelling value proposition for investors and operators, but realizing this potential requires navigating regulatory hurdles, supply chain instabilities, and shifting consumer spatial constraints. The insights provided in this introduction highlight the necessity of a data-backed approach to strategy.
Worldwide Low Speed Rehabilitation Treadmill Market
To leverage these insights fully and gain the competitive edge required for the 2026 fiscal year and beyond, stakeholders are encouraged to consult the complete market research report. The full version unlocks the specific regional percentages, detailed segmentation values, and granular competitive analysis necessary to transform broad market awareness into precise corporate action. In a market defined by concentration and consolidation, information remains the ultimate asset.
For detailed analysis of this topic, please visit the official page: Treadmill Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Form in Place Gaskets Market to Reach US$3.25B by 2032 with 6.98% CAGR
By pmarketresearch, 2026-09-15
Navigating the Form in Place Gaskets Market: Strategic Intelligence for 2026 Decision-Making
Market Trajectory and Macro Overview
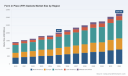
The Form in Place (FIP) Gaskets Market is entering a critical inflection point as it moves through the 2026-2032 forecast window. Analysis of historical performance from 2020 through 2025 reveals a consistent upward trajectory, with the global market expanding from approximately $1.41 billion to $2.025 billion over that five-year span. This growth reflects a compound annual growth rate that underscores sustained demand across industrial, electronics, and specialized engineering sectors.
Projecting forward, the market is expected to reach $2.18 billion in 2026 and climb steadily to $3.25 billion by 2032, maintaining a CAGR of 6.98% throughout the forecast period. This expansion is not merely a function of volume increase but signals deeper structural shifts in how manufacturers approach sealing, environmental protection, and electromagnetic interference (EMI) shielding. The market's evolution is being shaped by concurrent forces: supply chain restructuring, raw material cost volatility, accelerating adoption of automated dispensing technologies, and tightening performance requirements in semiconductor and automotive applications.
Strategic planners and procurement leaders must recognize that this market no longer operates as a commodity-driven segment. The convergence of material science innovation, precision manufacturing, and application-specific engineering has elevated FIP gaskets into a value-added solution space where performance differentiation, regulatory compliance, and supply reliability carry disproportionate weight. For organizations navigating 2026 investments, understanding these dynamics is not optional—it is foundational to capital allocation, vendor selection, and product roadmap planning.
Report Scope and Operational Intelligence
Our latest market research delivers a comprehensive, decision-ready analysis of the FIP gaskets market, structured to support cross-functional strategy teams. The report moves beyond headline figures to unpack the operational, competitive, and regulatory layers that define market behavior. Readers will find detailed breakdowns of market segmentation by type, application, and region, alongside deep dives into production methodologies, dispensing technologies, and cure-time optimization strategies that are reshaping manufacturing economics.
The study includes granular analysis of raw material cost structures, particularly silicone-based formulations and their derivatives, with tracking of price movements, supply constraints, and lead-time fluctuations that directly impact landed costs and production scheduling. We also examine the regulatory environment, including environmental compliance requirements, export control frameworks, and quality certification standards that influence sourcing decisions across different geographies.
Beyond market sizing, the report provides actionable intelligence on product innovation pipelines, including light-curable formulations, conductive elastomer advancements, and eco-friendly high-temperature material series. Each technology pathway is evaluated against adoption barriers, performance trade-offs, and integration requirements for assembly-line environments. This ensures that engineering, procurement, and product management teams can align their 2026 investment decisions with realistic assessments of technology readiness and supply availability.
Competitive Landscape and Strategic Positioning
The FIP gaskets market features a concentrated yet diverse competitive ecosystem. With a CR3 of 42% and CR5 of 51%, the market exhibits moderate concentration, indicating that while leading players hold meaningful share, there remains substantial room for specialized manufacturers, custom fabricators, and regional applicators to capture niche demand. This structure creates both opportunities and risks for organizations evaluating supply chain partnerships.
Parker Hannifin Corporation, headquartered in Cleveland, Ohio, continues to anchor its portfolio around conductive and non-conductive FIP gasket material series such as CHO-FORM and ParPHorm, targeting EMI shielding and environmental sealing applications. Their recent product launch in March 2025 introduced an eco-friendly high-temperature elastomer line tailored for offshore oil and gas environments, reflecting a strategic push into durability-focused, compliance-driven segments.
Laird Technologies, based in St. Louis, Missouri, emphasizes automated dispensing of conductive elastomer FIP gaskets for enclosure-level EMI shielding across electronics, automotive, and datacom applications. Their focus on process automation aligns with broader industry trends toward high-throughput, repeatable sealing solutions that reduce labor dependency and improve consistency in high-volume production.
Nolato Group, operating from Markaryd, Sweden, has built its reputation on the TriShield series of conductive silicone rubber FIP gaskets and associated dispensing technology for EMC shielding. Their approach integrates material formulation with application expertise, positioning them as a solutions provider rather than a commodity supplier.
Dymax Corporation, located in Torrington, Connecticut, differentiates through UV and LED light-curable FIP gasket formulations that cure in under 15 seconds, directly replacing slower traditional curing methods. This speed-to-cure advantage carries significant implications for cycle time reduction, throughput optimization, and floor-space efficiency in manufacturing environments.
Henkel AG & Co. KGaA, headquartered in Düsseldorf, Germany, focuses on 1K RTV silicone and related FIP gasket solutions designed for assembly-line dispensing and in-line curing. Their scale and formulation breadth support integration into automated production lines where consistency, shelf-life management, and curing predictability are critical.
Beyond these larger players, the market includes a network of specialized and custom-focused manufacturers. Sealing Devices Inc., based in Lancaster, New York, emphasizes custom fabrication for high-precision sealing applications and complex geometries. H&S Manufacturing Co. provides custom form-in-place liquid dispensing of high-performance silicone-based polymers for EMI shielding and complex gasket designs. Central Coating Technologies operates as a Nolato-approved applicator, delivering conductive and non-conductive FIP gaskets across a wide material range. KraFAB specializes in custom FIP gaskets using liquid dispensing for metal, glass, and substrate sealing, while Vactec Inc. combines precision dispensing technology with ISO 9001 and ITAR-compliant custom solutions. This ecosystem of specialized firms creates a tiered supply structure where organizations can match vendor capabilities to project complexity, compliance requirements, and volume profiles.
Form in Place (FIP) Gaskets Market
Market Dynamics: Supply Chain, Pricing, and Regulatory Pressures
The 2026 operating environment is being shaped by material cost movements and supply constraints that demand proactive procurement planning. Silicone pricing has shown regional divergence, with North American prices reaching approximately $6.18 per kilogram in May 2026, up 1.8% from the prior month, while European prices climbed to $7.98 per kilogram, reflecting a 1% monthly increase. These movements, while modest in isolation, compound when viewed alongside broader input-cost pressures and logistics variability.
More structurally significant is the 28% year-over-year increase in dimethyldichlorosilane prices during Q1 2026, driven by outages at Chinese chlor-alkali units. This upstream disruption has extended lead times for dimethyldichlorosilane and fumed silica from four weeks to twelve weeks in late 2025, creating scheduling uncertainty for manufacturers dependent on these inputs. Organizations that have not diversified sourcing, adjusted safety-stock parameters, or renegotiated delivery terms face heightened exposure to production delays and cost overruns.
Compounding these supply-side pressures, Wacker Chemie AG announced a mid-single-digit price increase for silicone-based products effective April 1, 2026, citing supply disruptions in the Middle East and higher energy tariffs in Europe. This development signals that raw material pricing is not only reacting to spot-market fluctuations but is also being reshaped by geopolitical supply routing and regional energy cost differentials. Procurement strategies that assume stable input pricing or rely on single-source supply chains will face increasing strain.
Regulatory and compliance considerations further complicate sourcing and product selection. Export control frameworks, quality management certifications, and environmental mandates influence which vendors can serve specific end markets and under what terms. For sectors such as defense, aerospace, and semiconductor manufacturing, compliance requirements are not peripheral—they are gatekeeping conditions that restrict vendor pools and elevate the importance of documented quality systems, traceability, and audit readiness.
Gasket and Seal Market
Strategic Implications for 2026 Decision-Making
The convergence of market growth, competitive differentiation, and supply-side volatility creates a clear imperative for structured market intelligence. Organizations operating in or dependent on FIP gaskets must evaluate their strategies across several interconnected dimensions.
- Supplier diversification and risk mitigation: With CR3/CR5 concentration and ongoing raw material constraints, over-reliance on a narrow vendor base increases vulnerability to price shocks, lead-time extensions, and capacity constraints. Strategic sourcing should map alternative suppliers, assess regional availability, and evaluate contractual flexibility.
- Technology and process alignment: Light-curable formulations, automated dispensing, and conductive elastomer innovations are not merely product upgrades—they are process enablers that affect cycle time, labor intensity, and quality consistency. Decision-makers should assess whether existing production lines can absorb these technologies and whether vendor support extends beyond material supply to process integration.
- Cost structure transparency: Regional silicone pricing divergence, upstream chemical price movements, and energy-related cost pressures require a more granular understanding of landed-cost drivers. Procurement teams should model sensitivity scenarios around key inputs and incorporate lead-time variability into inventory and scheduling plans.
- Compliance and qualification readiness: In regulated or export-controlled environments, vendor qualification is a strategic filter. Organizations should evaluate whether their supply base maintains the necessary certifications, documentation systems, and audit responsiveness to sustain uninterrupted sourcing.
- End-market demand signaling: Growth in semiconductor wafer manufacturing, IC packaging, automotive electronics, and specialized industrial applications is reshaping demand profiles. Understanding which applications are expanding, which are stabilizing, and which are facing substitution pressure helps prioritize internal resource allocation and vendor engagement.
These considerations are not isolated; they interact. A supplier selection decision that ignores lead-time risk may undermine production scheduling. A technology adoption choice that neglects compliance readiness may create bottlenecks in regulated markets. A procurement strategy that treats raw material pricing as static will misprice contracts and erode margin protection. The market's current dynamics reward organizations that integrate these dimensions into a coherent decision framework.
Why This Research Matters for 2026 Planning
Market intelligence in this space must be actionable, not descriptive. The report is structured to support strategic planning, procurement optimization, competitive benchmarking, and investment prioritization. It provides the context needed to interpret headline growth figures, the segmentation detail required to align with specific application or regional priorities, and the competitive analysis necessary to evaluate vendor capabilities against project requirements.
Readers will find analysis that connects market size evolution to underlying demand drivers, maps competitive positioning to technology and application focus areas, and translates raw material and regulatory developments into practical sourcing implications. The objective is to equip decision-makers with a clear view of where value is being created, where risk is accumulating, and where strategic options exist for 2026 and beyond.
For organizations that need to move from high-level awareness to detailed, segment-specific intelligence—including precise regional and application breakdowns, competitive financial and operational profiles, and scenario-based forecasting—the full report provides the depth required for execution-ready planning.
Next Steps for Decision-Makers
The FIP gaskets market is expanding in scale and complexity. Growth is real, but so are the pressures on supply reliability, input cost stability, and performance differentiation. Organizations that approach 2026 planning with a structured understanding of these forces will be better positioned to secure supply, optimize cost structures, and align technology adoption with operational realities.
To access the complete segmentation data, detailed competitive profiles, raw material tracking, and forecast scenarios that underpin this analysis, readers are encouraged to explore the full report. The complete research delivers the granularity and decision-grade detail necessary to translate market insight into concrete 2026 actions.
For detailed analysis of this topic, please visit the official page: Form in Place (FIP) Gaskets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Leather Goods Market Hits $363.2M in 2025, 7.2% CAGR to 2032
By pmarketresearch, 2026-09-15
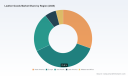
Strategic Outlook for the Global Leather Goods Market 2026-2032: Navigating Growth, Regulation, and Competitive Shifts
Introduction: The 2026 Inflection Point for Leather Goods Executives
The leather goods industry is entering a decisive phase of commercial expansion, operational restructuring, and regulatory recalibration. Executive teams across manufacturing, brand management, and distribution channels now face a landscape defined by resilient demand, evolving material preferences, and a tightening competitive perimeter. Our newly released Leather Goods Market research study offers a structured intelligence framework designed to support precise strategic planning, risk mitigation, and growth allocation for the 2026-2032 forecast horizon.
This report is not a static overview of historical performance. It is an operational reference tool for leadership teams that must decide where to commit capital, how to position product portfolios, and which partnership models will withstand shifting policy environments and material cost pressures. By integrating long-term market trajectory with granular analyses of segmentation dynamics, competitive positioning, and industry events, the study enables decision-makers to move beyond surface-level market narratives and into actionable strategic execution.
Macro Trajectory: A Market Built on Sustained Momentum
Over the 2020-2025 historical period, the global leather goods market demonstrated consistent expansion, with revenue reaching approximately 363.2 million USD in the base year. The growth path into 2026 and beyond reflects a market that is not merely recovering but compounding its structural advantages. Forecast modeling projects the market advancing toward 378.69 million USD in 2026, followed by a continued upward trajectory that carries revenue levels progressively higher across the remainder of the forecast window. By 2032, the market is positioned to reach an estimated 593.8 million USD.
Underlying this outlook is a compound annual growth rate of 7.2 percent across the forecast period, a figure that signals durable demand rather than temporary cyclical uplift. For executives, this kind of sustained CAGR has direct implications for capacity planning, inventory strategy, channel investment, and long-term brand positioning. It also reinforces the importance of forward-looking scenario modeling, particularly when regulatory and trade variables can alter the pace and geography of execution.
Importantly, the strategic relevance of this growth extends beyond the top-line trajectory. The market's expansion creates divergent opportunities across material types, product applications, and regional demand pockets, each with distinct margin profiles, sourcing requirements, and consumer resonance. Understanding where the highest-value opportunities concentrate, and how they interact with cost structures and compliance obligations, is central to capturing the market's upside without exposing the business to unnecessary operational risk.
Segmentation Architecture and Strategic Implications
One of the core strengths of this research is its disciplined segmentation design, which allows leadership teams to evaluate demand signals across the structural dimensions that shape procurement, product development, and market entry decisions. The analysis examines value distribution across material categories, application segments, and regional markets, providing a comparative lens for assessing where volume, premium positioning, and category expansion are evolving.
On the material side, the study evaluates the continuing relevance of genuine leather alongside the growing commercial footprint of synthetic and alternative material solutions. This comparison is critical for brands and manufacturers navigating consumer expectations around durability, aesthetics, sustainability, and price sensitivity. The report does not treat material choice as a static preference; instead, it frames material strategy as a dynamic component of portfolio architecture, influenced by sourcing availability, regulatory disclosure expectations, and shifting buyer perceptions.
Leather Market
Application-level analysis further sharpens strategic clarity by isolating demand patterns across major end-use categories. These include footwear, bags, and accessories, each of which presents distinct growth behavior, competitive intensity, and design-driven consumer demand. For product leaders, this breakdown supports more precise decisions about where to expand SKUs, how to prioritize design investment, and which categories may offer stronger resilience under changing macroeconomic conditions.
Geographically, the research maps regional market contributions to help executives assess where demand is most concentrated and where expansion may carry the greatest strategic payoff. Rather than describing the market as a uniform global entity, the study highlights how regional purchasing behavior, manufacturing ecosystems, and trade dynamics shape commercial opportunity. This regional perspective is especially valuable for companies evaluating sourcing reconfiguration, export exposure, and localized brand strategy in an environment where trade policy and logistics costs remain highly consequential.
Competitive Landscape: Differentiated Models in a Concentrated Market
The leather goods market is characterized by meaningful concentration among established players, alongside a broad field of specialized manufacturers and luxury-oriented houses competing on craftsmanship, vertical integration, and brand equity. The report examines this competitive architecture in depth, focusing on how leading firms differentiate themselves through product specialization, client relationships, material expertise, and geographic positioning.
A central theme in the competitive analysis is the coexistence of scale-oriented manufacturing and high-touch luxury production. Some companies compete by operating dedicated divisions that serve global fashion and lifestyle brands with handbags, wallets, and accessories, building long-term partnerships around consistency, volume capability, and design support. Others compete through OEM and ODM expertise, targeting premium handbags, backpacks, briefcases, belts, and related products with an emphasis on customization and technical execution.
At the premium end of the spectrum, the study evaluates firms whose commercial identity is anchored in craftsmanship, material provenance, and long durability commitments. These players often compete on vegetable-tanned materials, handmade construction, lifetime guarantees, and ultra-luxury travel or executive gear. Their strategic relevance lies not only in brand prestige, but in what they reveal about consumer willingness to pay for perceived authenticity, longevity, and material integrity.
The research also considers manufacturers that bridge B2B wholesale and private-label models, supplying fashion handbags and small leather goods to European and American brands. This segment underscores the importance of flexible production relationships and strong supply-chain credibility in markets where brand owners increasingly rely on specialized partners to manage design translation, production quality, and time-to-market.
Industry Events as Strategic Intelligence, Not Just Calendar Items
Trade fairs and product launches are often treated as industry noise, but in a market this dynamic, they function as leading indicators of sentiment, sourcing direction, and category innovation. The report integrates recent and upcoming events into its strategic context so that readers can interpret what major exhibitions and brand releases signal about the direction of demand and competition.
Recent activity shows continued emphasis on leather goods and fashion accessories at major international gatherings, with exhibitions bringing together suppliers, manufacturers, and buyers across material components, finished goods, and accessories. The upcoming 2026 event calendar reinforces this momentum, with multiple high-profile fairs scheduled across Europe, Asia, and the Middle East, each attracting hundreds of exhibitors and serving as focal points for sourcing relationships and product trends.
Equally telling are recent product launches from established retail and fashion names, including limited-edition leather jackets and handbags, as well as new timeless bag collections designed in one market and crafted in another using premium leather. These launches illustrate how brand strategy increasingly depends on material narrative, design authenticity, and cross-border craftsmanship. For competitive analysis, they also indicate where consumer-facing brands are placing their creative and commercial bets.
Regulatory and Cost Headwinds: The New Strategic Variables
Any realistic 2026 strategy must account for the fact that leather goods now operate within a more complex regulatory and cost environment than in previous growth cycles. The report devotes detailed attention to policy developments and input cost pressures that are reshaping sourcing decisions, product labeling practices, and market access.
One critical area is tariff exposure. Trade policy dynamics have added meaningful cost considerations for leather and allied product manufacturing, with average tariff impacts in key markets reaching levels that can influence export competitiveness and sourcing geography. For manufacturers and brand owners with cross-border supply chains, this is not simply a compliance issue; it is a strategic variable affecting product pricing, margin preservation, and the relative attractiveness of different production hubs.
Regulatory disclosure expectations are also tightening. Updated guidance in major consumer markets increasingly requires transparency around non-leather content in products that appear to be leather. This has direct implications for product claiming, packaging, and marketing language, especially for companies balancing genuine and alternative materials within the same portfolio. Failure to align product presentation with disclosure requirements can create both reputational and commercial risk.
In parallel, environmental policy developments are introducing new responsibilities for producers and brand operators. A proposed national extended producer responsibility framework in one of the major leather-producing economies signals a possible shift toward broader accountability for product lifecycles and end-of-life management. For industry participants, such developments point to a future where sustainability is not only a consumer-facing narrative but an operational and compliance consideration with potential cost and process implications.
Material cost pressure adds another layer of strategic urgency. Rising raw material costs have been identified as a headwind affecting profitability and planning, especially when combined with shifting consumer spending patterns. For executives, this reinforces the need to evaluate supplier diversification, product mix optimization, and price architecture with a greater degree of precision than in smoother cost environments.
Why This Research Is Built for Executive Decision-Making
The strategic value of this study lies in how it connects market structure to operational choice. It is designed to help leadership teams answer several questions that directly affect 2026 planning:
- Where is demand most likely to expand, and which product categories or material strategies align best with that expansion?
- How should companies interpret competitive concentration when deciding whether to compete on scale, craftsmanship, or specialization?
- Which sourcing and trade-policy risks are most material to margin and market access, and how should they be factored into sourcing strategy?
- What do recent trade fairs, brand launches, and industry developments reveal about near-term shifts in buyer expectations and supplier positioning?
- How should organizations prepare for regulatory disclosure and environmental accountability requirements without undermining product appeal or commercial agility?
To support these decisions, the report integrates market sizing and forecast data with segmentation analysis, competitive profiling, and contextual intelligence on events and regulatory developments. The result is a usable framework for portfolio strategy, market entry evaluation, supply-chain planning, and competitive positioning. It is built to reduce ambiguity in executive discussions and to give teams a shared basis for prioritizing investment and operational focus.
What the Full Report Unlocks
This article provides a strategic preview of the market environment and the decision context facing leather goods leaders in 2026. However, the complete research study goes further by offering the structured data, segmentation breakdowns, competitive profiles, and scenario-relevant analysis needed to turn strategic direction into execution. The full edition details market sizing across the historical and forecast timeline, segmentation dynamics across product type, application, and region, and a competitive assessment of the firms shaping today's supply and brand landscape. It also incorporates the latest trade fair signals, product-launch movements, and regulatory developments that are redefining operational risk and opportunity.
For decision-makers who need to translate market momentum into concrete strategy, the complete report delivers the depth required to act with confidence. It is designed to serve as a strategic reference for planning cycles, investment reviews, and competitive assessments throughout the 2026-2032 period.
Recommendation for Leadership Teams
If 2026 is treated as a tactical transition year, the leather goods market's growth trajectory and competitive intensity will likely outpace unprepared organizations. The companies that gain advantage will be those that use rigorous market intelligence to align product strategy, sourcing structure, compliance readiness, and brand positioning with the realities of a 7.2 percent growth environment and a more demanding regulatory landscape. This research study is built to support that decision-making process with professional depth, commercial relevance, and an executive-ready structure. For teams that require the full segmentation detail, competitive intelligence, and forward-looking context to guide their next strategic move, the complete market research report offers the comprehensive foundation needed to act decisively.
Leather Goods Market
For detailed analysis of this topic, please visit the official page: Leather Goods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: IPM Market Hits $3.8B in 2025, Projects 7.1% CAGR to $6.15B by 2032
By pmarketresearch, 2026-09-15
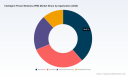
Navigating the Intelligent Power Module Landscape: Strategic Intelligence for the 2026 Market Cycle
The global market for Intelligent Power Modules (IPM) is entering a defining phase of expansion and technological renewal. As enterprises navigate shifting semiconductor supply chains, evolving application architectures, and intensifying regional competition, accessing precise, forward-looking intelligence is no longer a luxury—it is a strategic imperative. Our latest market research on the Intelligent Power Modules sector delivers exactly that: a rigorously modeled, commercially actionable view of where revenue is flowing, which architectures are gaining traction, and how the competitive field is reorganizing around the next generation of power integration. Drawing on historical tracking from 2020 through 2025 and a forecast horizon extending to 2032, this study translates volumetric growth into decision-grade frameworks designed specifically for corporate strategy, product planning, procurement, and investment teams operating in 2026.
Market Trajectory and the Macro Signals Shaping 2026 Decision-Making
The IPM sector has demonstrated consistent structural growth over the past half-decade, with global revenue tracking from approximately 2.7 billion USD in 2020 to an estimated 3.8 billion USD in 2025. That trajectory reflects more than cyclical recovery; it captures the deepening integration of intelligent power control into electrified transportation, industrial automation, renewable energy inverters, and compact consumer systems. The forecast period projects continued expansion, with market value expected to reach 4.02 billion USD in 2026 and advance toward 6.15 billion USD by 2032, corresponding to a compound annual growth rate of 7.1 percent across the forecast window.
Intelligent Power Modules (IPM) Market
These headline figures function as a strategic baseline rather than a final destination. For executive teams evaluating capacity commitments, product roadmaps, or supply-chain design, the real value lies in understanding the inflection mechanics that drive the curve: the pace at which alternative semiconductor architectures displace legacy configurations, the timing of adoption thresholds across end-use sectors, and the way regional deployment patterns reshape component sourcing strategies. Our analysis isolates these drivers so that leaders can anticipate demand shifts rather than react to them, aligning investment horizons with the growth vectors that will define the late 2020s.
Competitive Architecture and the Reconfiguration of Market Leadership
IPM market leadership is no longer determined solely by scale. It is increasingly defined by the ability to combine power semiconductor performance, driver integration, protection logic, and packaging efficiency into application-specific solutions. The competitive field is concentrated among a cohort of specialized and diversified semiconductor manufacturers, each pursuing distinct technology pathways and vertical strategies. STMicroelectronics continues to anchor its IPM portfolio in integrated power modules with IGBT and MOSFET drivers alongside built-in protection, targeting industrial and automotive motor control where reliability and functional integration carry premium value. Infineon Technologies AG has expanded its CIPOS portfolio into high-integration modules designed for motor drives, electric vehicle traction architectures, and renewable energy systems, emphasizing system-level efficiency and broad platform coverage.
Japanese manufacturers command a substantial share of innovation activity tied to packaging, material advances, and application-specific form factors. Mitsubishi Electric Corporation has pushed toward compact DIPIPM series and silicon-carbide-based IPMs for packaged air conditioners, heat pumps, and industrial inverters, a direction reinforced by recent sample shipments of a compact series leveraging RC-IGBTs and achieving a markedly smaller footprint for climate-control applications. Renesas Electronics Corporation maintains a focused position in embedded-control IPMs with integrated drivers for industrial and automotive use, aligning power integration with microcontroller architectures. Fuji Electric’s seventh-generation X Series IGBT IPMs target high-efficiency production equipment and energy-saving inverters, while ROHM Semiconductor is advancing gallium-nitride and silicon-carbide IPMs for high-efficiency compact inverters and motor drives. Toshiba Electronic Devices and Storage Corporation contributes to the landscape through SiC and IGBT IPMs designed for high-voltage industrial and automotive drives.
Europe remains a strategically important center for high-reliability and system-oriented IPM innovation. Semikron Danfoss GmbH and Co. KG provides high-reliability power modules for industrial automation, EV applications, and renewable energy drives, while NXP Semiconductors serves industrial and consumer motor control with power-management-oriented IPM solutions. In North America, Texas Instruments has emphasized isolated power modules and integrated solutions for data centers, electric vehicles, and industrial systems. ON Semiconductor Corporation has moved aggressively into wide-bandgap integration, introducing EliteSiC SPM series and GaN IPMs for HVAC systems, data-center drives, and e-mobility platforms, including a recently introduced 1200 V SiC MOSFET-based series intended to reduce system cost for HVAC and data-center drives. Wolfspeed continues to concentrate on SiC-based IPMs for e-mobility propulsion and high-efficiency inverters. Alpha and Omega Semiconductor Limited has pursued a highly practical, value-driven product cadence, launching the Mega IPM-7 series for brushless DC motor drives and commencing high-volume production of its IPM5 series, which integrates a substantial die count, at an outsourced packaging facility. Additional specialists such as Sensitron Semiconductor extend the competitive map into radiation-tolerant and high-reliability applications for space and industrial environments.
Together, these players illustrate a market in which differentiation is emerging from three intersecting axes: material technology transitions across IGBT, MOSFET, and wide-bandgap platforms; mechanical and electrical integration for size and efficiency targets; and vertical alignment with end-market reliability, thermal, and cost requirements. The intelligence embedded in our report unpacks these competitive vectors in detail, mapping how each design philosophy maps to revenue opportunity and risk exposure.
Technology Transitions, Supply Dynamics, and the Real Cost of Forecasting Errors
No IPM strategy for 2026 can be built on product roadmaps alone. Material availability, substrate constraints, and geopolitical frictions are actively reshaping lead times and platform timing. Throughout 2025, silicon-carbide wafer supply constraints drove lead times for 1200 V dies toward 26 weeks, causing some OEMs to postpone platform launches by as much as six months. At the same time, shortages of advanced substrates used in IPM manufacturing extended component lead times beyond 16 weeks, introducing design delays for EV and grid-related OEMs. Volatility in silicon wafers and aluminum-nitride substrates has similarly pushed module lead times past the 16-week threshold, compounding scheduling risk across multiple application segments.
These supply-side pressures intersect with an increasingly complex regulatory environment. Export controls on gallium and related critical minerals introduced in mid-2025 have created new exposure for GaN and SiC substrates used in IPM production, while broader trade restrictions and geopolitical tensions have added uncertainty to logistics and customs clearance within IPM supply chains. The practical implication for corporate planners is clear: model assumptions that ignore material bottlenecks and regional trade friction will systematically underestimate time-to-market risk and overstate near-term flexibility.
Our research integrates these dynamics into a structured view of market behavior, enabling decision-makers to test portfolio resilience under realistic supply scenarios. Rather than treating lead-time volatility as a peripheral procurement concern, the analysis positions it as a primary variable in revenue timing, model selection, and supplier negotiation strategy.
Scope, Structure, and the Operational Breadth of the Report
The study is built to support cross-functional execution rather than to remain an abstract market narrative. It opens with a rigorous quantification of market size and growth across the historical and forecast periods, establishing a shared baseline for commercial planning. From there, the analysis decomposes demand across technology families, application domains, and geographic regions, while deliberately preserving the granularity that product managers, sourcing leaders, and strategy teams need to make specific commitments.
Readers will find detailed assessments of technology transition dynamics, including the economic and performance trade-offs that determine when IGBT, MOSFET, and silicon-carbide or gallium-nitride alternatives become strategically preferable in specific use cases. The report also examines application-side adoption patterns, tracking how motor control requirements, efficiency targets, thermal constraints, and packaging trends are accelerating or delaying IPM integration across transportation, industrial equipment, consumer electronics, and renewable energy systems. Regional deployment characteristics are analyzed to inform sourcing diversification, capacity planning, and market-entry sequencing without reducing the picture to simplistic regional rankings.
In parallel, the report delivers a company-level competitive assessment that goes beyond public positioning statements. It evaluates how each major participant’s product families map to application needs, where integration depth creates defensibility, and how recent product launches and shipment milestones alter near-term competitive pressure. Recent developments—such as compact DIPIPM sampling for climate-control applications, wide-bandgap IPM introductions targeting cost-sensitive HVAC and data-center drives, high-volume production ramp-ups for integrated IPM platforms, and new compact BLDC-oriented product lines—are contextualized within broader technology adoption cycles so that teams can distinguish transient news from structural momentum.
Additional sections address market concentration dynamics, pricing behavior, packaging and integration trends, and the procurement implications of substrate and wafer availability. The objective is to convert market intelligence into an operational reference that procurement can use for negotiation timing, engineering can use for architecture selection, and strategy teams can use for portfolio prioritization.
Where to Place Strategic Attention in 2026
For organizations operating in or adjacent to the IPM ecosystem, 2026 is a year in which tactical assumptions can quickly become outdated. The convergence of technology transitions, supply fragility, and regional regulatory variability means that advantage will accrue to teams who can distinguish durable demand from short-term noise. Several actionable priorities emerge from the broader landscape:
-
Prioritize technology roadmapping that aligns power semiconductor selection with application-specific efficiency, thermal, and cost targets rather than defaulting to legacy architectures simply because they are established.
-
Stress-test sourcing plans against substrate and wafer lead-time scenarios, especially for wide-bandgap devices where availability constraints can cascade into platform timing.
-
Treat competitive intelligence as a moving target: monitor product cadence, packaging innovation, and integration depth as leading indicators of where market share will migrate.
-
Incorporate regulatory and materials-export risk into regional planning, particularly where GaN and SiC supply chains intersect with critical-mineral controls and trade friction.
The study is designed to support exactly this kind of integrated decision-making. It gives leadership a defensible view of market size, growth velocity, competitive positioning, and risk exposure, while preserving the segment-level clarity necessary for execution teams to act with confidence.
Why the Complete Report Matters for Enterprise Decision-Makers
Market summaries can indicate direction, but they rarely provide the precision required to commit capital, redesign architectures, or renegotiate supply agreements. The full report supplies the missing layer: segment-level quantification, technology-specific adoption trajectories, regional deployment patterns, company positioning with product-level context, and scenario-aware guidance derived from current supply-chain stress points. It is structured so that strategy, R&D, procurement, and investor teams can extract the same underlying intelligence through different lenses without compromising analytical consistency.
Intelligent Power Module Board Market
Most importantly, the report is built to remain relevant beyond a single planning cycle. By combining historical validation, a clearly defined forecast window, and a disciplined focus on the operational drivers of growth, it offers an enduring reference for tracking how the IPM market evolves as electrification, automation, and efficiency mandates continue to spread across industrial and consumer systems.
For executives and analysts who require complete segment-level intelligence—rather than directional headlines—the full report delivers the detail, structure, and strategic framing needed to make informed decisions throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Intelligent Power Modules (IPM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oral Mucositis Drug Market Hits $159.4 Million in 2025, Poised for 7.38% CAGR Through 2032
By pmarketresearch, 2026-09-15
Beyond Symptom Management: Strategic Intelligence for the Oral Mucositis Drugs Market (2026-2032)
The Shifting Landscape of Supportive Oncology Care
Oral mucositis remains one of the most debilitating and dose-limiting side effects of cancer therapy. As oncology increasingly adopts aggressive multi-modal regimens and expands into earlier disease stages, the demand for effective mucositis management has never been more critical. For pharmaceutical executives, investors, and healthcare strategists, the oral mucositis drugs market represents far more than a niche supportive care segment; it is a rapidly evolving commercial space shaped by regulatory shifts, unmet clinical needs, and a growing array of localized treatment modalities. Our latest comprehensive market intelligence study provides decision-makers with the analytical scaffolding required to navigate this space through 2032.
Drawing on historical performance from 2020 through 2025 and projecting forward across the 2026-2023 forecast horizon, the analysis reveals a market that has consistently compounded its value as clinicians and drug developers respond to persistent gaps in standard care. The total market revenue climbed from approximately USD 111.3 billion in 2020 to roughly USD 159.4 billion by 2025, reflecting sustained investment in both pharmaceutical and device-based interventions. Looking ahead, the market is forecasted to expand further, reaching more than USD 169 billion in 2026 and projected to cross USD 263 billion by 2032, underpinned by a steady annualized growth trajectory of 7.38%. These figures are not abstract milestones; they signal structural demand that will directly influence formulary positioning, R&D prioritization, and commercial partnerships in the years ahead.
Why These Projections Matter for 2026 Strategic Planning
The narrative behind the numbers is where executive strategy truly converges. Every percentage point of growth reflects clinical realities: the expanding use of myeloablative conditioning, the iterative refinement of targeted radiotherapy protocols, and the persistent search for better-tolerated alternatives to systemic analgesics. As payers tighten coverage around opioid-sparing protocols and regulatory agencies accelerate breakthrough and fast-track pathways, companies that understand the underlying revenue architecture of this market will be better positioned to time product launches, negotiate pricing, and secure reimbursement pathways.
Our research is designed to translate macro growth trajectories into actionable intelligence. By dissecting the commercial value tied to distinct clinical drivers and intervention categories, the report enables strategists to evaluate which therapeutic angles hold the most commercial momentum and where competitive intensity is likely to concentrate. Rather than offering static snapshots, the analysis maps how revenue streams are distributed across chemotherapy-induced, radiotherapy-induced, and hematopoietic stem cell transplantation-related contexts, as well as how they align with pain control pharmacotherapies, mucosal rinses and wash therapies, and emerging adjunctive approaches. This structure allows clients to stress-test product pipelines against real-world utilization patterns and forecast which segments will absorb incremental investment with the highest risk-adjusted returns.
Inside the Research: Executive Frameworks for Commercial Decision-Making
The report is engineered for cross-functional application. Clinical strategy teams, market access professionals, and corporate development units will find layered breakdowns that connect scientific rationale to commercial viability. Each section moves beyond descriptive commentary to deliver structured analytical outputs, including:
Oral Mucositis Drugs Market
- Demand attribution by clinical trigger , mapping how the revenue base segments across chemotherapy, radiation therapy, and stem cell transplantation pathways, with contextual insight into how regimen intensity and patient population dynamics drive utilization patterns.
- Therapeutic modality valuation , examining how revenue splits across conventional pain control pharmacologies, topical rinse and wash formulations, and alternative supportive interventions, helping stakeholders assess competitive positioning and white-space opportunities within the current treatment algorithm.
- Competitive footprint and concentration metrics , quantifying market share dispersion among leading players to reveal consolidation dynamics, barriers to entry, and the strategic implications of a partially concentrated landscape where a handful of firms command disproportionate influence over prescribing behaviors and distribution channels.
- Pipeline and regulatory intelligence , integrating recent clinical trial milestones, regulatory designations, and partnership developments that are reshaping the innovation curve and signaling which entrants may disrupt incumbent positioning over the forecast period.
- Supply chain and access constraints , capturing structural bottlenecks, raw material availability, and reimbursement realities that can alter commercialization timelines and affect the speed-to-market for both branded and generic entrants.
Together, these components form a decision-grade reference architecture rather than a single-point forecast. Clients can use the report to benchmark internal market assumptions, calibrate investment scenarios, and prepare for regulatory or reimbursement events that may compress or expand profitable windows of opportunity.
Competitive Architecture: Leaders, Entrants, and Strategic Wedges
The current commercial ecosystem is defined by a blend of established specialty brands, device-oriented innovators, and regional players pursuing differentiated mechanisms of action. At the center of the branded pharmaceutical space sits Amgen Inc., whose commercialization of Kepivance (palifermin) has long anchored the standard of care for severe oral mucositis in patients undergoing autologous hematopoietic stem cell transplantation. The FDA approval of palifermin in December 2004 established a rare example of a drug specifically indicated to reduce both the incidence and duration of severe mucosal injury, giving Amgen a durable regulatory anchor in a niche where therapeutic specificity commands premium positioning. The company's profile underscores a fundamental strategic question for the market: how long can a single-indication biologic preserve its leadership as alternative mechanisms and localized therapies continue to mature?
Parallel to pharmacologic approaches, device-based and mechanical-action solutions are carving out meaningful commercial territory. Jaguar Health, Inc., operating through its subsidiary Napo Pharmaceuticals, commercializes Gelclair, a mechanical-action gel that adheres to the mucosal surface to manage pain and provide temporary relief. The value proposition here is mechanistic: rather than relying solely on systemic or topical pharmacological activity, the product modulates the local environment to protect ulcerated tissue. ChemoMouthpiece, LLC extends this device-driven logic into preventive care with an FDA-cleared oral cryotherapy device designed to reduce the incidence and severity of chemotherapy-induced mucositis. In August 2025, the company published peer-reviewed results from a multi-center randomized controlled trial demonstrating a significant reduction in oral pain and decreased reliance on opioids and analgesics during chemotherapy. That clinical signal, combined with InfuSystem Holdings Inc.'s nationwide distribution and service infrastructure for the device, illustrates how complementary commercial ecosystems can accelerate adoption in cancer centers even when the underlying technology remains relatively straightforward.
Meanwhile, a newer cohort of innovators is targeting the pain-relief gap with localized, non-opioid formulations. OncoZenge AB has positioned BupiZenge, a bupivacaine-containing lozenge for local pain management, as its lead candidate. The strategic significance of this program was reinforced throughout 2025: the company secured approval to initiate the pivotal Phase III 'BEAM-Pain' trial in January, filed a PCT patent application for the lozenge formulation that same month, and signed a non-binding agreement with Molteni Farmaceutici in September to secure exclusive commercialization rights for BupiZenge in Europe. This three-part sequence—clinical advancement, intellectual property protection, and regional partnership architecture—is a textbook example of how development-stage companies are structuring go-to-market readiness in a space where regulatory differentiation and access to established distribution networks can be decisive.
Regional and value-oriented players are also reshaping commercial dynamics. Shilpa Medicare Limited has launched ORAAL, a naturally derived oral spray marketed for rapid pain relief and wound healing in oral mucositis patients. The emergence of naturally derived formulations reflects a broader trend toward patient-preferred delivery formats and adjunctive comfort solutions, even as payers and clinicians increasingly demand robust comparative evidence. Collectively, these companies span the full commercialization spectrum: from late-stage branded assets and cleared devices to early-phase pipeline candidates and regionally scaled specialty products, each pursuing a distinct route to share in the growing revenue base.
Market Dynamics as Strategic Inflection Points
The commercial opportunity cannot be fully interpreted without accounting for the structural dynamics that shape availability, reimbursement, and clinical adoption. Regulatory history provides one important anchor: the FDA's long-standing approval of Kepivance for bone marrow transplant-associated severe mucositis gave clinicians an early mechanistic option, yet the broader therapeutic landscape still reflects meaningful unmet need. Notably, there remains no FDA-approved systemic drug specifically indicated for severe oral mucositis associated with chemotherapy or radiation in head and neck cancer patients. That gap has incentivized a wave of investigational efforts, including the FDA's fast-track designation granted to RRx-001 for the prevention and attenuation of severe oral mucositis in head and neck cancer patients undergoing chemotherapy and radiation.
Supply-side realities add another layer of complexity. Regulatory and public health authorities have reported ongoing global shortages of Beriglobin, a blood product used in the treatment of radiation-induced oral mucositis. Shortages of supportive care inputs can create localized access volatility, influence off-label substitution patterns, and shift clinician preference toward alternative modalities that are less exposed to supply disruption. For commercial teams, these dynamics are not peripheral; they directly affect planning assumptions for launch sequencing, inventory strategy, and the timing of evidence generation.
The distribution of market influence also matters. A moderately concentrated competitive base indicates that while large specialty assets and established device programs exert significant pull on clinical practice, fragmentation in adjacent segments leaves room for targeted entrants with defensible mechanisms. High concentration at the top of the ranking often correlates with formulary entrenchment and reliance on clinical familiarity, whereas lower concentration among secondary participants suggests multiple opportunities to differentiate on pain management efficacy, ease of administration, or regional access advantages. The interaction between these concentration tiers will shape pricing power, partnership leverage, and the pace at which next-generation innovations can displace entrenched approaches.
Drugs for Herpes Labialis (Oral Herpes) Market
Using This Intelligence to De-Risk 2026 Decisions
Strategic planning for the oral mucositis market must balance optimism about growth with realism about clinical and regulatory complexity. The market's expansion from roughly USD 159.4 billion in 2025 toward a projected USD 263.1 billion by 2032 is strong enough to justify serious portfolio attention, but the distribution of that growth across causes, modalities, and geographies is what ultimately determines commercial success. Companies that treat the segment as a single homogeneous opportunity risk misallocating resources; those that can operationalize segment-level intelligence will be better equipped to choose where to compete, how to differentiate, and which partnerships will accelerate uptake.
This research report is built to support precisely that level of decision-making. It translates historical performance and forward forecasts into a structured reference for scenario modeling, competitive positioning, and commercialization roadmapping. By integrating pipeline developments, regulatory signals, access constraints, and concentration dynamics, the analysis equips executive teams with a common language for evaluating risk and opportunity across the full spectrum of oral mucositis interventions. The macro trajectory may be compelling, but the real value lies in understanding how that trajectory breaks down into actionable commercial logic.
For leaders preparing for critical 2026 decisions—whether related to pipeline prioritization, market entry timing, partnership structuring, or reimbursement strategy—the complete study provides the segmented segmentation detail, competitive scenarios, and analytical depth required to move from general market awareness to precise strategic execution. Access the full research for the granular breakdowns, regional momentum patterns, modality-level revenue shares, and competitor-specific positioning that will allow your team to convert broad market growth into a targeted competitive plan.
For detailed analysis of this topic, please visit the official page: Oral Mucositis Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Data Center Construction Market to Hit $442.64B by 2032, Growing at 6.4% CAGR
By pmarketresearch, 2026-09-15
Navigating the Data Center Construction Surge: A Strategic Imperative for 2026
The global infrastructure landscape is undergoing a structural transformation that cannot be ignored. Driven by exponential data growth and the rapid deployment of artificial intelligence workloads, the construction of data centers has evolved from a specialized niche into a macroeconomic force. For enterprise leaders, investors, and real estate strategists, the question is no longer whether to engage with this sector, but how to navigate its accelerating complexity with precision. PW Consulting presents our latest comprehensive analysis, the Data Center Construction Market study, designed to equip decision-makers with the actionable intelligence required to thrive in 2026 and the subsequent forecasting window through 2032.
The Scale of Transformation: From Recovery to Accelerating Growth
The market trajectory over the past half-decade tells a story of resilience followed by rapid acceleration. Following a measured expansion through the early twenty-twenties, the sector experienced a notable inflection point that pushed overall market size toward 288.34 Billion in the base year of 2025. This surge reflects a broader realignment of capital toward digital infrastructure, as organizations recognize that compute capacity is now a primary driver of competitive advantage and operational continuity.
Looking ahead, our forecasts indicate sustained momentum. The market is projected to reach 307.46 Billion in 2026, with a clear upward trajectory continuing through the end of the decade and into the early twenty-thirties. By 2032, total market valuation is expected to approach 442.64 Billion. This expansion path is underpinned by a compound annual growth rate of 6.4 percent across the forecast period from 2026 to 2032. Such figures are not merely statistical markers; they represent the compounding effect of hyperscale campus expansions, enterprise digitalization mandates, and colocation demand reshaping commercial real estate priorities. Understanding how this growth distributes across project types, geographic footprints, and deployment models is essential for allocating capital efficiently, and this is precisely where deep-dive segmentation analysis becomes indispensable.
Beyond Headline Figures: The Operational Complexity of Modern Build-Outs
Constructing a modern data center is fundamentally different from traditional commercial development. The integration of high-density power distribution, advanced thermal management systems, and redundant mechanical infrastructure demands a level of engineering coordination that leaves little room for conventional procurement delays. Project timelines are increasingly compressed by competitive pressure and utility interconnection queues, while simultaneously being stretched by supply chain volatility and evolving regulatory expectations.
Our research dissects these operational realities by examining the interplay across electrical infrastructure, mechanical infrastructure, and general construction disciplines. Each segment carries its own procurement constraints, labor skill requirements, and technology adoption curves. The report evaluates how these components converge in practice, highlighting where bottlenecks form, where value engineering can yield meaningful savings, and where accelerated permitting strategies can protect critical path schedules. Rather than treating these elements as isolated line items, our analysis maps them against real-world project delivery models, offering practitioners a framework to anticipate friction before it impacts budget or timeline.
Data Center Consulting Services Market
Competitive Positioning and the Consolidation of Specialized Expertise
The competitive landscape in this sector is characterized by a concentrated group of established players who have invested heavily in mission-critical delivery capabilities. The market exhibits meaningful concentration, with leading firms commanding a dominant share of large-scale deployments. This structure rewards organizations that can demonstrate proven execution across multiple continents, maintain rigorous quality controls under aggressive timelines, and navigate the intersection of utility coordination, environmental compliance, and advanced construction methodologies.
Firms such as Fluor Corporation and AECOM have long anchored the market through full-scale engineering, design, and construction delivery spanning hyperscale campuses and enterprise facilities worldwide. Turner Construction Company brings deep experience in executing large-scale build-outs for hyperscale operators and colocation providers, while DPR Construction has carved a distinct position by specializing in mission-critical environments and preconstruction services tailored to AI-ready facilities. These capabilities reflect a broader industry shift: prime contractors are increasingly expected to function as integrated solution providers rather than traditional general contractors.
Other organizations are advancing complementary strengths. Holder Construction emphasizes efficiency-driven execution and advanced mechanical and electrical systems integration. HITT Contracting delivers general contracting and build services aligned with high-density AI infrastructure demands. Clayco differentiates itself through modular construction approaches and sustainable design methodologies, while Mortenson focuses on hyperscale campus delivery with embedded sustainability and power solutions. Brasfield & Gorrie supports enterprise and cloud providers with construction and commissioning expertise, and Equans extends its footprint through international construction and facility management capabilities. Together, these players illustrate a market where specialization, regional presence, and technical versatility determine competitive advantage.
Regulatory and Cost Dynamics Defining the 2026 Environment
Decision-makers entering 2026 must operate within a rapidly shifting policy and cost environment. Federal and state-level actions are reshaping how and where projects move forward, while material economics continue to pressure project budgets.
At the federal level, an executive order issued in mid-2025 accelerated the permitting pathway for data center infrastructure by streamlining environmental reviews and introducing financial incentives for qualifying projects. A subsequent agreement in early 2026 saw major developers commit to a Ratepayer Protection Pledge, agreeing to fully cover the costs of new electric generation resources supporting their facilities. These developments signal a growing expectation that large-scale infrastructure providers will internalize external costs, a principle that is also reflected in legislative activity across more than twenty-seven states requiring developers to shoulder the full cost of new energy infrastructure.
Meanwhile, cost pressures are intensifying on multiple fronts. A prominent industry cost index released in late 2025 documented elevated material and labor expenses driven by sustained AI-related demand. Upstream commodity dynamics have compounded this challenge, with producer price indices for industrial chemicals rising sharply in early 2026, directly affecting materials used in construction and systems integration. Compounding these supply-side headwinds, trade exposures on steel, aluminum, and copper have increased construction material cost sensitivity for data center projects by roughly ten to fifteen percent. Navigating these pressures requires procurement strategies that are forward-looking rather than reactive.
Data Center Construction Market
Regional Dynamics and the Energy Infrastructure Equation
Regional considerations now play an outsized role in project viability. Market participants must evaluate interconnection capacity, local regulatory frameworks, and utility pricing structures with greater rigor than ever before. In key power markets, transmission and capacity pricing have experienced dramatic adjustments, with some regional capacity markets seeing pricing shifts driven by hyperscale demand intensity. These changes directly influence total cost of ownership, site selection logic, and the timeline required to secure power commitments.
Concurrent regulatory evolution adds another layer of operational complexity. For instance, updated building energy efficiency standards in certain major states, effective from early 2026, impose stricter compliance requirements on cooling and electrical systems. Simultaneously, accelerated federal environmental review timelines for larger load facilities are creating new opportunities to compress permitting cycles for qualifying projects. These competing forces, faster approvals on one hand and stricter technical compliance on the other, demand a nuanced strategy that balances speed with compliance risk management. Our report examines how these regional and regulatory dynamics interact across key markets without reducing the analysis to simplistic geographic rankings, instead focusing on the structural factors that determine where and how projects can be delivered profitably.
How This Research Supports Executive Decision-Making
This study is structured to support real-world decisions rather than theoretical exploration. The report integrates historical performance data with forward-looking modeling to help organizations stress-test assumptions around budget allocation, procurement timing, and market entry strategies. It examines the relationship between infrastructure segment choices and project-level execution risk, providing a basis for more accurate forecasting and more resilient contracting strategies.
Readers will find detailed coverage of how different application models, hyperscale, colocation, and enterprise deployments, shape demand patterns, investment priorities, and delivery expectations. The analysis also explores how leading contractors structure their service offerings, where differentiation has become most valuable, and how market concentration influences bid dynamics and partnership opportunities. By aligning these insights with cost trends, regulatory milestones, and regional power market developments, the report provides a cohesive framework for evaluating risk and identifying actionable opportunities.
Strategic Takeaways for the Months Ahead
As organizations prepare their capital plans and long-term infrastructure roadmaps, several priorities come into focus. First, procurement and contracting strategies must account for sustained material cost volatility and the compounding effects of trade-related exposures. Second, engagement with energy infrastructure, from generation cost commitments to interconnection lead times, must be integrated into site selection and feasibility assessments rather than treated as a downstream utility issue. Third, firms should evaluate partnership and contracting options against a market where top-tier delivery capabilities remain concentrated, making selective collaboration and vendor qualification increasingly important. Fourth, regulatory compliance, spanning energy efficiency standards and evolving state-level cost responsibility mandates, must be embedded into project design and scheduling from the outset.
Accessing the Full Strategic Outlook
The data points highlighted here reflect only a portion of the intelligence embedded in the complete study. The full report provides granular segmentation analysis, detailed regional evaluations, and comprehensive assessments of competitive positioning that cannot be summarized in a single overview. For executives, development teams, and investment strategists seeking to align their decisions with the realities of a 442.64 Billion market trajectory by 2032, the complete research offers the depth required to move from awareness to execution. We invite you to explore the full dataset and analysis to secure the complete strategic picture for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Data Center Construction Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com