

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Spray Dryer Market Hits $6.59B in 2025, Projects 6.51% CAGR Through 2032
By pmarketresearch, 2026-09-15
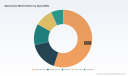
Navigating the Spray Drying Landscape: Strategic Imperatives for 2026 and Beyond
The global spray dryer market is entering a phase of disciplined expansion. Between 2020 and 2025, industry valuations climbed from 4,617.0 million USD to 6,590.0 million USD, reflecting a compound annual growth rate of 6.51 percent across the forecast horizon extending to 2032. This trajectory is not merely a function of incremental demand. It signals a structural recalibration of how powdered intermediates, active ingredients, and consumer-ready formulations are engineered, scaled, and commercialized. For executives mapping capital allocation, product roadmaps, and supply chain resilience in 2026, understanding the operational and regulatory forces shaping atomization technology has shifted from a technical consideration to a board-level priority.
The Trajectory: From Recovery to Sustained Expansion
The historical record from 2020 through 2025 demonstrates how quickly industrial and consumer-facing sectors can amplify throughput when formulation economics favor dry powder architectures. After a 2021 peak, the market experienced a brief contraction in 2022 before resuming a steady upward path, culminating in an estimated valuation above the 6,000 million USD threshold. The forward projection maintains this momentum, with valuations anticipated to surpass the 10,000 million USD mark by the early 2030s. This expansion is anchored in three interconnected drivers: the migration of traditional liquid or slurry processes toward powder-based formats, the integration of precision drying into continuous manufacturing pipelines, and the increasing requirement for batch-to-batch reproducibility in highly regulated categories. Companies that rely on legacy single-stage drying or outsourced powder conversion are finding that capital efficiency, shelf-stability requirements, and cold-chain compression are collectively pulling atomization capabilities inward, closer to the formulation stage.
Yet the headline trajectory only tells part of the story. The operational reality of spray drying remains heavily influenced by energy intensity, capital expenditure cycles, and the specialized labor required to maintain sanitary and process-valid conditions. Large-scale industrial units routinely involve multi-million-dollar investments, and the ongoing operational profile demands trained personnel for routine maintenance, cleaning protocols, and sanitation routines. These structural cost dynamics mean that capacity decisions cannot be decoupled from efficiency modeling, utility pricing, and the long-term total cost of ownership. Executives evaluating expansion or retrofit programs must weigh not only throughput ceilings but also the operational discipline required to sustain them. The market’s growth is real, but it rewards disciplined engineering rather than speculative overbuilding.
Competitive Architecture and Strategic Positioning
The competitive landscape is characterized by a high degree of consolidation among tier-one suppliers. The top three firms collectively command an estimated 68.5 percent of market share, while the leading five players extend that influence to 78.2 percent. This concentration indicates that scale, engineering heritage, and application-specific process knowledge create meaningful barriers to entry. It also means that late-stage entrants or commoditized hardware suppliers face mounting pressure to differentiate through automation, integration, and lifecycle support rather than equipment price alone.
Several companies define the current architecture of the sector. GEA Group AG, headquartered in Düsseldorf, Germany, provides specialized spray drying solutions spanning dairy, food ingredients, pharmaceutical, and instant coffee production, with GEA NIRO® plants serving as a reference point for integrated drying and particle processing. SPX FLOW, Inc., based in Charlotte, North Carolina, offers Anhydro-branded spray dryers tailored to food, dairy, and pharmaceutical powders, emphasizing advanced atomization and process technology. Tetra Pak International SA, operating from Pully, Switzerland, delivers automated spray drying systems for dairy, whey, and plant-based powders using Wide Body technology, aligning drying capability with broader processing and packaging ecosystems.
Beyond the large-scale industrial leaders, the market includes firms that address adjacent but strategically important niches. BÜCHI Labortechnik AG, headquartered in Flawil, Switzerland, manufactures laboratory and pilot-scale spray dryers for research, quality control, and small-scale pharmaceutical and chemical applications, enabling formulation teams to de-risk scale-up before committing to full production assets. VetterTec GmbH, based in Kassel, Germany, supplies customized industrial spray dryers for food, chemical, and starch industries, offering pilot to full-scale units built on more than forty years of experience. Pulse Combustion Systems, located in Arizona, develops pulse atomization spray dryers aimed at energy-efficient drying across food, chemical, mineral, and pharmaceutical powders, positioning energy performance as a core differentiator. Dedert Corporation, based in Homewood, Illinois, supplies U.S.-made spray dryers for starch, food, and industrial powder production. Changzhou Jinqiao Spray Drying and Engineering Co., Ltd. operates from Changzhou, Jiangsu, China, manufacturing milk and food spray dryers with precision engineering and automation designed for dairy applications.
Recent activity underscores how these players are positioning themselves for the next cycle. In August 2025, GEA Group AG introduced an advanced pharmaceutical spray dryer to Chugai Pharmaceutical, targeting enhanced product development and manufacturing capabilities. In March 2025, RISE PFI installed a new spray dryer in a laboratory setting to improve the efficient separation of solids from liquids or suspensions into powder. These developments are indicative of two broader trends: first, the continued push to bring higher-performance drying into specialized formulation and R&D environments, and second, the growing expectation that drying equipment will be evaluated not just for throughput but for reproducibility, modular integration, and process control.
Regulatory and Operational Dynamics Redefining Requirements
The operating environment for spray drying infrastructure is being reshaped by regulatory expectations and process-validation demands. As of February 2, 2026, the FDA Quality Management System Regulation became effective, incorporating ISO 13485:2016 for medical device manufacturers, including spray dryers used in pharmaceutical production. This alignment raises the bar for documentation, design controls, and management-system rigor across equipment that interfaces with regulated product streams. In parallel, industry standards for process validation and design space optimization under quality-by-design principles continue to be required under FDA guidance for spray dryers in pharmaceutical applications. For manufacturers, this means that drying is no longer treated as an isolated unit operation. It must be demonstrably integrated into a controlled, validated, and auditable process architecture.
These dynamics carry direct implications for sourcing, commissioning, and lifecycle management. Equipment that supports traceability, configurable control logic, and robust cleaning and sanitation pathways is increasingly favored, especially where formulation integrity and cross-contamination risk must be tightly managed. At the same time, the necessity for trained personnel to perform regular maintenance, cleaning, and sanitation highlights a labor dimension that is often underestimated during feasibility studies. The operational burden of sustaining compliant, high-uptime drying lines means that service networks, operator training, and remote diagnostics are becoming part of the competitive value proposition rather than afterthoughts.
Energy and capital intensity remain foundational considerations. Spray drying is inherently power-demanding, and the scale required for industrial throughput often translates into significant capital outlays and operating costs. As utilities pricing and sustainability mandates continue to influence return-on-investment calculations, procurement teams are scrutinizing atomizer selection, thermal efficiency, and integration with broader plant energy systems. This is where differentiated technologies and customized engineering can shift the economics of a project, but only when they are evaluated against real process requirements rather than isolated equipment specifications.
Segment Architecture and Decision-Relevant Trade-offs
The market’s structure is divided across type, application, and geography, and each lens reveals different strategic trade-offs. By type, the landscape includes rotary atomizer, nozzle atomizer, fluidized, closed loop, and centrifugal configurations. Each technology family carries distinct implications for particle size distribution, thermal exposure, feedstock viscosity tolerance, and operational flexibility. By application, demand is anchored in food and dairy, pharmaceutical, chemical, and other end-use categories, where formulation goals, regulatory exposure, and throughput requirements differ materially. By region, activity is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, reflecting varied manufacturing bases, procurement norms, and industry maturity levels.
Spray Dryer Market
These structural divisions matter because they shape not only where demand originates, but how equipment should be specified. A formulation team working with heat-sensitive actives will evaluate drying architecture differently from a producer focused on high-volume dairy powder or starch derivatives. A laboratory or pilot-scale program will prioritize reproducibility and rapid changeover, while an industrial line will emphasize uptime, utility efficiency, and integration with upstream and downstream modules. The strategic question for 2026 is not which segment is largest in isolation, but which combination of type, application, and operating context aligns with a company’s product roadmap, compliance posture, and scale-up cadence.
Why the 2026 Market Research Is Differentiated for Decision-Making
The Spray Dryer Market research is designed to convert these dynamics into actionable intelligence. Rather than presenting a static snapshot, the report maps the path from historical performance through the 2026 to 2032 forecast window, allowing leadership teams to stress-test capacity plans, product entry timing, and supplier selection against a structured forward view. The analysis integrates process technology considerations, application-driven demand patterns, and competitive positioning into a single decision framework, helping stakeholders connect equipment selection to broader commercial objectives.
Food Dryer Market
Practically, the report supports multiple use cases. For capital planning and plant expansion, it provides a structured basis for evaluating whether in-house drying capability, modular pilot assets, or outsourced conversion offers the better risk-adjusted path. For product development teams, it contextualizes how atomization choices influence formulation feasibility, scale-up risk, and process validation burden. For procurement and engineering leaders, it frames supplier evaluation around integration, automation, service readiness, and alignment with evolving regulatory expectations. For corporate strategy and M&A functions, it identifies where consolidation dynamics and technology differentiation are likely to shape vendor resilience and partnership value.
The research also addresses the practical realities that often determine project outcomes. It examines how energy intensity, labor requirements, maintenance discipline, and sanitation protocols interact with equipment architecture and total cost of ownership. It situates recent equipment installations and product introductions within the broader demand environment, helping readers distinguish one-off announcements from durable shifts in capability expectations. And it places regulatory developments, including quality management system alignment and process validation standards, in the context of supplier qualification and long-term operating risk.
Organizations that use this intelligence effectively will not simply track market size. They will use it to prioritize where to invest, which operating parameters to optimize, and how to structure supplier relationships so that drying capability becomes a source of competitive advantage rather than a constraint. The most consequential decisions in 2026 will be made by teams that can connect particle engineering, compliance readiness, and commercial strategy into a coherent plan.
Connect to the Full Intelligence Package
The Spray Dryer Market research translates a complex intersection of technology, regulation, and demand into a focused decision tool for 2026 and the forecast period ahead. It is built to support capacity strategy, supplier evaluation, application planning, and investment prioritization with a clear view of where the market is headed and why. To access the complete segmentation analysis, full forecast pathway, competitive profiling, and operational-risk assessment that support these conclusions, please visit the PW Consulting market research page for the complete report and detailed executive summaries.
For detailed analysis of this topic, please visit the official page: Spray Dryer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Data Diode Market Hits $215.75M in 2025, Projects 7.15% CAGR to $349.05M by 2032
By pmarketresearch, 2026-09-15
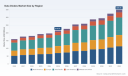
Navigating the Data Diode Market: Strategic Intelligence for the 2026 Enterprise Landscape
In an era where cyber threats increasingly target operational continuity and classified information flows, the Data Diodes Market has emerged as a critical infrastructure layer for organizations demanding uncompromising network isolation. As we move through 2026, enterprises across government, energy, and industrial sectors face mounting pressure to secure unidirectional data pathways without sacrificing real-time visibility or compliance readiness. The latest research from PW Consulting delivers a comprehensive, forward-looking analysis of this rapidly maturing market, equipping leadership teams with the analytical rigor needed to navigate technology selection, vendor evaluation, and long-term capital allocation.
This market intelligence report spans historical performance from 2020 through 2025 and extends its forecasting horizon to 2032, providing a complete view of the trajectory that has shaped today’s competitive environment. The global market, valued at approximately 215.75 million USD in 2025, is projected to reach 349.05 million USD by the close of the forecast period, reflecting a compound annual growth rate of 7.15%. These figures represent more than headline valuation; they map the steady structural expansion of hardware-enforced security architectures driven by regulatory mandates, critical infrastructure modernization, and the growing impossibility of relying on software-only isolation in high-assurance environments. Decision-makers who understand the underlying velocity of this growth can better anticipate procurement windows, align internal security roadmaps, and position their organizations ahead of supply chain bottlenecks.
Why This Research Matters for 2026 Decision-Making
Enterprise security leaders no longer operate in a landscape where data diode adoption is a niche consideration. The convergence of operational technology exposure, cross-domain data sharing requirements, and classified information handling protocols has transformed unidirectional gateways into foundational components of zero-trust and network segmentation strategies. Yet the market remains fragmented across product architectures, certification standards, and deployment contexts. Without a structured view of how these variables interact, procurement teams risk investing in solutions misaligned with operational realities or regulatory expectations.
The value of this report lies in its translational approach. Rather than presenting isolated metrics, the analysis connects market sizing trends to real procurement drivers, competitive positioning, and the evolving technical requirements that define successful deployments. Organizations preparing budgets for fiscal 2027, evaluating vendor shortlists, or designing secure OT/IT integration architectures will find actionable frameworks that reduce evaluation time and sharpen investment criteria. The research is structured to support multiple functions: cybersecurity architecture teams can reference product classification and certification pathways; operations leaders can assess deployment complexity and integration demands; and procurement executives can use the competitive landscape analysis to benchmark pricing rationales, service expectations, and long-term vendor viability.
Market Structure and Thematic Drivers
The market’s expansion has been shaped by a clear shift from legacy manual transport procedures toward automated, hardware-enforced one-way transfer. Organizations that previously relied on physical media movement or logistically heavy retrieval processes have documented annual costs ranging from 2,100 to 10,000 USD per workflow, alongside significant operational drag and human-error exposure. These inefficiencies have accelerated adoption among enterprises seeking repeatable, auditable, and tamper-resistant data flow controls. At the same time, regulatory alignment has become a decisive purchasing factor. Unidirectional gateway architectures are increasingly evaluated against established industrial cybersecurity guidance, including frameworks that emphasize lateral movement prevention in operational technology environments. Certifications issued by national defense and security authorities have also become key differentiators, particularly for organizations managing information at classified or restricted levels.
The report provides a detailed breakdown of how product types, application domains, and regional demand patterns interact to shape total addressable opportunity. While the overall market continues to grow at a steady pace, the underlying composition reveals a landscape where ruggedized and specialized form factors are gaining relevance in harsh-environment deployments, and where high-throughput protocol filtering diodes are redefining performance expectations in defense and critical infrastructure contexts. Rather than presenting static splits, the analysis explains how each segment responds to distinct deployment constraints, certification requirements, and integration pathways, enabling buyers to map their operational profile to the most relevant technology categories.
Competitive Landscape: Leaders Shaping the Unidirectional Security Market
No examination of this market would be complete without a rigorous assessment of the companies defining its direction. The competitive environment is characterized by a mix of specialized security vendors, industrial networking providers, and defense-oriented engineering firms, each pursuing distinct value propositions across certification, throughput, environmental hardening, and integration depth. The research profiles a broad set of market participants, including Owl Cyber Defense, OPSWAT, Fibersystem AB, Patton Electronics, Advenica, BAE Systems, Waterfall Security Solutions, ST Engineering, Nexor, Garland Technology, Valiant Communications, and Everfox.
The competitive analysis goes beyond corporate descriptions to examine how each organization’s offering aligns with market demand signals. In the defense and government segment, vendors with validated protocol filtering capabilities and high-assurance transfer performance have gained renewed attention as cross-domain requirements intensify. In industrial and operational technology environments, the emphasis has shifted toward hardware-enforced isolation combined with software intelligence that can sanitize, replicate, and contextualize data flows without exposing control networks. Ruggedized and TEMPEST-aligned product families continue to serve niche but strategically vital deployments where electromagnetic emission control and extreme environmental tolerance are non-negotiable. Meanwhile, companies focused on standardized DIN-rail form factors and industrial protocol support have expanded the practical usability of data diodes in manufacturing and process automation settings.
Recent corporate activity underscores the pace of differentiation. In early 2026, Owl Cyber Defense received U.S. Government verification for its Talon Torrent as an approved protocol filtering diode capable of reliable one-way transfer up to 100 Gbps, reinforcing the importance of certified performance in high-throughput defense and critical infrastructure applications. That same year, the company introduced a pocket-sized Incident Response Diode designed for forensic evidence collection from compromised endpoints through USB, using hardware-enforced one-way protocol filtering. This product direction illustrates a broader market trend: data diodes are increasingly evaluated not only for bulk data transfer, but also for specialized incident response, evidence preservation, and targeted operational workflows. Shortly thereafter, Owl integrated VTScada SCADA software with its data diode portfolio to enable secure one-way operational data transfer from OT to IT and cloud environments in water and wastewater systems, with initial deployments in Houston and Nashville. These moves demonstrate how vendors are extending the reach of unidirectional security into live operational networks where continuous monitoring and secure telemetry are essential.
Across the broader field, product launches have reflected the market’s diversification. Advenica introduced a data diode engineered specifically for railway trackside applications, compliant with EN railway standards and designed to operate without additional security software, highlighting the demand for deployment simplicity in transportation infrastructure. Patton Electronics expanded its industrial networking portfolio with a DIN-rail FiberPlex FP-DD100 data diode supporting OPC UA and MQTT protocols, reinforcing the importance of protocol readiness in plant and factory environments. Advenica’s product documentation also underscores N3 certification under Swedish Armed Forces standards for information up to TOP SECRET levels, illustrating how national certification frameworks continue to influence procurement decisions in sensitive government and defense contexts. These developments are not isolated highlights; they are indicators of how product strategy, standards alignment, and deployment context are converging across the competitive landscape.
Deployment Dynamics, Regulatory Alignment, and Infrastructure Considerations
One of the most valuable contributions of this research is its treatment of deployment realities. Data diodes are no longer evaluated solely on their ability to enforce one-way flow; buyers now assess integration complexity, environmental suitability, protocol coverage, and the broader security ecosystem in which the device will operate. In industrial monitoring and network segmentation contexts, diode TAPs have become part of the foundational infrastructure for enabling raw data flow without exposing sensitive control planes. In OT/ICS environments, unidirectional gateways are increasingly scrutinized for their ability to align with established cybersecurity guidance and to reduce lateral movement risk across networks of differing trust levels. The report examines these operational dynamics in detail, connecting them to procurement criteria such as certification traceability, maintenance requirements, and long-term interoperability.
The analysis also addresses the role of certification and regulatory alignment as procurement accelerators. Where national defense certifications, Common Criteria evaluations, and industrial cybersecurity frameworks apply, they shape not only product eligibility but also the timeline and confidence with which enterprises can deploy solutions. For organizations operating in multi-jurisdictional environments, understanding which certifications carry weight in which sectors can materially influence vendor selection and deployment sequencing. The report maps these considerations to real purchasing behavior rather than abstract compliance language, helping decision-makers anticipate which validation pathways will matter most for their specific operating environment.
Rectifier Diode Market
How the Report Supports Actionable Strategy
This research is designed for practical use. It provides structured coverage across market sizing, segmentation logic, competitive benchmarking, and deployment context, giving organizations a single reference point for strategy development. Readers will find detailed profiles of market participants, an assessment of recent product launches and partnership activity, and analysis of how certification status and technical architecture influence adoption in different sectors. The report examines market concentration indicators and competitive dispersion to help buyers understand where consolidation pressure exists and where specialized differentiation remains viable. It also outlines the operational and regulatory forces that are likely to shape demand through the end of the forecast period, enabling leadership teams to prepare for supply alignment, capability planning, and procurement timing.
Importantly, the report avoids superficial vendor rankings or static market splits. Instead, it explains how different product categories perform under varying operational constraints, which certification pathways carry the most weight in different sectors, and how integration requirements influence total cost and deployment risk. This approach ensures that the findings can be used not only for immediate purchasing decisions but also for longer-term security architecture planning and portfolio strategy.
Data Diodes Market
Conclusion: Moving From Awareness to Informed Execution
The Data Diodes Market is no longer defined by incremental interest; it is being reshaped by tangible operational needs, certification expectations, and the growing recognition that hardware-enforced unidirectional transfer is essential in environments where software-only isolation is insufficient. With a market trajectory that reflects steady expansion toward a valuation of 349.05 million USD by 2032 and a compound annual growth rate of 7.15%, the sector presents both opportunity and complexity for enterprises seeking to strengthen their security posture. The difference between reactive adoption and strategic execution lies in the quality of market intelligence guiding the decision process.
This PW Consulting report provides that intelligence. It equips cybersecurity leaders, operations executives, and procurement professionals with the context needed to evaluate vendors, align technology choices with operational requirements, and anticipate the regulatory and competitive dynamics that will influence the market through the end of the decade. For organizations preparing to commit resources in 2026 and beyond, the full analysis offers the depth, structure, and strategic framing necessary to turn market momentum into informed action. The complete market intelligence, including detailed segmentation analysis, competitive benchmarking, and forward-looking procurement guidance, is available through the full report.
For detailed analysis of this topic, please visit the official page: Data Diodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Advanced CO2 Sensors Market Hits $690M in 2025, Projected to Reach $1.12B by 2032
By pmarketresearch, 2026-09-15
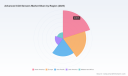
Strategic Imperatives in the Advanced CO2 Sensors Market: Navigating Growth and Regulation Through 2032
The global transition toward smarter, healthier, and more energy-efficient environments has placed advanced carbon dioxide sensing technology at the center of industrial and commercial strategy. For executives, procurement leaders, and innovation managers, the question is no longer whether to invest in CO2 sensing infrastructure, but how to navigate a rapidly evolving landscape defined by tightening regulations, technological miniaturization, and shifting demand patterns. PW Consulting's latest Advanced CO2 Sensors Market research provides a comprehensive blueprint for understanding these forces, offering decision-makers the granular intelligence required to allocate capital, shape product roadmaps, and secure competitive positioning between 2026 and 2032.
Market Trajectory and Macroeconomic Context
The market for advanced CO2 sensors has demonstrated consistent expansion over the past half-decade, driven by the convergence of environmental awareness, building efficiency mandates, and industrial safety requirements. Historical data from 2020 through 2025 reveals a sector that has successfully navigated supply chain disruptions and component shortages to deliver robust revenue growth. The baseline year of 2025 anchors the market at approximately USD 690.0 million, a substantial increase from the USD 475.8 million recorded in 2020. This upward trajectory reflects not merely cyclical recovery but structural demand shifts that are reshaping procurement priorities across multiple verticals.
Looking forward, our forecast period spanning 2026 through 2032 projects sustained momentum for the industry. By 2026, market revenue is anticipated to cross USD 754.4 million, with growth compounding steadily toward the USD 1.1 billion threshold by 2032. The compound annual growth rate of 7.1 percent during this window underscores the durability of underlying demand drivers, even as macroeconomic headwinds and inflationary pressures continue to influence capital expenditure decisions globally. For enterprises evaluating market entry, capacity expansion, or portfolio diversification, this growth curve provides a critical baseline for scenario planning and investment justification.
Several structural factors underpin this expansion. The acceleration of demand-controlled ventilation (DCV) deployments in both new construction and retrofit projects has generated a reliable pipeline of sensor requirements. Simultaneously, the proliferation of Internet of Things (IoT) architectures and the push toward smart building certifications have elevated CO2 monitoring from a compliance checkbox to a foundational component of operational strategy. Industries ranging from healthcare to automotive and petrochemical processing are recalibrating their air quality standards, recognizing that real-time gas detection capabilities directly influence occupant health, regulatory compliance, and energy expenditure optimization.
Regulatory Tailwinds and Industry Dynamics
Regulatory frameworks are emerging as perhaps the most potent catalyst for market growth, transforming CO2 sensing from an optional enhancement into a compliance necessity in key jurisdictions. The ANSI/ASHRAE Standard 62.1-2022 Addendum d has established stringent requirements for demand-controlled ventilation systems, mandating precise CO2 measurement to achieve energy-efficient building codes. This standard has compelled building owners, HVAC integrators, and sensor manufacturers to align their product specifications with rigorous performance thresholds, creating a measurable uplift in demand for high-accuracy sensing solutions.
Beyond North American standards, the European Union's Energy Performance of Buildings Directive has set a trajectory toward zero-emission standards for new buildings by 2030. This directive not only imposes emission targets but also drives demand for advanced CO2 sensors integrated into DCV systems, as building operators seek to demonstrate compliance while minimizing energy consumption. The intersection of these regulatory mandates with certification frameworks such as RESET Grade B and the WELL Building Standard v2 has further broadened the addressable market, requiring sensor technologies that can satisfy overlapping compliance criteria without compromising deployment economics.
Advanced CO2 Sensors Market
These regulatory dynamics interact with technological advancement in ways that reshape competitive battles. Manufacturers are now evaluated not only on measurement accuracy but also on form factor, power consumption, integration compatibility, and certification readiness. The pressure to meet multiple standards simultaneously has accelerated innovation cycles and compressed development timelines, placing a premium on research and development agility. Companies that fail to align their sensor portfolios with evolving regulatory expectations risk marginalization, while those that proactively embed compliance into their product architecture are positioned to capture disproportionate market share.
Survey of the Competitive Landscape
The advanced CO2 sensors market is characterized by a concentrated competitive structure, with the top three players accounting for approximately 55 percent of market revenue and the top five controlling an estimated 68 percent. This concentration reflects the technical barriers to entry, the capital intensity of optical sensing research, and the long qualification cycles associated with building automation and industrial applications. Nevertheless, the market remains dynamic, with established players and emerging innovators competing on dimensions beyond raw market share, including technological differentiation, regional footprint, and ecosystem integration capabilities.
Senseair, headquartered in Sweden, has built its reputation on ultra-compact NDIR CO2 sensors designed for demand-controlled ventilation and indoor air quality monitoring. The S12 series exemplifies the company's focus on size reduction and surface-mount device integration, enabling OEMs to embed sensing capabilities in space-constrained smart building environments. In January 2026, Senseair launched a new iteration of the S12 sensor, achieving a 75 percent size reduction relative to predecessors while maintaining SMD solderability. The product is positioned as compliant with ASHRAE 62.1-2022 Addendum d, RESET Grade B, and WELL Building Standard v2 standards, and mass production is slated for 2026 following sample distribution.
Sensirion AG, based in Switzerland, has differentiated itself through high-accuracy photoacoustic NDIR CO2 sensors, most notably the SCD4x series and the recently announced SCD43. The SCD43, launched in February 2025 as a drop-in upgrade for the SCD4x platform, delivers best-in-class accuracy of ±(30 ppm + 3% m.v.) and targets compliance with ASHRAE 62.1 Draft Addendum d. By offering summer 2025 availability, Sensirion has signaled its intent to capture demand from building standards compliance and compact environmental monitoring applications. The photoacoustic approach allows for competitive performance in form factors that would be challenging for traditional NDIR implementations, broadening the application envelope for precision sensing.
Gas Sensing Solutions, operating from the United Kingdom, has focused on the CozIR series of solid-state NDIR CO2 sensors optimized for ultra-low power consumption. These devices are particularly relevant for IoT deployments and battery-powered applications where energy efficiency dictates operational viability. The integration of environmental sensing capabilities within a single package positions the CozIR series as a versatile solution for remote monitoring scenarios, where maintenance logistics and power constraints are paramount considerations.
Vaisala Oyj, a Finnish manufacturer, leverages advanced optical technology to produce NDIR CO2 sensors tailored for precision building management, industrial environments, and data-center applications. The emphasis on stability and reliability under demanding conditions has made Vaisala a preferred choice for mission-critical deployments where sensor drift or failure carries significant operational consequences. Amphenol Advanced Sensors, based in the United States, complements this landscape by supplying compact and low-power CO2 sensors for HVAC, IoT, and environmental monitoring applications, with a particular focus on miniaturization without sacrificing measurement accuracy.
Air Quality Sensor Market
The competitive field also includes integrators and diversified technology conglomerates. Siemens AG, headquartered in Germany, embeds NDIR CO2 sensor modules directly into building management systems, offering portfolios that address HVAC and air quality control requirements within broader automation architectures. Honeywell International Inc., also US-based, provides both chemical and infrared CO2 sensors targeted at safety, indoor air quality, and industrial applications, with low-power draw options that align with energy-conscious deployment strategies. These diversified players illustrate how CO2 sensing is increasingly being absorbed into larger ecosystem plays, where value is created through system-level integration rather than sensor component sales alone.
Segmentation Insights and Structural Demand Drivers
The market structure reveals distinct demand clusters that inform go-to-market strategies for manufacturers and procurement decisions for end users. In terms of technology type, NDIR CO2 sensors dominate the revenue landscape, reflecting the industry's preference for optical-based measurement techniques that offer long-term stability, minimal drift, and compatibility with continuous monitoring applications. Chemical CO2 sensors occupy a meaningful secondary position, serving applications where cost profile, power constraints, or specific environmental characteristics favor alternative sensing mechanisms. The coexistence of these technology pathways highlights the absence of a one-size-fits-all solution and the importance of matching sensor architecture to application requirements.
Application segmentation further illuminates where value is being created. Building automation represents the largest demand pool, aligning with the regulatory and certification dynamics discussed earlier. The integration of CO2 sensing into HVAC control loops, occupancy-based ventilation strategies, and indoor air quality dashboards has become a standard expectation rather than a premium feature. Healthcare applications constitute the second major pillar, driven by infection control protocols, operating room environmental management, and patient comfort standards that demand reliable gas monitoring. Industrial applications follow closely, encompassing process monitoring, safety systems, and environmental compliance in manufacturing and processing facilities.
The automotive and petrochemical segments, while smaller in aggregate revenue terms, represent high-growth niches where sensor requirements are shaped by distinct constraints. Automotive applications demand robustness, fast response times, and integration with cabin air quality management systems, while petrochemical deployments prioritize accuracy under challenging atmospheric conditions and compliance with safety regulations. The geographic distribution of demand mirrors these application dynamics, with developed markets in North America and Europe maintaining the largest shares due to regulatory maturity and building stock renovation cycles, while Asia Pacific and other emerging regions are expanding as construction activity intensifies and standards adoption accelerates.
It is critical for stakeholders to recognize that these segmentation patterns are not static. As new building standards take effect, as IoT deployment models mature, and as manufacturing automation deepens, the relative weight of each application segment will shift. Our research provides the framework for anticipating these shifts, identifying leading indicators of demand migration, and recalibrating product and sales strategies before competitors react.
Report Scope and Actionable Intelligence
PW Consulting's Advanced CO2 Sensors Market research is designed to equip decision-makers with more than macro-level trends. The full report delivers a multi-dimensional analysis that bridges strategic vision with operational execution, structured around the following core components:
- Historical and Forecast Revenue Analysis: A detailed chronological breakdown spanning 2020 through 2032, enabling readers to validate growth assumptions, identify inflection points, and benchmark internal performance against market trajectories.
- Technology-Type Deep Dive: Comprehensive profiling of NDIR and chemical sensor categories, including performance characteristics, cost structures, integration considerations, and suitability profiles for specific application environments. This section equips R&D and product management teams with the technical context needed to prioritize development investments.
- Application-Specific Demand Mapping: Granular examination of building automation, healthcare, industrial, automotive, and petrochemical use cases, with attention to deployment drivers, specification requirements, purchase decision workflows, and pricing dynamics. Procurement leaders and sales strategists will find actionable guidance for segment-specific positioning.
- Regional Market Intelligence: Analysis of demand distribution and growth prospects across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The report examines regulatory adoption timelines, construction activity indicators, and competitive intensity in each region, enabling geographic resource allocation decisions.
- Corporate Profiles and Strategic Positioning: Detailed assessments of leading manufacturers, covering headquarters, product portfolios, technological differentiators, recent launches, and strategic implications. Profiles include Senseair, Sensirion AG, Gas Sensing Solutions, Vaisala Oyj, Amphenol Advanced Sensors, Siemens AG, and Honeywell International Inc., with attention to how each competitor is navigating the current landscape.
- Recent Developments Tracker: A chronologically organized record of product launches, regulatory updates, and strategic moves. Notable entries include Senseair's January 2026 S12 sensor launch and Sensirion's February 2025 SCD43 announcement, contextualized within the broader compliance and standards environment.
- Competitive Concentration and Market Structure Analysis: Evaluation of market concentration metrics, barriers to entry, consolidation risks, and partnership opportunities. This section supports M&A screening, competitive benchmarking, and strategic positioning exercises.
- Executive Summary and Strategic Recommendations: A synthesized overview tailored for C-suite audiences, translating analytical findings into prioritized action items for investment, innovation, partnership, and market entry decisions.
Each section is structured to facilitate rapid extraction of relevant insights while providing sufficient depth for thorough strategic analysis. Decision-makers are encouraged to consult the full report for the complete dataset, including segmentation splits, regional breakdowns, and detailed revenue figures that inform precise planning assumptions.
Strategic Recommendations for 2026 and Beyond
The intersection of regulatory momentum, technological innovation, and market growth creates a window of strategic opportunity that demands decisive action. For manufacturers and technology providers, the imperative is to accelerate development cycles while ensuring that sensor architectures are validated against the most demanding current standards, including ASHRAE 62.1-2022 Addendum d and relevant certification frameworks. Product roadmaps that prioritize miniaturization, low power consumption, and integration readiness will resonate with the IoT-driven deployment models that are expanding addressable use cases. Investment in photoacoustic and advanced NDIR technologies should be viewed not as optional enhancement but as foundational capability required to defend market position.
For end-user organizations and integrators, the priority lies in aligning procurement strategies with the trajectory of regulatory tightening and building certification requirements. Specifications should be updated to reflect the accuracy thresholds and compliance attributes demanded by emerging standards, and vendor evaluation criteria should incorporate long-term drift performance, certification documentation, and ecosystem compatibility alongside initial cost considerations. Procurement processes that favor lowest upfront price may inadvertently increase lifecycle costs through calibration frequency, premature replacement, or non-compliance penalties.
For investors and market entrants, the concentration structure of the industry signals both barriers and opportunities. Incumbents benefit from established qualification relationships and technical reputation, but the pace of innovation and the breadth of new application domains create openings for differentiated offerings. Targeting underpenetrated verticals, developing region-specific compliance packages, or pursuing strategic partnerships with building automation platforms can provide pathways to growth even in a concentrated market environment.
Conclusion: Securing Competitive Advantage Through Intelligence
The Advanced CO2 Sensors Market is entering a phase where regulatory discipline, technological capability, and demand expansion converge to reward organizations that invest in structured, data-backed strategic decision-making. The historical growth record, the projected 7.1 percent CAGR through 2032, and the active regulatory landscape collectively affirm that CO2 sensing is a strategic technology rather than a discretionary purchase. Yet the complexity of segmentation, the intensity of competition, and the velocity of standard evolution demand more than high-level awareness. They require detailed intelligence that informs specific investments, product specifications, geographic prioritization, and partnership choices.
PW Consulting's full market research report delivers the depth required to navigate this environment with confidence. By accessing the complete analysis, stakeholders will gain the segmentation data, regional breakdowns, revenue trajectories, and competitive profiles necessary to transform market awareness into actionable strategy. We invite executives, product leaders, and investment professionals to engage with the full report, exploring the comprehensive dataset and analytical frameworks that underpin the insights presented here. The path from regulatory pressure to commercial advantage runs through informed decision-making, and the intelligence contained in this research is structured to empower that journey.
For detailed analysis of this topic, please visit the official page: Advanced CO2 Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fiber Laser Cutting Machines Market Poised to Reach $2.51 Billion by 2032 at 5.3% CAGR
By pmarketresearch, 2026-09-15
Navigating the Fiber Laser Cutting Machines Market: Strategic Intelligence for 2026 and Beyond
The global manufacturing landscape is undergoing a profound transformation driven by precision, efficiency, and automation. At the forefront of this shift is the fiber laser cutting machines market, a critical enabler for industries ranging from heavy industrial machinery to high-tech automotive production. As we move through 2026, enterprise decision-makers face a complex environment characterized by rapid technological evolution, shifting supply chain dynamics, and intensifying competitive pressure. Understanding the trajectory of this market is no longer optional; it is a strategic imperative for capital allocation, capacity planning, and long-term competitive positioning.
PW Consulting's latest comprehensive market research provides a detailed roadmap of the fiber laser cutting machines industry. This analysis bridges the gap between historical performance and future potential, offering the granular intelligence required to navigate the forecast period spanning 2026 through 2032. The following insights outline the strategic value of this research, highlighting key market dynamics, competitive forces, and operational considerations that will define success in the coming years.
Market Trajectory and Growth Fundamentals
Historical data indicates a robust expansion trajectory for the fiber laser cutting machines sector. Over the historical period from 2020 to 2025, the market demonstrated consistent resilience and growth, culminating in a solid revenue base in 2025. This foundational strength sets the stage for the forecast period, where the market is projected to continue its upward momentum. The analysis identifies a steady Compound Annual Growth Rate (CAGR) throughout the 2026-2032 forecast window, signaling sustained demand across multiple verticals.
Laser Cutting Machines Market
Revenue Evolution and Scale
The financial scale of this market underscores its significance within the broader industrial automation ecosystem. Revenue valuations have progressed from approximately 1.35 billion USD in 2020 to an estimated 1.74 billion USD in 2025. Looking forward, the market is expected to breach the 2 billion USD threshold during the forecast period, reaching substantial valuations by 2032. This growth is not merely linear; it reflects underlying shifts in manufacturing capabilities and the increasing integration of laser technology into standard production workflows.
- Base Year Context: The 2025 base year establishes a critical benchmark, reflecting post-pandemic recovery stabilization and the accelerated adoption of automated cutting solutions.
- Forecast Horizon: The projection extends through 2032, allowing stakeholders to model long-term investments and assess the viability of multi-year technology roadmaps.
- Currency Standardization: All financial data is presented in USD Million, ensuring consistency for global comparative analysis and investment modeling.
While macroeconomic fluctuations can impact capital expenditure cycles, the structural drivers supporting fiber laser adoption remain intact. The transition from traditional mechanical cutting to high-precision laser systems is driven by the need for reduced operational costs, improved material utilization, and tighter tolerances required by modern engineering specifications.
Dynamics Shaping the Market Landscape
Several macro and micro factors are converging to accelerate the deployment of fiber laser cutting machines. These dynamics create both opportunities for growth and challenges that require strategic mitigation. Understanding these forces is essential for interpreting the market data and anticipating shifts in demand patterns.
Energy Efficiency and Operational Costs
Energy efficiency mandates are becoming a primary driver for technology selection in industrial facilities. Fiber laser cutting machines offer a distinct advantage over traditional methods due to their solid-state design. This architecture requires minimal mirrors and reduces maintenance overhead, leading to lower operating costs over the lifecycle of the equipment. As industries face pressure to reduce carbon footprints and energy consumption, the inherent efficiency of fiber laser technology aligns with broader sustainability goals.
Labor Constraints and Automation
The metal fabrication sector is grappling with persistent labor shortages and rising wage pressures. Automation labor shortages are driving demand for high-power fiber laser systems that enable faster, more precise processing with reduced manual intervention. Machines equipped with advanced automation features allow facilities to maintain throughput levels even when skilled labor is scarce. This trend is particularly pronounced in regions where demographic shifts are impacting the availability of experienced machine operators.
Regulatory and Safety Compliance
Regulatory frameworks continue to evolve, mandating stricter safety standards for industrial laser equipment. OSHA and ISO safety standards require Class 4 laser safety features, including automatic beam shutters and protective enclosures. Compliance with these regulations is not only a legal requirement but also a competitive differentiator for manufacturers seeking to export equipment to regulated markets. Furthermore, CE and FDA/CDRH certifications are required for export and use in European and US markets, influencing the market entry strategies of key players.
Supply Chain and Component Technology
The core component of fiber laser cutting machines is the rare-earth-doped optical fiber gain medium, typically ytterbium-doped. This medium generates the beam through solid-state excitation and focuses it via optics for metal cutting. Stability in the supply of these specialized components is critical. Disruptions in the supply chain for high-quality optical fibers or pump sources can impact manufacturing timelines and costs. Recent industry developments highlight ongoing innovation in beam quality and power density, pushing the boundaries of what is possible in terms of cutting speed and material thickness.
Competitive Landscape and Strategic Positioning
The market exhibits a moderate level of concentration, with a handful of dominant players commanding a significant share of revenue. However, the landscape is diverse, ranging from specialized laser source manufacturers to integrated system providers. The analysis reveals a CR3 of approximately 36 percent and a CR5 of roughly 48 percent, indicating that while leadership is consolidated, there remains substantial room for specialized competitors and regional players.
Key Industry Players
Several companies define the current competitive architecture. IPG Photonics, headquartered in Marlborough, Massachusetts, stands as a world leader in fiber laser sources and integrated systems. They offer custom robotic and automated fiber laser cutting cells and high-power industrial solutions for metal fabrication. Their recent recognition with the SPIE Prism Award for a novel 8 kW compact single-mode fiber laser source with exceptional beam quality highlights their continued focus on technological superiority.
TRUMPF, based in Ditzingen, Germany, is a global provider of TruLaser 2D fiber laser cutting machines, including the 3000, 5000, and 8000 series, alongside TruFiber lasers. Their portfolio includes bevel cutting and automation for industrial sheet metal processing. TRUMPF recently launched a new high-productivity TruFiber fiber laser series suitable for industrial welding and cutting applications, including EV battery components, signaling a strategic pivot towards electrification supply chains.
Fiber Laser Cutting Machines Market
Bystronic, from Balgach, Switzerland, supplies ByStar Fiber laser cutting systems with advanced automation and software. They offer complete solutions for sheet metal cutting with integration of laser heads and loaders. Bystronic showcased the ByCut 3015 laser cutting system with SSC V3.2 cutting head and modular frame at CIIF 2025. Furthermore, in early 2026, Bystronic finalized the acquisition of Coherent's Tools for Materials Processing unit, expanding fiber laser capabilities and consolidating market presence.
Coherent, located in Santa Clara, California, produces the EDGE FL series and industrial precision fiber laser sources/solutions for metal cutting and welding applications in automotive, aerospace, and energy sectors. They announced the EDGE FL series high-power fiber laser platform for industrial cutting and machine tool integration in late 2025. Other notable participants include Hytek Tools, emphasizing speed and precision; Epilog Laser, with enclosed and open-bed designs for commercial use; Cincinnati Incorporated, providing heavy-duty industrial metal processing systems; Boss Laser, producing machines capable of cutting over 20 materials; Haas CNC, supplying fully enclosed CNC fiber laser cutting machines with autofocus sensors; and Laser Photonics, developing high-power systems for industrial applications.
Recent Developments and M&A Activity
The competitive landscape is dynamic, with frequent product launches and strategic moves reshaping market shares. In addition to the product launches mentioned above, AP Lazer demonstrated a powerful new dual-laser fiber system at NDFA 2025. These activities indicate a race towards higher power densities, better integration with factory automation software, and diversification into new application verticals such as electric vehicle component manufacturing.
Operational Segmentation and Application Insights
To effectively strategize, businesses must understand how the market is segmented by technology type and application sector. While specific numerical splits are detailed in the full report, the qualitative distribution reveals critical focus areas for investment and sales strategies.
Technology Types
The market is broadly divided into 2D and 3D laser cutting machines. 2D Laser Cutting Machines represent a significant portion of the market, driven by their versatility in sheet metal processing and lower entry costs for standard fabrication tasks. 3D Laser Cutting Machine solutions cater to more complex geometries and specialized industrial requirements, often commanding higher price points and requiring more sophisticated programming and handling systems. The choice between these types depends heavily on the specific manufacturing workflows and the complexity of parts being produced.
Application Verticals
Demand is dispersed across several key industries. General Machinery Processing remains a substantial consumer, utilizing laser cutting for components across various mechanical assemblies. The Automotive Industry is a major driver, particularly with the shift towards electric vehicles requiring precise battery component manufacturing and lightweight structural parts. Home Appliance manufacturing utilizes these machines for high-volume production of cabinets and structural elements. Aerospace and Ship Building represent high-value segments where precision and material integrity are paramount, often justifying the use of advanced high-power systems. Other applications include niche markets that leverage the flexibility of fiber laser technology for custom fabrication.
Regional Expansion and Market Penetration
Geographic dynamics play a crucial role in shaping revenue streams. The market is active across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique challenges and opportunities regarding regulatory compliance, labor costs, and industrial base maturity.
- North America: Characterized by a strong base of automotive and aerospace manufacturers, driving demand for high-precision and automated solutions.
- Europe: A hub for high-technology manufacturing and strict regulatory environments, favoring established players with robust compliance frameworks.
- Asia Pacific: Represents a vast and growing industrial base, with increasing adoption rates driven by infrastructure development and export-oriented manufacturing.
- Latin America and Middle East/Africa: Emerging markets where industrialization efforts are gradually increasing the penetration of advanced cutting technologies.
Strategic expansion in these regions requires tailored approaches. For instance, entering markets in Europe may require navigating CE certification complexities, while growth in Asia Pacific might focus on capacity expansion and local service support networks. The full report provides detailed regional analysis to guide these geographic strategies.
Strategic Implications for Decision Makers
For executives and strategy teams, the insights from this market research translate into actionable intelligence for several key areas.
Capital Investment and Procurement
Understanding the growth trajectory helps in budgeting for equipment upgrades. With the market projected to expand steadily, delaying investment in modern laser cutting technology may result in competitive disadvantages regarding throughput and precision. The data supports justified capital expenditure requests by highlighting efficiency gains and labor savings.
Partner and Vendor Selection
The competitive landscape analysis aids in selecting machinery partners. Companies like IPG Photonics and TRUMPF offer integrated ecosystems, while others may provide specialized components. Knowing the strengths and recent developments of key players allows procurement teams to align vendor capabilities with specific project requirements, such as the need for EV battery component processing or heavy-duty industrial applications.
Risk Management
Awareness of regulatory requirements and supply chain dependencies mitigates operational risk. Ensuring compliance with OSHA, ISO, CE, and FDA/CDRH standards is critical for market access. Additionally, understanding the reliance on rare-earth-doped optical fibers helps in planning for supply chain resilience.
Market Entry and Expansion
For companies looking to enter new geographic markets or application verticals, the segmentation data provides a roadmap. Identifying high-growth areas within General Machinery Processing or Automotive Industry can pinpoint where to allocate sales resources and marketing efforts.
Conclusion: The Value of Comprehensive Intelligence
The fiber laser cutting machines market is at a pivotal juncture. Driven by efficiency mandates, labor constraints, and technological advancements, it offers significant opportunities for those equipped with the right intelligence. However, the complexity of the competitive landscape, regulatory environment, and regional dynamics demands more than surface-level analysis.
PW Consulting's full market research report goes beyond the summary figures. It provides a deep dive into revenue forecasts, detailed segmentation splits by region, type, and application, and a thorough evaluation of the competitive positioning of key players like Bystronic, Coherent, and IPG Photonics. It includes specific data on market concentration, historical trends, and precise forecast numbers that enable robust financial modeling.
To access the complete dataset, including the specific percentage splits, detailed regional revenue figures, and comprehensive profiles of all key companies and their recent developments, stakeholders are invited to explore the full report. This intelligence is designed to empower your organization to make data-driven decisions, optimize supply chains, and capture growth in the evolving landscape of industrial laser cutting.
Invest in clarity. Invest in strategy. Access the full Fiber Laser Cutting Machines Market research today to secure your competitive edge for 2026 and the decade ahead.
For detailed analysis of this topic, please visit the official page: Fiber Laser Cutting Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Drive Shaft Market Hits $9.03B in 2025, Projected to Reach $12.86B by 2032 at 5.2% CAGR
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Automotive Drive Shaft Market: A 2026 Perspective
The automotive drivetrain landscape is undergoing a structural transformation. As propulsion architectures diversify across internal combustion, hybrid, and fully electric platforms, the drive shaft has evolved from a standardized mechanical component into a differentiated engineering asset. For executives navigating procurement, capacity allocation, and portfolio strategy in 2026, understanding the trajectory of this segment requires more than headline figures. It demands a disciplined examination of material substitution, regional demand migration, OEM validation cycles, and the competitive consolidation reshaping the global supply base.
PW Consulting’s latest Automotive Drive Shaft Market research delivers precisely that operational clarity. Built on a six-year historical baseline and extended through a seven-year forecast horizon, the study translates macroeconomic momentum into actionable deployment frameworks. Below is a structured preview of the analytical architecture, the competitive forces at play, and the strategic questions this intelligence is designed to resolve for 2026 decision-makers.
Executive Trajectory: Market Scale, Growth Cadence, and Structural Inflection
The global automotive drive shaft market has demonstrated consistent expansion over the past half-decade, advancing from approximately 6.9 billion USD in 2020 to a projected 9.03 billion USD in 2025. The forward trajectory indicates a moderate but dependable growth cadence, underpinned by a forecast compound annual growth rate of 5.2 percent through 2032. By the close of the outlook period, market revenue is expected to approach the 13 billion USD threshold.
These aggregate movements, however, mask divergent underlying dynamics. Growth is not distributed uniformly across propulsion types, vehicle classes, or geographic corridors. The shift toward high-angle constant velocity assemblies, lightweight tubular geometries, and integrated e-propulsion coupling mechanisms is redefining volume-to-value ratios across the segment. At the same time, material procurement cycles, regional localization mandates, and OEM platform consolidation are introducing volatility that conventional top-down forecasting struggles to isolate. Our analysis disentangles these forces, mapping where incremental revenue will materialize and where margin compression will test incumbent operating models.
What the Study Covers: Operational Architecture and Decision Frameworks
The research is structured to support cross-functional deployment rather than passive reading. Each section translates market signals into executable levers across product planning, supplier qualification, regional capacity allocation, and risk hedging. The core deliverables include:
- Propulsion-Agnostic Demand Mapping: A systematic evaluation of how drive shaft specifications diverge across ICE, hybrid, and electric architectures, with attention to joint integration, torsional load profiles, and NVH tolerance thresholds that influence validation timelines and bill-of-materials complexity.
- Material and Processing Architecture: A detailed assessment of steel, aluminum, and carbon fiber composite adoption pathways, including the cost implications of lightweighting mandates, supply chain readiness, and the price volatility dynamics that can shift component economics by double-digit annual ranges.
- Application and Platform Prioritization: A comparative review of volume concentration in passenger car programs versus commercial vehicle applications, highlighting where platform commonality, fleet turnover cycles, and service interval expectations drive distinct procurement behaviors.
- Regional Momentum and Localization Logic: A ground-up analysis of demand clustering across major automotive corridors, incorporating OEM sourcing shifts, logistics footprint constraints, and policy-driven content requirements without resorting to superficial regional aggregates.
- Competitive Position Assessment: A structured benchmarking of core suppliers across engineering capability, program win rates, vertical integration depth, and propulsion-agnostic portfolio readiness, enabling readers to evaluate partnership options, displacement risk, and pricing leverage.
- Scenario and Sensitivity Frameworks: Forecast bands tied to adoption velocity, raw material escalation, and regulatory efficiency targets, allowing strategy and finance teams to pressure-test capacity plans, inventory policy, and supplier diversification decisions.
Competitive Landscape: Consolidation, Portfolio Realignment, and Propulsion-Agnostic Positioning
The market’s competitive architecture is characterized by moderate concentration, with the top tier holding a combined share just under twenty-five percent and the extended leadership group approaching twenty-six percent. This fragmented-but-consolidating structure means that scale advantages are real but not absolute, and engineering differentiation remains a decisive credential for program retention and new business acquisition.
GKN Automotive, headquartered in Coventry, has reinforced its position through propulsion-agnostic drive systems that span sideshafts, CV joints, and propeller shafts for ICE, hybrid, and electric platforms. Its engineering emphasis on modular joint architecture and integrated propulsion coupling aligns with OEM demands for platform flexibility and reduced validation fragmentation. Nexteer Automotive, based in Auburn Hills, has pursued a complementary trajectory centered on premium telescopic drive shafts, high-angle CV joints, and driveline systems tailored for OEM applications. In April 2026, the company debuted three driveline technologies aimed at EVs and premium driving experiences across propulsion types, underscoring a strategy that links ride refinement and packaging efficiency with electrification requirements.
Dana Incorporated, operating from Maumee, continues to expand its integrated drivetrain portfolio encompassing axles, driveshafts, and e-propulsion systems for passenger vehicles. Its February 2026 reporting of strong first-quarter results accompanied by a new business win in drivetrain solutions reflects an execution model that pairs component supply with systems-level integration. American Axle & Manufacturing, under the Dauch Corporation banner in Detroit, manufactures driveline and metal-forming components including front and rear axles and driveshafts for global OEMs, leveraging high-volume forming capability and broad program coverage.
Hyundai WIA Corporation, based in Seoul, produces driveline systems and components including drive shafts for passenger vehicles and commercial applications, combining regional manufacturing depth with expanding export-oriented program participation. Neapco Holdings, headquartered in Quakertown, supplies driveline components such as driveshafts and CV joints across OEM and aftermarket channels, maintaining a dual-stream revenue structure that buffers pure OEM cycle exposure.
Cardan Shaft Market
The consolidation trajectory remains a defining feature of the competitive outlook. In January 2026, Dauch Corporation announced a combination with Dowlais Group to integrate GKN Automotive driveline technologies, a move that signals the industry’s push toward broader propulsion-agnostic portfolios and consolidated engineering assets. The strategic implication is clear: suppliers that can span multiple propulsion architectures, sustain validation credibility, and offer packaging-efficient joint and shaft solutions are gaining disproportionate relevance in OEM sourcing decisions.
Automotive Drive Shaft Market
Market Dynamics: Material Substitution, Volatility, and Efficiency Mandates
Three structural forces are reshaping specification decisions and cost planning across the drive shaft segment. First, lightweight aluminum and carbon fiber composites are increasingly specified as standard by EV manufacturers to meet efficiency and emissions requirements. This shift is not a wholesale displacement of incumbent materials; rather, it is a selective migration into programs where packaging constraints, range targets, and NVH performance justify higher unit economics. Steel remains the dominant material for drive shafts due to its strength, toughness, and established supply chain, and its prevalence in high-volume and commercial applications continues to anchor baseline procurement logic.
Second, raw material price volatility for steel, aluminum, and composites can increase component costs by up to fifteen percent annually. This volatility transforms material procurement from a tactical purchasing function into a strategic exposure management discipline. Suppliers and OEM buying organizations alike are responding with hedging structures, dual-source qualification, localized processing footprints, and design-to-cost initiatives that decouple performance requirements from raw input swings. Our study quantifies these exposure pathways and maps mitigation playbooks that have proven effective across recent procurement cycles.
Third, regulatory and efficiency mandates are accelerating engineering tradeoffs. As manufacturers pursue tighter efficiency envelopes, the drive shaft’s role in packaging, rotational mass, joint articulation, and propulsion integration becomes more visible in program economics. The result is a market where specification value is increasingly tied to system-level performance rather than component-level commodity pricing. This dynamic favors suppliers that can demonstrate holistic integration benefits, predictable lead times, and design flexibility across propulsion variants.
Implications for 2026 Strategic Decision-Making
For executives operating in 2026, the drive shaft market presents a dual mandate: capture growth where propulsion transitions and platform commonality converge, while insulating the operating model from material volatility and competitive displacement risk. The study is built to support that balance through several decision lenses.
Procurement and supply chain leaders can use the analysis to evaluate supplier resilience, regional sourcing tradeoffs, and exposure to raw material escalation across steel, aluminum, and composite pathways. Product planning teams can leverage propulsion-specific specification mapping to prioritize validation investments, align joint and shaft architectures with platform roadmaps, and avoid over-indexing on legacy ICE configurations that face diminishing program longevity. Commercial and business development teams can use the competitive benchmarking and recent development timeline to identify partnership opportunities, assess program win probability, and anticipate consolidation-driven portfolio shifts.
The study also provides a structured view of where volume concentration is likely to persist and where application-specific differentiation will command pricing discretion. In passenger car programs, the emphasis continues to lean toward packaging efficiency, high-angle articulation, and propulsion integration across a broad model mix. Commercial vehicle applications, by contrast, remain shaped by durability expectations, service interval economics, and platform durability thresholds that influence component specifications and replacement cycles. Understanding these distinctions is essential for allocating engineering resources, negotiating volume commitments, and structuring aftermarket support where relevant.
Regional demand patterns further complicate the strategic picture. Growth is not simply a function of total vehicle production; it is mediated by localization mandates, OEM sourcing footprints, logistics constraints, and the pace at which new propulsion platforms reach volume production in each corridor. The research maps these influences without reducing them to static regional aggregates, instead highlighting where program activity, supplier presence, and content requirements are likely to shift over the forecast period.
Why This Study Matters Now
Market intelligence is only valuable if it converts into decisive action. The Automotive Drive Shaft Market research is designed to do exactly that: convert a broad growth narrative into procurement logic, supplier strategy, capacity planning, and risk hedging that can be discussed in the boardroom and executed on the plant floor. With a historical foundation spanning 2020 through 2025 and a forecast window extending to 2032, the study provides the temporal context needed to distinguish cyclical noise from structural change. The 5.2 percent CAGR trajectory signals dependable expansion, but the strategic value lies in identifying which subsegments, material pathways, and supplier relationships will capture disproportionate share of that growth.
The preview above highlights the analytical architecture, competitive dynamics, and market forces that define the segment’s current trajectory. It is intended to establish the foundation for a deeper evaluation of where your organization should invest, sourcing options worth qualifying, and competitive threats worth modeling before they materialize. The full study delivers the segmented sizing, regional and application-level breakdowns, supplier share context, scenario analyses, and implementation playbooks necessary to translate these conclusions into specific 2026 actions.
For a complete view of the data architecture, competitive benchmarks, and deployment frameworks, download the full PW Consulting Automotive Drive Shaft Market research. The detailed intelligence is structured to support immediate strategic planning, supplier negotiations, and portfolio decisions with the rigor required for a segment in active transformation.
For detailed analysis of this topic, please visit the official page: Automotive Drive Shaft Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Robot Tool Changers to Reach $1,350 Million by 2032 at 13.81% CAGR
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Robot Tool Changers Market: Navigating Growth and Consolidation Through 2032
Market Trajectory and Strategic Context
The global industrial automation landscape is undergoing a structural shift driven by the need for flexible manufacturing systems and rapid production changeovers. At the heart of this transformation lies the robot tool changer market, a critical enabler for maximizing the utility of robotic assets across diverse operational environments. Our latest research provides a comprehensive evaluation of this sector, offering decision-makers a clear view of the momentum building from 2026 through 2032.
Historical data indicates a robust expansion phase. The market revenue grew from 284.67 million USD in 2020 to 543.55 million USD in 2025. This trajectory underscores a sustained demand for modular automation solutions. As we look toward the forecast period, the market is projected to reach 1,350.0 million USD by 2032. This growth path suggests a compound annual growth rate of 13.81 percent, signaling that investment in tool changing infrastructure is no longer optional but a strategic necessity for maintaining competitive agility.
For enterprise leaders, understanding these macro trends is the first step toward effective capital allocation. The acceleration is not uniform across all sectors, however. The research highlights specific drivers that are shaping the demand curve, requiring stakeholders to differentiate between transient trends and fundamental shifts in production methodology. This insight prepares organizations to anticipate supply chain needs and technology integration requirements before market saturation occurs.
Core Report Content and Operational Insights
Our analysis moves beyond simple top-line numbers to provide actionable intelligence on how technology adoption varies across the value chain. The report dissects the market by type, distinguishing between automatic and manual systems. This distinction is vital for assessing operational efficiency. Automatic systems are increasingly favored in high-volume environments where minimizing downtime is paramount. The data suggests that the automatic segment currently holds a significant share of the revenue, reflecting the industrys push toward lights-out manufacturing and reduced human intervention in repetitive tasks.
Conversely, manual tool changers retain relevance in low-volume, high-mix scenarios where flexibility outweighs the need for full automation. Understanding the balance between these two segments allows manufacturers to right-size their investments. The report details the specific payload capacities and compatibility standards that define these categories, ensuring that procurement teams can align hardware specifications with existing robotic fleets.
Application-wise, the research segments the market to reveal where demand is most concentrated. Automotive and electronics industries remain dominant forces, driving volume through complex assembly and handling tasks. However, significant growth potential is identified in sectors such as chemicals, medical, and food and beverage. Each application presents unique challenges regarding hygiene, precision, and safety. By analyzing these verticals separately, the report helps businesses identify adjacent opportunities and benchmark their performance against industry-specific adoption rates.
Robot Tool Changers Market
Regional dynamics also play a crucial role in market access. While developed regions currently account for a substantial portion of revenue, emerging markets are showing increased interest in automation to offset labor constraints. The report provides a geographic breakdown that helps strategists prioritize market entry or expansion efforts based on localized adoption maturity and infrastructure readiness.
Competitive Landscape and Key Players
The market structure is characterized by a high degree of concentration. Our analysis indicates that the top three companies hold approximately 65.5 percent of the market share, while the top five entities command around 78.2 percent. This consolidation implies that partnerships and vendor selection are critical decisions. Switching costs can be high, and compatibility with existing systems often dictates loyalty.
Several key players define the competitive boundaries. Stäubli, headquartered in Switzerland, offers the MPS series automatic robotic tool changers designed for payloads up to 80 kg. Their focus on ISO-standard flange compatibility and modular configurations makes them a strong contender for heavy-duty industrial applications. Meanwhile, Zimmer Group, based in Germany, provides a broader range of solutions including automatic, manual, pneumatic, and magnetic tool changers. Their emphasis on manufacturing flexibility appeals to facilities requiring diverse end-of-arm tooling options.
In the Americas, ATI Industrial Automation, located in North Carolina, specializes in robotic tool changers alongside multi-axis force/torque sensing. This integration of sensing capabilities adds value for applications requiring precise interaction with workpieces. Destaco, also based in the United States, develops cobot end-of-arm tools and manual tool changers with pass-through air and electric ports, catering specifically to the growing collaborative robot segment.
Worldwide Tool Changers Market
European innovation continues with SCHUNK, based in Lauffen am Neckar. They offer the CPS series pneumatically actuated automatic tool changers, which feature an integrated spring for self-retaining capabilities during air-loss scenarios. This safety feature is critical for machine tending automation. Recently, in May 2025, SCHUNK USA promoted this CPS line as a solution for manual changeovers, highlighting the ongoing push to bridge the gap between manual flexibility and automatic efficiency.
Other notable participants include SMC Corporation from Japan, known for pneumatic tool changers and grippers for collaborative robots. Robot System Products, based in Germany, provides the CoboShift tool changer family with automated exchange capabilities for collaborative robots. SmartShift Robotics, based in the United States, offers a universal tool changer system designed for fast deployment and redeployment. The presence of these specialized players indicates a mature market where differentiation often comes through niche capabilities, ease of integration, or specific regional support networks.
Market Dynamics and Regulatory Influence
External factors are exerting significant pressure on market dynamics. Regulatory standards are evolving to ensure safety as robot integration becomes more pervasive. The update to ISO 10218-2 in 2025 establishes new global safety requirements for industrial robot systems and integration. Compliance with these standards is essential for manufacturers deploying tool changers in multi-robot cells or shared workspaces. In the United States, ANSI/RIA R15.06-2012 Part 2 remains the key standard for integrating robot systems into completed machinery applications. Keeping abreast of these regulatory frameworks is vital for risk management and market access.
Supply chain considerations are also reshaping the landscape. Recent analysis from 2025 suggests that U.S. tariff policies are prompting localized supply chain adjustments among major manufacturers of robotic components. This shift may influence pricing strategies and lead times for hardware procurement. Companies are increasingly evaluating the origin of components and the resilience of their supply networks. This dynamic creates an opportunity for regional manufacturers to capture market share by offering reduced logistics friction and compliance with local content requirements.
Technological evolution continues to drive demand. The integration of sensor technology and smart connectivity into tool changers allows for predictive maintenance and real-time monitoring of tool status. As Industry 4.0 initiatives mature, the data generated by these components becomes part of the broader digital twin ecosystem. Organizations that invest in compatible hardware today are better positioned to leverage data analytics for optimization tomorrow.
Strategic Recommendations for 2026 Decision Makers
Based on the comprehensive data and analysis presented in our full report, we recommend several strategic actions for stakeholders planning their 2026 initiatives.
- Evaluate Total Cost of Ownership: When selecting between automatic and manual solutions, decision-makers should look beyond initial purchase price. Consider the downtime savings, labor reduction, and error minimization offered by automatic systems in high-volume contexts.
- Assess Vendor Concentration Risk: Given the high market concentration among top players, diversifying supplier relationships or ensuring robust support contracts with primary vendors is advisable to mitigate supply chain disruptions.
- Monitor Regulatory Compliance: Ensure that all tool changing hardware and integration plans align with the latest ISO and ANSI standards. Non-compliance can lead to operational delays and safety liabilities.
- Explore Adjacent Markets: While automotive and electronics are core drivers, the growth in medical and food and beverage sectors presents opportunities for specialized tool changer solutions that meet stringent hygiene and precision standards.
- Prepare for Supply Chain Shifts: Factor in potential changes related to localization trends and tariff impacts. Engaging with suppliers who have adapted their logistics networks can provide a competitive advantage in cost and reliability.
The robot tool changers market is poised for significant expansion. The interplay between automation demand, regulatory evolution, and competitive consolidation creates a complex environment. Organizations that leverage deep market intelligence will be better equipped to navigate these dynamics, secure reliable supply chains, and optimize their automation investments for the decade ahead.
For a detailed breakdown of regional forecasts, specific application growth rates, and comprehensive competitor profiling, we invite you to access the full report. The complete intelligence contained within our research provides the granularity required to finalize strategic plans and execute with confidence in the 2026-2032 period.
For detailed analysis of this topic, please visit the official page: Robot Tool Changers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Diesel Fuel Injection Systems Market Rises 5.5% CAGR to $109.4B by 2032
By pmarketresearch, 2026-09-15
Navigating the Diesel Fuel Injection Systems Market: Strategic Intelligence for 2026 and Beyond
The global automotive and heavy machinery sectors are undergoing a period of profound transformation. As emission regulations tighten and performance expectations rise, the diesel fuel injection systems market remains a critical battleground for original equipment manufacturers (OEMs) and tier-one suppliers. At PW Consulting, we understand that access to precise, forward-looking data is not merely an academic exercise—it is a prerequisite for survival and growth in a volatile landscape. Our latest comprehensive market research report, covering the trajectory from 2026 through 2032, offers an unflinching look at the forces shaping this industry.
This document serves as an introduction to the depth of analysis contained within our full study. While we provide a high-level overview of the market's trajectory and the key players defining the competitive arena, the specific granular data required to build detailed financial models or supply chain strategies is reserved for our clients. The following insights highlight the strategic value of this research, demonstrating why industry leaders rely on PW Consulting to navigate the complexities of diesel fuel injection technologies.
Market Trajectory and Macroeconomic Context
Understanding the broader market currents is essential for strategic planning. Our analysis covers historical performance from 2020 through 2025, establishing a baseline against which future growth is measured, and extends a robust forecast through 2032. This longitudinal view allows stakeholders to distinguish between temporary fluctuations and structural shifts in demand.
The market has experienced a period of contraction in the immediate historical past, reflecting broader economic adjustments and shifts in mobility patterns. However, the forecast period indicates a decisive turnaround. Starting from a base valuation in 2025, the market is projected to regain momentum, driven by renewed investment in heavy-duty transportation and off-highway machinery. The compound annual growth rate (CAGR) anticipated for the forecast period stands at 5.5 percent, signaling a steady recovery and expansion phase.
By 2032, the total market valuation is expected to surpass previous historical highs, reaching new milestones in revenue terms denominated in USD millions. This growth trajectory is not linear; it is shaped by technological adoption rates, regulatory compliance costs, and regional industrial output. For decision-makers, recognizing the timing of this recovery is crucial. Investing too early in capacity without demand validation carries risk, while waiting too long may cede market share to competitors who have anticipated the upturn. Our report details the inflection points where these risks are minimized, providing a timeline for capital allocation and product development.
Technological Segmentation and Application Dynamics
The diesel fuel injection landscape is defined by distinct technological pathways, each serving specific engine requirements and emission standards. The market is primarily segmented by type, with Common Rail systems dominating the landscape due to their precision and efficiency advantages. This segment continues to leverage advancements in high-pressure operation, with systems now operating at pressures exceeding 2,500 bar to meet stringent emission norms. Alongside Common Rail, Unit Injectors and other specialized types maintain significant presence in specific heavy-duty and niche applications where durability and specific torque characteristics are prioritized.
Application-wise, the market is bifurcated between passenger cars, commercial vehicles, and off-highway vehicles. While passenger cars have historically been a major driver, the commercial vehicle sector remains a cornerstone of revenue stability, particularly as logistics networks demand higher efficiency. Off-highway vehicles, including mining and agricultural machinery, represent a critical growth vector, driven by the need for power density and fuel economy in harsh operating environments.
Our research delves deeply into the performance metrics of these segments without exposing the sensitive percentage splits that constitute our proprietary intelligence. We analyze the interplay between injector technology and engine management systems, highlighting how advancements in piezo injectors and solenoid valves are enabling faster actuation times and finer fuel metering. Furthermore, we examine the material science aspects, noting the reliance on high-performance steels and alloys capable of withstanding operating pressures up to 2,700 bar. This technical granularity is vital for suppliers evaluating their manufacturing capabilities against future product requirements.
Competitive Landscape and Key Player Strategies
The competitive environment in the diesel fuel injection systems market is characterized by a mix of established automotive giants and specialized component manufacturers. Market concentration remains moderate, indicating room for strategic maneuvering while acknowledging the dominance of key firms. Our report provides detailed profiles of the leading companies that are setting the pace for innovation and market capture.
Bosch, headquartered in Germany, continues to be a formidable force, manufacturing common-rail diesel fuel injection systems with piezo injectors operating up to 2,700 bar. Their comprehensive approach includes pumps and full fuel supply solutions for passenger cars, light commercial, and heavy-duty vehicles, ensuring a holistic value proposition for OEMs. Similarly, Denso Corporation from Japan supplies i-ART common rail fuel injection systems for medium- and large-sized vehicles. Their technology focuses on pressures up to 2,500 bar and the integration of SCR/DPF controls, demonstrating a commitment to low-emission performance through systemic integration.
In the United States, PHINIA produces DFI1 and DFI2 families of diesel fuel injectors for light- and medium-duty engines up to 250 kW. They also supply high-pressure diesel pumps and rails, supporting emissions standards through 3,000 bar operation. Their recent strategic moves indicate a focus on future-proofing their portfolio. BorgWarner, also based in the United States, provides diesel fuel injection systems including EUI and DFi7 injectors for heavy-duty trucks and passenger cars, plus PLD systems. Their positioning was significantly strengthened following the 2020 acquisition of Delphi Technologies, allowing them to broaden their technological reach.
Cummins Inc. offers Common Rail Fuel Systems and a Modular Common Rail Fuel System (MCRS) with ultra-fast actuated injectors and dual-stage pumps, delivering up to 2,600 bar for heavy-duty and mining engines. Their systems boast verified efficiency gains, a critical metric for commercial fleet operators. These companies represent the vanguard of the industry, and our report analyzes their recent developments to predict future market shifts.
Recent Developments and Strategic Implications
To navigate the market effectively, one must understand the immediate actions taken by these key players. Recent industry activity provides a window into where competitive advantages are being built. In April 2026, PHINIA announced plans to unveil 500bar+ fuel injection and alternative fuel innovations at Auto China 2026. This event underscores a strategic pivot towards supporting OEMs for future emissions standards while exploring diversification beyond traditional diesel platforms. Such announcements signal to the market that the boundaries of injection technology are expanding, and suppliers must adapt their roadmaps accordingly.
Meanwhile, Cummins Inc. demonstrated a focus on upgrading existing infrastructure. In June 2025, Cummins launched Modular Common Rail Fuel System (MCRS) upgrade kits for QSK60 and QSK78 engines. These kits convert legacy HPI systems with ultra-fast injectors and increased accumulator volume. This strategy highlights a significant market opportunity: the retrofitting and modernization of existing engine fleets to meet new efficiency and emission targets without requiring complete engine replacements.
These developments are not isolated incidents; they are indicative of broader industry trends. Our report contextualizes these moves within the larger framework of market evolution, helping clients understand whether to invest in new platform development or leverage upgrade paths to capture value from legacy assets.
Regulatory Pressures and Industry Dynamics
No analysis of the diesel fuel injection market is complete without addressing the regulatory environment. Compliance is no longer optional; it is the primary driver of technology adoption. Heavy-duty engines must meet EPA and Euro emission standards, which require optimized fuel injection timing and quantity alongside aftertreatment systems. The US EPA enforces nonconformance penalties for on-highway heavy-duty engines where fuel injection and EGR systems fail to achieve optimized emissions compliance. These regulatory facts create a hard ceiling for performance and a strict floor for compliance, dictating the minimum technical specifications for any market entry or product update.
Diesel Common Rail Injection System Market
Furthermore, the reliance on specific raw materials introduces supply chain volatility. Diesel fuel injection components such as injectors and rails use high-performance steels and alloys to withstand operating pressures up to 2,700 bar. Fluctuations in the availability or cost of these materials can impact manufacturing margins and lead times. Our research incorporates these dynamics into the forecast, offering scenarios that account for regulatory tightening and material cost variations. By understanding these constraints, companies can build more resilient supply chains and negotiate better terms with material suppliers.
The Strategic Value of Proprietary Intelligence
While the overview provided here outlines the general direction of the diesel fuel injection systems market, the true utility of our research lies in the details that cannot be publicly disclosed. Strategic decision-making requires precise revenue figures, specific regional growth rates, and detailed segmentation splits that reveal hidden opportunities. Publicly available data often lags behind real-time market shifts and lacks the granularity needed for operational planning.
Our full report offers actionable intelligence on the specific share of each region, the exact revenue contribution of each application segment, and the precise market concentration metrics that define competitive intensity. We analyze the interplay between regional industrial policies and local demand-supply gaps, providing a roadmap for market entry or expansion. We also quantify the impact of technological transitions on revenue streams, allowing R&D departments to prioritize projects with the highest return on investment.
For executives and strategy teams, the difference between a good decision and a great one often comes down to the quality of information. Access to our complete dataset eliminates guesswork. It allows you to validate assumptions about market size, verify the feasibility of capacity expansions, and benchmark your performance against the aggregated data of the industry's top players. The 5.5 percent CAGR and the projected market size by 2032 are headline figures, but the path to capturing that growth is nuanced and requires the depth of analysis only our full report provides.
Conclusion: Positioning for Future Growth
The diesel fuel injection systems market is at a pivotal juncture. The convergence of regulatory pressure, technological innovation, and recovering market demand creates a complex environment for stakeholders. Companies that can navigate the technical requirements of high-pressure systems, adapt to regulatory changes, and anticipate competitor moves will secure a dominant position.
PW Consulting's Diesel Fuel Injection Systems Market report is designed to be the cornerstone of that strategy. By synthesizing historical data, forward-looking forecasts, and deep competitive analysis, we provide the clarity needed to act with confidence. We invite industry leaders to leverage this intelligence to refine their strategies, optimize their portfolios, and capture the value available in the forecast period through 2032.
To access the complete dataset, including detailed segmentation values, regional breakdowns, and comprehensive company profiles with strategic recommendations, we encourage you to explore the full report. The competitive advantage lies in the details, and those details are available to partners ready to invest in superior market intelligence.
Diesel Fuel Injection Systems Market
For detailed analysis of this topic, please visit the official page: Diesel Fuel Injection Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lithium Ion Battery Market Hits $325.77M in 2025, Forecasts 17.52% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Decisive Decade: Inside the 2026 Global Lithium-Ion Battery Market Research
The lithium-ion battery industry has transitioned from a phase of rapid, speculative expansion into a mature, capital-intensive arena where competitive advantage is dictated by supply chain resilience, technological precision, and strategic foresight. For executive teams navigating capital allocation, product roadmaps, and geographic positioning, the margin for strategic missteps has narrowed considerably. PW Consulting is proud to introduce our latest comprehensive analysis of the global Lithium-Ion Battery Market, a diagnostic framework engineered specifically to equip leadership teams with the operational clarity required to make high-conviction decisions throughout 2026 and beyond.
Lithium-ion Battery Recycling Market
Over the past half-decade, the sector has consistently demonstrated a compound annual growth trajectory of 17.52 percent, with market valuation crossing the 325.77 million USD threshold in 2025 and continuing its upward march toward a projected 663.71 million USD by 2032. These figures, however, represent only the surface architecture of a profoundly intricate ecosystem. Behind the headline metrics lies a competitive matrix defined by intensifying vertical integration, divergent cathode CHEMISTRY adoption curves, shifting regulatory guardrails, and raw material supply chains that remain both critical and structurally fragile. Our research moves decisively past superficial valuation models to deliver an actionable, execution-ready intelligence architecture that maps market velocity against real-world operational complexity.
Decoding Market Architecture for Executive Decision-Making
At the strategic core of this study lies a granular examination of the competitive and operational forces that will determine enterprise profitability over the forecast horizon. We have systematically mapped the primary commercial pathways across multiple critical dimensions, tracing how chemistry selection, end-use case prioritization, and regional deployment patterns are actively reshaping competitive positioning. Rather than offering static snapshots, the analysis treats these variables as dynamic levers, providing a contextual framework that executives can stress-test against internal capacity rollouts, procurement strategies, and partnership pipelines. This structure is deliberately designed to answer the strategic questions that typically surface during quarterly planning cycles: where will demand actually concentrate, which manufacturing pathways offer sustainable margin defense, and how should organizations hedge against supply-side volatility without compromising long-term growth targets.
Our methodological framework also integrates forward-looking scenario modeling, allowing leadership to evaluate multiple deployment trajectories under varying macroeconomic and policy conditions. By synthesizing historical performance data with emerging market signals, the report delivers a structured lens for capital allocation, R&D prioritization, and market-entry timing. The objective is not simply to forecast where the industry is heading, but to equip decision-makers with the analytical rigor required to navigate ambiguity, reallocate resources efficiently, and secure first-mover advantage in high-growth corridors before competitive saturation sets in.
What the Full Report Delivers: Operational Depth and Strategic Clarity
Leaders evaluating this intelligence should expect an end-to-end operational blueprint rather than a conventional market summary. The complete publication dissects the competitive hierarchy, technology transition vectors, manufacturing footprint evolution, and demand-side procurement behaviors across every major value chain node. The report is structured to support cross-functional alignment, enabling strategy teams, engineering leadership, procurement directors, and investor relations stakeholders to operate from a shared factual baseline.
Key analytical pillars embedded in the full study include:
- Segmentation Deep Dives: A structured evaluation of chemistry pathways, application-driven demand clusters, and regional deployment sequences, revealing where pricing power, capacity utilization, and supply chain leverage are being actively consolidated.
- Detailed profiling of the market's most influential manufacturers, with emphasis on vertical integration strategies, cell-format specialization, and regional manufacturing investments that are actively reshaping the industry's center of gravity.
- Forward-looking assessments of material availability, cell-design evolution, and commercialization timelines, providing the strategic context needed to anticipate bottlenecks, secure procurement windows, and align product roadmaps with credible development trajectories.
- An integrated review of emerging compliance frameworks and transport constraints that directly affect global distribution, inventory planning, and cross-border partnership design.
- A multi-horizon projection architecture that enables leadership to model capacity expansion, demand elasticity, and competitive response under baseline and stress-case assumptions.
Each analytical layer is designed to translate complex industry signals into explicit, boardroom-ready implications. Readers will leave with a defined understanding of which strategic moves will compound value over the forecast window and which legacy assumptions are increasingly misaligned with the evolving market structure.
Competitive Dynamics: The Strategic Moats Being Forged Today
The competitive architecture of the lithium-ion battery sector is no longer defined solely by cell performance metrics. Today's winning organizations are those executing multi-vector strategies that combine manufacturing scale, chemistry agility, geographic positioning, and ecosystem partnerships. The full report profiles the industry's most influential incumbents, examining how each is engineering defensible advantages in an increasingly polarized environment.
Several strategic archetypes have emerged clearly. Leading cell manufacturers with full vertical integration from raw materials through system-level deployment are leveraging control over the upstream value chain to stabilize margins and accelerate development cycles. At the same time, specialized producers focused on distinct form factors, such as high-performance prismatic or cylindrical cells, are deepening their alignment with premium automotive programs and specialized storage applications. Other organizations are differentiating through chemistry emphasis, whether advancing high-nickel formulations for energy-dense mobility use cases or scaling LFP-based platforms that prioritize safety, cycle life, and cost predictability. The competitive tension between these approaches is intensifying, and understanding where each player is investing, partnering, and defending is essential for any enterprise seeking to position itself intelligently within the value chain.
The pace of recent activity underscores how rapidly the landscape is being reconfigured. Strategic contract awards, product platform unveilings, cross-industry partnerships, and major capacity expansions are actively reshaping regional supply balances and customer relationships. These developments are not isolated headlines; they signal durable shifts in manufacturing geography, program partnerships, and technology commercialization priorities. Our research contextualizes these moves within broader competitive dynamics, helping leaders distinguish between tactical positioning and structural advantage, and enabling them to anticipate which partnerships, capacity corridors, or technology bets will define the next cycle of consolidation and growth.
Lithium Ion Battery Market
Macro Forces and Operational Realities Shaping the 2026–2032 Window
No strategic assessment of this market is complete without a realistic engagement with the external forces that constrain and enable growth. The full study integrates several macro-level dynamics that executives must factor into scenario planning and operational design. On the materials side, lithium availability and pricing remain central variables. Worldwide production expanded meaningfully during the most recent reporting cycle, reflecting the sector's relentless demand pull, while domestic pricing patterns for battery-grade inputs have experienced measurable fluctuation across the year. These movements carry direct implications for procurement strategy, contract structuring, and manufacturing cost models. Organizations that treat raw material exposure as a static risk item rather than a dynamic variable risk mispricing their product pipelines and underinvesting in supply diversification.
Regulatory and logistics frameworks are equally consequential. From the outset of 2026, stricter transport constraints have governed the shipment of lithium-ion batteries and battery-powered equipment, imposing new limits on state of charge for air transport and prompting necessary adjustments in global distribution logic, inventory positioning, and fulfillment design. Simultaneously, policy-driven standards are accelerating technology commercialization roadmaps in key development centers, establishing formal benchmarks for next-generation battery architectures and influencing R&D prioritization across the industry. These regulatory signals are not peripheral; they actively shape where and how manufacturers scale, which form factors gain commercial traction, and how quickly advanced chemistry pathways can move from prototype to production.
Compounding these forces is the broader reality of a market that remains highly concentrated at the top. A relatively small group of leading enterprises continues to command a substantial share of global revenue, reinforcing the strategic importance of partnership selection, supplier diversification, and differentiated value propositions for organizations operating outside the dominant tier. For entrants, joint venture participants, and downstream integrators, understanding the barriers to scale and the leverage points available within an asymmetric competitive structure is critical to designing realistic growth strategies.
Why This Research Is a Strategic Imperative for 2026 Decision-Makers
The global lithium-ion battery market will not reward passive observation. As capacity expansions proceed, chemistry portfolios diverge, supply chains recalibrate, and policy regimes tighten, the organizations that thrive will be those capable of converting market intelligence into timely operational action. This publication has been designed to serve as that conversion mechanism. It provides the evidentiary foundation needed to validate capital deployment assumptions, prioritize technology partnerships, anticipate procurement exposure, and refine market-entry or expansion strategies with greater confidence.
More importantly, the study is structured to be actively used rather than passively read. Cross-functional teams can leverage its frameworks to align on strategic priorities, risk officers can map exposure against documented market trajectories, and commercial leaders can identify where demand momentum is genuinely forming versus where narrative outruns fundamentals. In an environment where competitive windows are narrowing and capital efficiency is increasingly scrutinized, the difference between a reactive posture and a proactive one often comes down to the quality and immediacy of the intelligence at hand.
To access the complete segmentation analysis, full competitive profiles, scenario projections, and operational recommendations that will inform your 2026 strategy, we invite you to explore the full report suite on our platform. The macro trajectory is clear; the actionable detail that separates informed execution from speculation is available in the complete publication.
For detailed analysis of this topic, please visit the official page: Lithium Ion Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com