

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: First Aid Kits Market Hits $215M in 2025, Projected 4.2% CAGR to 2032
By pmarketresearch, 2026-09-15
The First Aid Kits Market in 2026: A Strategic Imperative for Resilient Operations
As organizational risk profiles evolve and regulatory frameworks tighten, the first aid kits market has transitioned from a basic compliance accessory to a strategic component of operational resilience. The sector has demonstrated steady expansion over the past half-decade, with total market revenue rising from approximately 163.15 million USD in 2020 to an estimated 215.0 million USD in 2025. This trajectory reflects not only baseline demand but a structural shift in how workplaces, public institutions, and private consumers approach injury preparedness. Looking ahead, the forecast period from 2026 through 2032 indicates continued growth, with revenue projected to reach 227.94 million USD in 2026 and progress toward 284.0 million USD by 2032, underpinned by a compound annual growth rate of 4.2 percent. For executive teams, procurement leaders, and product strategists, these figures do more than describe a market. They signal where compliance obligations, supply chain risk, and consumer expectations are converging.
PW Consulting's latest First Aid Kits Market research study is designed to translate this momentum into actionable intelligence. Rather than offering a static snapshot, the report provides a decision-ready architecture that helps organizations anticipate supply disruptions, navigate evolving safety standards, and position their offerings within a consolidating competitive field. This article previews the strategic themes, structural dynamics, and operational implications embedded in the full study, while deliberately leaving the granular segmentation data for the complete report. The objective is simple: demonstrate the depth of the analysis so that decision-makers understand exactly what they will gain by examining the full market intelligence package.
From Steady Growth to Strategic Necessity: The 2026 Market Backdrop
The historical record from 2020 through 2025 shows a market that has grown with notable consistency, moving from 170.51 million USD in 2021 to 175.81 million USD in 2022, then to 184.71 million USD in 2023 and 199.12 million USD in 2024. Each year reflects a compounding set of pressures: heightened workplace safety awareness, broader institutional procurement of emergency preparedness supplies, and a consumer base increasingly attentive to home and recreational safety. By 2025, the market reached 215.0 million USD, establishing a base from which the 2026 estimate of 227.94 million USD emerges.
What makes this progression strategically meaningful is not the absolute size of the market, but the forces shaping its composition. Between 2023 and 2025, prices for medical-grade gloves, antiseptic consumables, and trauma care materials increased by nearly 18 percent. This rise was driven by supply concentration in Asia and elevated freight costs, exposing the sector to input cost volatility that ripples directly into kit pricing, replenishment economics, and margin structures. At the same time, regulatory updates have begun to redefine what qualifies as a compliant kit, forcing manufacturers and distributors to reconsider product specifications, quality documentation, and production controls. The result is a market where growth is real but uneven, and where competitive advantage depends on how well firms manage cost pressure, regulatory alignment, and product differentiation simultaneously.
Regulatory Evolution and Supply Chain Pressure in the Current Landscape
The operational context for first aid kits in 2026 is defined by a convergence of regulatory and sourcing dynamics. The Quality Management System Regulation, known as QMSR, became effective on February 2, 2026. This regulation amended the device current good manufacturing practice requirements under 21 CFR part 820 and incorporated ISO 13485:2016 by reference as the core quality framework. In practical terms, it aligns FDA quality expectations for medical devices, including first aid kits, with an internationally recognized quality management standard. For market participants, this is more than a compliance footnote. It reshapes documentation requirements, production governance, and the burden of demonstrating consistency across batches and product lines.
First Aid Kits Market
At the same time, regional standards activity is adding further specificity. A Standards Board First-Aid Public Hearing Notice proposed revisions to sections 1512 and 3400 in California, effective for 2026 compliance, requiring first-aid kits to meet ANSI/ISEA Z308.1-2021 Class A specifications. Such moves signal a broader direction in which minimum content expectations, classification rules, and workplace readiness requirements are becoming more explicit. Organizations that rely on generic or outdated kit configurations may find themselves exposed to compliance gaps, procurement rework, or reputational risk.
These regulatory shifts intersect with the cost pressures already noted. When input prices accelerate and manufacturing standards tighten at the same time, the margin for error narrows. Kit assemblers and distributors must reconcile higher material costs with the expectation of stable pricing in many procurement categories. This tension is one of the central dynamics examined in the full report, where the interplay between cost structure, product design, and regulatory readiness is mapped not as a theoretical concern but as a practical constraint on growth and profitability.
A Competitive Landscape Shaped by Specialization and Consolidation
The first aid kits market is not fragmented in the sense of being unstructured. It features a meaningful degree of concentration, with the top three competitors accounting for approximately 42.5 percent of market revenue and the top five reaching roughly 58.7 percent. Such concentration implies that scale, brand trust, distribution reach, and service models matter significantly. It also suggests that smaller or more specialized players must compete on precision, compliance credibility, or niche application expertise rather than on broad volume alone.
Several established players illustrate the diversity of strategic positioning now present in the market. First Aid Only, based in Shelton, United States, has built its offering around cost-effective, OSHA-compliant workplace first aid kits and refills, emphasizing practical compliance and replenishment economics. The American Red Cross focuses on ANSI/OSHA-compliant workplace, industrial, and construction first aid kits, leveraging institutional trust and a recognized safety brand. North American Rescue addresses a more specialized segment with trauma and first aid kits, including lumbar first aid kits and public access bleeding control kits, appealing to users who prioritize advanced response capability. Aero Healthcare takes a different route by concentrating on wholesale first aid kits, private-label and contract manufacturing, and managed rental and restocking systems, which positions it as a service-oriented partner rather than a pure product vendor. My Medic targets premium first aid kits and supplies selected by first responders and medical professionals, structuring its offering around expert-endorsed product selection. Cintas Corporation provides first aid kits, cabinets, and replenishment services for workplace use, integrating kits into a broader workplace safety and maintenance ecosystem. JumpMedic rounds out the field with premium first aid kits and supplies designed for emergency needs, emphasizing readiness for urgent scenarios.
This mix of strategies reveals a market in which competitive advantage is increasingly derived from how well a company aligns product content, compliance positioning, distribution model, and customer service. Some competitors win through brand authority and institutional relationships. Others compete through specialized trauma capability, premium product curation, or managed replenishment services that reduce the administrative burden for workplaces. The full report examines these positioning choices in greater depth, including the implications for market share movement, partnership opportunities, and customer acquisition logic across different end-use environments.
What the Full Study Delivers: Decision-Ready Analysis Across Market Structure, Segmentation, and Strategy
PW Consulting's First Aid Kits Market research is structured to support practical decision-making rather than abstract observation. The study covers historical performance and forecast trajectories across the 2026 to 2032 period, anchoring the analysis in a base year of 2025 and drawing on historical data from 2020 through 2025. Revenue is presented in million USD, allowing executive readers to assess absolute scale and growth momentum without losing sight of the operational meaning behind the numbers.
A major strength of the report is its segmentation architecture, which breaks the market down by region, by type, and by application. This structure helps clients understand where demand is concentrated, which product categories are driving value, and how different use environments shape procurement behavior. The segmentation analysis is paired with a competitive assessment that examines the strategies, offerings, and positioning of leading market participants. Rather than simply listing companies, the report interprets how their product lines, service models, and compliance approaches influence market dynamics and what they reveal about shifting customer expectations.
The study also integrates regulatory and supply-side intelligence into the market narrative. Instead of treating standards and input costs as external noise, the report connects them to product design, margin management, and market entry considerations. This is especially relevant given the 2026 enforcement of the Quality Management System Regulation and the broader movement toward more specific content requirements in certain jurisdictions. By mapping how these changes affect manufacturing, documentation, and procurement, the report gives clients a basis for scenario planning and risk mitigation.
In addition, the report addresses recent industry developments that shape near-term decision-making. It incorporates the February 2026 regulatory updates associated with the Quality Management System Regulation and the proposed California standards revisions tied to ANSI/ISEA Z308.1-2021 Class A specifications. It also reflects the cost pressures observed between 2023 and 2025 for medical-grade gloves, antiseptic consumables, and trauma care materials, linking these trends to broader questions about sourcing strategy, pricing resilience, and supplier concentration. Together, these elements provide a multi-layered view of the market that is meant to support strategy, procurement, and product planning in parallel.
Why This Research Matters for 2026 Decision-Making
For organizations operating in or adjacent to the first aid kits market, the strategic question in 2026 is not whether demand exists, but how to respond to a market that is growing while becoming more complex. The combination of steady top-line expansion, rising input costs, tighter quality expectations, and a concentrated competitive structure means that generic strategies are increasingly insufficient. Companies need clarity on where value is being created, which compliance obligations will shape purchasing decisions, and how service models such as managed restocking or private-label manufacturing can change the economics of participation.
This is where the full PW Consulting report adds value. It gives decision-makers a structured foundation for evaluating market entry, portfolio expansion, product specification upgrades, and supplier relationships. It helps procurement teams anticipate cost behavior and compliance shifts rather than reacting to them after the fact. It helps commercial leaders understand the competitive logic of incumbents and identify where differentiation is still possible. And it helps investors and advisors assess the market's resilience, concentration dynamics, and sensitivity to regulatory change.
The preview presented here is intentionally selective. It establishes the analytical direction, the operational themes, and the strategic relevance of the study, while leaving the detailed regional, typological, and application-level breakdowns for the complete publication. Those details are where the research becomes directly operational: they reveal the relative weight of different demand centers, the segmentation logic behind product mix decisions, and the specific competitive pressures that vary across use cases. For teams that need to move from awareness to action, the full report is the necessary next step.
Worldwide Antiseptic First Aid Liquid Market
Conclusion: Turning Market Momentum into Informed Strategy
The first aid kits market in 2026 is defined by a rare combination of stability and disruption. Revenue has grown consistently from 163.15 million USD in 2020 to an estimated 215.0 million USD in 2025, with forecasts pointing toward 227.94 million USD in 2026 and a 4.2 percent CAGR through 2032. At the same time, regulatory alignment under the Quality Management System Regulation, proposed state-level specification changes, and nearly 18 percent increases in key input prices are reshaping the operating environment. In such a market, the winners are likely to be those who treat first aid kits not as commoditized compliance items, but as part of a broader safety, service, and risk-management strategy.
PW Consulting's First Aid Kits Market research is built for that moment. It combines macro-level market sizing, segmentation structure, competitive analysis, and regulatory context into a single decision-oriented framework. The full study provides the depth required to translate these dynamics into concrete choices about product specification, sourcing, positioning, and growth planning. For executives and strategy teams seeking to act with confidence in 2026 and beyond, the complete report offers the detailed intelligence needed to move beyond surface-level trends and into strategic execution.
For detailed analysis of this topic, please visit the official page: First Aid Kits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plastic Pallets Market to Hit $9.67B by 2032 at 6.68% CAGR
By pmarketresearch, 2026-09-15
Navigating the Plastic Pallets Market: Strategic Insights for 2026 and Beyond
The global logistics infrastructure is undergoing a quiet but profound transformation, driven by imperatives in sustainability, supply chain resilience, and regulatory compliance. At the heart of this shift lies the plastic pallets market, a critical component of modern material handling. As enterprises plan their capital allocation and operational strategies for 2026, understanding the trajectory of this market is no longer optional—it is a strategic necessity.
In this comprehensive analysis, PW Consulting presents our latest market research on the Plastic Pallets Market. This report is designed to equip decision-makers with the granular intelligence required to navigate a landscape defined by steady growth, evolving material science, and shifting regulatory frameworks. The following overview outlines the core macro trends, competitive dynamics, and strategic imperatives that will define the sector through the forecast period ending in 2032.
Market Trajectory and Growth Outlook
The plastic pallets market has demonstrated remarkable resilience over the past half-decade, recovering from minor fluctuations to establish a robust growth trajectory. Our analysis of historical data from 2020 through 2025 reveals a market that has consistently expanded its value base, culminating in a significant valuation at the base year. This momentum is projected to accelerate as we move into the forecast period of 2026 to 2032.
The market is expected to grow from its 2026 valuation to nearly double that figure by the end of the forecast window, driven by a compound annual growth rate (CAGR) that underscores the sector's long-term viability. This growth is not merely a reflection of increased trade volumes but is deeply rooted in the structural advantages plastic pallets offer over traditional wood alternatives. Key drivers include the global push toward circular economy principles, the need for hygienic storage solutions in sensitive industries, and the inherent durability of plastic substrates that allow for repeated use cycles.
For strategic planners, this growth curve signals more than just revenue potential; it indicates a maturing market where efficiency and differentiation will become the primary battlegrounds. The transition from 2025 to 2032 represents a critical window for investment in supply chain infrastructure, where early adopters of optimized plastic pallet solutions can secure significant operational cost advantages.
Strategic Segmentation and Material Dynamics
Understanding the market requires a deep dive into the segmentation that defines customer choices and manufacturer capabilities. The market is primarily bifurcated by material type, with high-density polyethylene (HDPE) and polypropylene (PP) dominating the landscape. These materials are not merely commodities; they represent distinct value propositions regarding strength, weight, chemical resistance, and recyclability.
Our report provides an intricate analysis of how these material segments are performing relative to end-user demands. HDPE continues to hold a substantial share, favored for its robustness and widespread availability, while PP is gaining traction in specific applications requiring higher temperature resistance or different mechanical properties. Beyond these primary resins, the market also explores niche materials that cater to specialized industrial needs. A critical trend within this segmentation is the increasing incorporation of recycled content. Suppliers are increasingly offering options with significant recycled HDPE content, responding to both regulatory pressure and corporate sustainability mandates. This shift toward recycled feedstocks is reshaping cost structures and supply chain dependencies, making raw material sourcing a strategic consideration for procurement leaders.
Application-wise, the market serves a diverse array of industries. Food and beverage logistics remain a cornerstone, driven by stringent hygiene requirements and the need for traceable, durable transport units. The pharmaceutical sector similarly relies on plastic pallets for contamination control and cleanliness. Chemicals and general industrial applications also contribute significantly to demand, each with unique performance criteria. The report details how these application segments interact with material choices and regional supply chains, offering a nuanced view of where growth opportunities are concentrated without exposing the specific financial allocations that constitute our proprietary intelligence.
Regulatory Landscape and Compliance Imperatives
In 2026, regulatory compliance is a pivotal force shaping market dynamics. One of the most significant developments is the update to fire safety standards regarding plastic pallets in storage environments. Recent guidance from the National Fire Sprinkler Association (NFSA) highlights critical distinctions in how unreinforced versus reinforced plastic pallets affect commodity classification in high-piled combustible storage.
Specifically, unreinforced plastic pallets can increase the commodity classification by one class, while reinforced variants may increase it by two classes, potentially pushing storage groupings into higher hazard categories. Furthermore, the NFPA 13 (2025 edition) now includes specific sections dedicated to plastic pallets for sprinkler system design and protection in warehouses. For logistics operators, warehouse managers, and safety compliance officers, these updates necessitate a thorough review of storage configurations and fire suppression systems. Failure to account for these classifications can result in increased insurance premiums, operational restrictions, or safety risks.
Plastic Pallets Market
Conversely, the market benefits from certain regulatory exemptions. Plastic pallets are exempt from ISPM-15 phytosanitary treatment standards that are mandatory for wood pallets. This exemption simplifies international shipping protocols, reduces treatment costs, and eliminates delays associated with fumigation. This advantage is particularly valuable for exporters and importers navigating complex cross-border trade regulations. Our report analyzes how these regulatory factors weigh against each other, helping stakeholders assess the total cost of compliance and the strategic benefits of choosing plastic over wood in regulated environments.
Competitive Landscape and Key Players
The competitive environment in the plastic pallets market is characterized by a mix of global pooling giants, specialized manufacturers, and regional players. Our research identifies a consolidated landscape where top players command significant market share, fostering both competition and collaboration in pooling networks and innovation.
Global leaders such as CHEP continue to set the standard for reusable plastic pallet pooling and supply solutions, leveraging extensive networks to optimize asset utilization for clients. In North America, companies like Rehrig Pacific Company, ORBIS Corporation, and Millwood Inc. are prominent for their focus on durable, nestable, and rackable designs that enhance supply chain efficiency. These firms often emphasize full pallet solutions, including custom options and recycled content integration.
In Europe, CABKA Group and Schoeller Allibert represent strong competitive forces. CABKA is noted for producing nestable and endur plastic pallets from recycled materials, aligning closely with sustainability trends. Schoeller Allibert provides global hygienic and reusable solutions, catering to sectors where cleanliness is paramount. Other notable participants include Polymer Solutions International, Elkhart Plastics, Lile Group, and Vantage Plastics, each bringing specialized capabilities ranging from rotomolded custom pallets for food-safe applications to thermoformed solutions for automotive and household goods.
This competitive mix drives innovation in design, material usage, and service models. Our report offers a detailed competitive benchmarking analysis, examining the strategic positioning, product portfolios, and recent developments of these key companies. Understanding these dynamics is essential for identifying partnership opportunities, assessing supplier reliability, and anticipating market shifts driven by competitor actions.
Paper Pallet Market
Operational Value and Strategic Applications
Beyond the macro data, the true value of this research lies in its operational applicability. The report is structured to provide actionable insights for various functional teams within an organization.
-
Procurement and Supply Chain: Gain insights into material sourcing trends, including the availability and pricing implications of recycled vs. virgin resins. Learn how to evaluate pallets based on total cost of ownership, considering factors like lifespan, repairability, and pooling viability.
-
Risk Management and Compliance: Navigate the complex regulatory environment with detailed explanations of fire code implications, ISPM-15 exemptions, and other standards. Ensure your storage and transport strategies align with the latest NFPA updates and international trade requirements.
-
Product Development and Innovation: For manufacturers and private label buyers, the segmentation analysis reveals gaps in the market for specialized pallet types. Understand the performance characteristics demanded by different applications, from heavy-duty chemical handling to hygienic food transport.
-
Sustainability Strategy: Leverage data on recycled content usage and the environmental advantages of reusable plastic systems. Align your pallet choices with corporate ESG goals, demonstrating reductions in waste and carbon footprint compared to single-use or wood alternatives.
The report also addresses the strategic implications of pallet pooling versus owned assets, a decision that impacts working capital, logistics flexibility, and asset recovery rates. By analyzing the operational models of leading players, we provide a framework for evaluating which approach best suits your specific supply chain topology and volume requirements.
Conclusion: The Imperative for Informed Decision-Making
As the plastic pallets market moves through its forecast period, the intersection of material innovation, regulatory change, and competitive pressure creates a complex environment for business leaders. The growth trajectory indicated by our macro analysis suggests a market that is expanding but also evolving in sophistication. Success in this landscape requires more than general industry knowledge; it demands precise, data-driven intelligence that can inform capital investment, vendor selection, and risk mitigation strategies.
This market research report by PW Consulting offers a comprehensive examination of the factors shaping the plastic pallets industry. From the dominance of HDPE and PP to the nuances of fire code regulations and the competitive maneuvers of global players, every aspect is scrutinized to provide a clear path forward. However, the full depth of our analysis—including specific regional valuations, detailed customer insights, and proprietary forecasting models—remains within the complete report.
We invite stakeholders committed to optimizing their supply chain assets and staying ahead of market shifts to explore the full findings. The strategic advantages of the coming years will belong to those who anticipate change and equip themselves with the most accurate intelligence available.
For detailed analysis of this topic, please visit the official page: Plastic Pallets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Voluntary Carbon Offsets Market to Hit $13.56B by 2032, 30.7% CAGR
By pmarketresearch, 2026-09-15
Beyond Compliance: Strategic Intelligence for the 2026 Voluntary Carbon Offsets Market
The voluntary carbon market has entered a decisive phase. After a period of volatility and intense scrutiny regarding project integrity, the sector is recalibrating around quality, transparency, and measurable impact. For corporate sustainability leaders, procurement officers, and strategic planners, navigating this landscape demands more than surface-level metrics. It requires a granular understanding of supply dynamics, regulatory trajectories, and the competitive positioning of key market participants.
PW Consulting's latest market research on the Voluntary Carbon Offsets Market offers a structured view of this evolution. Drawing on historical data from 2020 through 2025 and projecting forward to 2032, the study provides a foundation for evidence-based decision-making in 2026 and beyond. The following analysis outlines the strategic value of this research, highlights the operational content embedded within the report, and frames the competitive and regulatory forces shaping the next phase of market development.
Market Trajectory and the 2026 Inflection Point
The historical record reveals a market that has matured through cycles of expansion, contraction, and reevaluation. Between 2020 and 2025, total revenue progressed from approximately $0.4 billion to $2.1 billion, reflecting both surging corporate interest in climate commitments and subsequent corrections driven by concerns over credit quality and additionality. The trajectory is not linear. Periods of rapid growth were followed by consolidation and a sharper focus on verification standards, project selection, and methodological rigor.
Looking ahead, the forecast period from 2026 to 2032 signals a reacceleration under clearer structural conditions. The market is projected to grow at a compound annual growth rate of 30.7%, reaching a revenue base of approximately $2.75 billion in 2026 and expanding to $13.56 billion by 2032. These figures are not merely top-line indicators; they encode underlying shifts in demand composition, project type preferences, and regional participation patterns. For 2026 planning cycles, the inflection point matters because it coincides with a wave of regulatory clarity, new methodology rollouts, and a recalibration of corporate offsetting strategies. Organizations that understand the shape of this growth, rather than simply its magnitude, will be better positioned to allocate budgets, structure procurement contracts, and align offsetting activities with broader decarbonization pathways.
The research frames this growth within strategic questions that matter for 2026 decision-making: which project categories are gaining share, how does demand differ across application areas, and what does regional participation reveal about supply availability and pricing dynamics? The answers are developed in depth within the report, where granular segmentation data is presented alongside qualitative analysis of market drivers and constraints.
Regulatory and Structural Dynamics Reshaping the Landscape
The voluntary carbon market does not operate in a vacuum. Recent developments have introduced both pressure and opportunity, reshaping the economics of credit procurement and the criteria for high-integrity sourcing. A series of regulatory and institutional milestones during late 2025 and early 2026 stand out as particularly consequential.
Voluntary Carbon Offsets Market
The European Commission's adoption of rules for an EU-wide voluntary certification framework for carbon removals and carbon farming under the CRCF Regulation marks a new era of institutional oversight. This framework, accompanied by Implementing Regulation (EU) 2025/2358 introducing transparency standards for voluntary carbon credit certification schemes, elevates the bar for documentation, traceability, and disclosure. For companies sourcing credits in or linked to European markets, these standards create both compliance considerations and competitive differentiators for providers who can demonstrate alignment.
Simultaneously, the Integrity Council for the Voluntary Carbon Market (ICVCM) has advanced the Core Carbon Principles as a global benchmark for high-integrity voluntary carbon credits. Assessment activity ongoing through 2025 has begun to separate projects and methodologies that meet these benchmarks from those that do not. This process is influencing buyer behavior, as organizations increasingly seek credits with verifiable integrity credentials to protect against reputational and regulatory risk.
Methodological innovation continues to progress. Verra's announcement of the forthcoming Scope 3 Standard Program, intended to support corporate supply chain decarbonization using voluntary carbon credits, signals an expansion of use cases beyond direct operational offsets. In parallel, Equitable Earth launched its new REDD+ methodology, M002, aimed at addressing quality issues in voluntary carbon markets, while the Scaling JREDD+ Coalition, involving the World Bank and the Initiative for Sustainable Forest Landscapes, was launched to advance jurisdictional REDD+ in voluntary markets. These developments reflect a broader push toward jurisdictional approaches and higher-quality nature-based solutions.
Price dynamics remain a critical consideration. Typical voluntary carbon offset prices range from $5 to $10 per tonne for nature-based credits, with tech-based carbon dioxide removal credits exceeding $170 per tonne. This wide range underscores the importance of understanding credit type, project maturity, co-benefit profiles, and certification status when interpreting market levels. The report situates these pricing observations within a broader analysis of supply constraints, demand elasticity, and the strategic implications for procurement planning.
What the Report Delivers: Operational Content for 2026 Planning
This research is structured to support actionable decision-making rather than abstract market description. The report's content is designed to help organizations translate market signals into procurement strategies, risk assessments, and investment theses.
Key components include a detailed segmentation analysis covering regions, project types, and application areas. The segmentation reveals how demand is distributed across corporate net-zero commitments, energy and utilities, consumer goods and retail, and agriculture, while also distinguishing between avoidance and reduction projects and removal projects. Regional participation patterns are examined to highlight where supply and demand dynamics are converging or diverging. Rather than presenting these splits as static figures, the analysis connects them to underlying structural factors such as regulatory exposure, corporate reporting requirements, and project pipeline availability.
Carbon Offset/Carbon Credit Trading Service Market
The report also provides a comprehensive competitive landscape assessment. Profiles of leading market participants cover their operational focus, geographic footprint, and strategic positioning. Coverage spans organizations that provide voluntary carbon offset credits and integrated sustainability consulting, those developing high-integrity project portfolios, and firms specializing in renewable energy, energy efficiency, conservation forestry, and reforestation-based offsets. This competitive mapping helps buyers evaluate supplier capabilities, understand differentiation in sourcing models, and anticipate how market participants may adapt to new regulatory and integrity standards.
Beyond company profiles, the study incorporates recent developments and industry context to frame near-term market behavior. This includes regulatory milestones, methodology launches, coalition formations, and certification assessments that are actively reshaping sourcing strategies. By integrating these developments with historical and forecasted market data, the report enables readers to interpret short-term fluctuations within a longer-term structural context.
Competitive Positioning and Strategic Implications
The voluntary carbon offsets market features a diverse set of participants, each with distinct sourcing models, project specializations, and geographic strengths. Understanding this landscape is essential for buyers seeking to construct resilient procurement portfolios and for investors or partners evaluating market entry and expansion opportunities.
Among the companies profiled, several exhibit clear strategic orientations. Some providers emphasize integrated sustainability consulting alongside offset credit supply, positioning themselves as advisors rather than purely transactional intermediaries. Others focus on high-integrity projects, leveraging rigorous certification and transparent project selection as differentiators. Specialized players concentrate on particular project categories, such as renewable energy and energy efficiency, conservation forestry, or reforestation and conservation, aligning their offerings with specific buyer preferences and co-benefit considerations.
This diversity of models matters because market conditions increasingly reward specialization and integrity. As transparency standards tighten and integrity benchmarks gain traction, suppliers with robust project pipelines, clear certification pathways, and strong documentation practices are likely to gain relative advantage. Conversely, the market may consolidate around providers who can demonstrate alignment with emerging regulatory expectations, including the EU certification framework and ICVCM assessments. The report's competitive analysis highlights these dynamics, offering readers a basis for evaluating supplier selection criteria and anticipating shifts in market share.
Market concentration data provides additional context. The combined share of the top three and top five participants indicates a landscape that remains relatively fragmented at the top, with room for both established players and new entrants to influence sourcing flows. This fragmentation suggests that buyers have meaningful choice, but it also underscores the importance of due diligence in assessing credit quality, project documentation, and supplier reliability.
Navigating 2026 Decision Points with Structured Intelligence
For organizations making decisions in 2026, the voluntary carbon market presents a set of interconnected challenges and opportunities. Procurement teams must balance cost considerations against integrity requirements. Strategy teams must align offsetting activity with broader decarbonization goals, including supply chain emissions addressed through emerging standards. Risk teams must monitor regulatory developments, certification assessments, and price volatility across different credit types.
The report supports these decisions by connecting market data to practical questions. It helps clarify where demand is originating, how project types are evolving, and what regional patterns imply for supply access. It frames competitive dynamics in a way that informs supplier evaluation and portfolio construction. And it embeds recent regulatory and methodological developments within a market context, enabling readers to anticipate how standards, transparency requirements, and new methodologies may influence credit availability and pricing over the forecast period.
Importantly, the research is designed to reveal enough structural insight to guide strategy while reserving detailed segmentation figures and granular breakdowns for the full analysis. This approach reflects the reality that the most consequential decisions often depend on precise data that must be evaluated in context. Readers seeking to map out procurement pathways, assess regional supply considerations, or benchmark competitive positioning will find the complete segmentation data and supporting analysis essential to their work.
Accessing the Full Strategic Brief
The voluntary carbon offsets market is moving from a phase of experimentation and volatility toward one defined by integrity standards, regulatory clarity, and more disciplined procurement. For 2026 decision-makers, that transition creates both the need and the opportunity to act on robust market intelligence.
PW Consulting's Voluntary Carbon Offsets Market research provides the depth required to navigate that transition. By combining historical trajectory, forecast projections, segmentation analysis, competitive profiling, and recent industry developments, the report equips leaders with a structured view of where the market has been and where it is heading. The full analysis includes the detailed data necessary to convert strategic insight into procurement plans, supplier evaluations, and investment judgments.
To access the complete segmentation data, regional and application breakdowns, and the full competitive landscape assessment, readers are encouraged to visit the source page for this market research. The complete report provides the granular intelligence needed to support confident, evidence-based decisions throughout 2026 and the forecast period ahead.
For detailed analysis of this topic, please visit the official page: Voluntary Carbon Offsets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Endoscopy Ultrasound Market Hits $1,340M in 2025, Forecasts 7.1% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Endoscopy Ultrasound Market 2026–2032
The landscape of advanced gastrointestinal imaging is undergoing a structural transformation. Driven by rising oncology screening volumes, strategic partnerships accelerating imaging clarity, and an increasingly dense competitive field, the endoscopy ultrasound (EUS) sector demands rigorous, forward-looking intelligence. This analysis distills the foundational architecture of our latest Endoscopy Ultrasound Market research, a comprehensive study designed specifically to equip executive teams, product leaders, and strategy officers with actionable decision frameworks for 2026 and the forecasting window through 2032.
Policymakers, investors, and corporate planners navigating this space in 2026 face a dual imperative: capture the momentum of a maturing yet rapidly expanding market while navigating intricate reimbursement gradients, evolving regulatory clearances, and material-driven supply chain considerations. The study at the center of this article is constructed not merely to report historical trajectories, but to translate them into defensible strategic pathways. Several foundational market metrics anchor this intelligence. Tracing performance across the 2020–2025 historical window, the market closed 2020 at approximately 950.0 million USD and climbed through successive annual increments, reaching roughly 1,340.0 million USD by the 2025 base year. Looking ahead into the 2026–2032 forecast period, the trajectory sustains a compound annual growth rate of 7.1 percent. By the end of the window, projected market revenue approaches 2,170.0 million USD, with intermediate milestones mapping a steady expansion through 2026, 2027, and beyond. Revenue figures are presented in millions of USD. These aggregate indicators establish the scale of the opportunity; the study then deconstructs the underlying mechanics that truly drive investment rationale.
Decoding the Structural Pillars of Growth
Understanding why the EUS market expands requires more than top-line tracking. Our research dissects the ecosystem across three interlocking axes: product architecture, clinical application pathways, and geographic distribution of demand. Each axis introduces distinct commercial dynamics, procurement behaviors, and adoption curves that together dictate where margin expansion, market share capture, and capacity investments will materialize.
On the product side, the market is segmented across endoscopes, ultrasound processors, ultrasound needles, and ultrasound probes. These categories do not grow in isolation. Processors function as the technological core, dictating image fidelity, workflow integration, and upgrade cycles that influence downstream accessory purchasing. Endoscopic platforms and specialized probes determine diagnostic reach and therapeutic versatility, while needle systems represent a high-frequency consumable layer with direct implications for procedural throughput and cost-per-case economics. The interplay between capital equipment refreshes and recurring consumable demand creates a multi-layered revenue architecture that procurement teams must model carefully when forecasting share and pricing power.
Endoscopy Ultrasound Market
Application segmentation further clarifies where clinical volume concentrates. The market is anchored by two dominant clinical domains: oncology and gastroenterology. Oncology procedures drive substantial volume due to staging requirements, tissue acquisition protocols, and the expanding use of EUS in guiding minimally invasive interventions. Gastroenterology applications maintain steady, high-utilization pathways for diagnostic evaluation, biliary and pancreatic assessments, and therapeutic maneuvers. The study examines how procedural coding structures, outpatient reimbursement patterns, and institutional procurement guidelines shape demand elasticity in each domain, revealing where volume growth translates directly into durable revenue and where reimbursement variability introduces margin uncertainty.
Geographic distribution compounds these dynamics. Demand is not uniformly weighted across regions. The study maps concentration patterns that highlight mature, high-density markets alongside emerging regions exhibiting different adoption velocities, regulatory maturation timelines, and infrastructure readiness. Understanding which regions contribute the largest revenue pools, and which are positioned for accelerated procedural diffusion, is essential for clinical rollout planning, distributor partnerships, and localized pricing strategies.
Competitive Architecture and Tactical Positioning
The EUS marketplace is characterized by a concentrated yet highly competitive supplier ecosystem. Our research quantifies industry concentration, revealing a market where a small cohort of leading firms commands significant share, while a broader tier of specialized manufacturers, component suppliers, and emerging innovators competes for procedural footprint and hospital formulary placement. This concentration profile shapes bargaining dynamics, partnership opportunities, and barriers to entry in distinct ways.
At the forefront of comprehensive EUS portfolios stand organizations such as Olympus Corporation, Boston Scientific Corporation, Medtronic plc, FUJIFILM Holdings Corporation, and Pentax Medical. These players don't merely supply equipment; they engineer integrated diagnostic-therapeutic ecosystems. Olympus has consistently broadened its lineup with processors, echoendoscopes, miniature probes, and needle systems, while also advancing advanced imaging platforms through strategic technology partnerships. Recent activity underscores this momentum: in May 2026, Olympus introduced the Aplio i800 EUS Premium Ultrasound System in the United States via a partnership with Canon, targeting advanced imaging capabilities, and simultaneously showcased an expanded EUS solutions portfolio at Digestive Disease Week 2026. Earlier, in September 2025, FUJIFILM Holdings Corporation launched the Arietta 850 EUS processor alongside 700 Series linear scopes at the American College of Gastroenterology annual meeting, emphasizing enhanced image clarity for diagnostic and interventional workflows.
Worldwide Ultra HD Endoscope Market
Beyond the integrated giants, a specialized layer of players competes intensely around high-frequency consumables and targeted procedural tools. Companies including ConMed Corporation, Cook Medical, Medi-Globe Corporation, and B. Braun deliver EUS endoscopes, needles, stents, and accessories that intersect directly with the procedural cost structure. Needle technology, in particular, carries material and performance implications that ripple through both clinical adoption and procurement economics, with biopsy needles increasingly relying on medical-grade nitinol and multi-layer shear designs to secure consistent tissue acquisition.
Perhaps most strategically interesting is the emergence of innovators targeting workflow accessibility and technology democratization. EndoSound, Inc. exemplifies this approach with its Vision System, designed to transform standard upper GI endoscopes into full EUS-capable platforms. Meanwhile, auxiliary suppliers such as STERIS plc and Nihon Dempa Kogyo Co., Ltd. anchor the ecosystem through endoscope reprocessing and sterilization validation, and ultrasonic component supply, respectively. These enabling players illustrate how the competitive field extends well beyond the instrument manufacturer, encompassing sterilization compliance, component engineering, and clinical enablement services.
The presence of additional platform developers and therapeutic contributors—spanning entities like HUACO Healthcare Technologies, Limaca Medical, Philips, Smith & Nephew, and SonoScape Medical Corp.—further diversifies the landscape. Our study evaluates how this layered player base shapes pricing pressure, innovation cadence, procurement bundling behavior, and regional market entry strategies. It also assesses how certified clinical application specialists drive on-site training and procedural optimization, a factor that increasingly differentiates vendors in a market where adoption velocity hinges on skill transfer as much as hardware performance.
Market Dynamics: Reimbursement, Regulation, and Operational Realities
Strategic decision-making in EUS requires a clear grasp of the operational and regulatory scaffolding that governs commercialization. The study integrates these dynamics not as peripheral context, but as core variables that influence market entry timing, product clearance pathways, and the financial viability of procedural programs.
Reimbursement structures exert a direct influence on institutional adoption. EUS procedures are generally billed under standard outpatient CPT codes, yet Medicare national average payments vary, and coverage nuances differ across payer types and care settings. These reimbursement gradients affect hospital investment calculus, clinical volume projections, and the speed at which new technologies achieve cost neutrality within departmental budgets. The report maps how coding ambiguity and payment variability shape procurement risk and where service bundling, training support, and workflow efficiency arguments become essential to overcome reimbursement friction.
Regulatory pathways remain equally consequential. New EUS devices require FDA 510(k) clearance, a process that recent premarket notifications—such as those associated with Olympus EVIS EUS ENDOSCOPIC ULTRASOUND CENTER EU-ME3 and the EndoSound Vision System—demonstrate continues to gate innovation velocity and commercialization timelines. Clearance timelines, predicate strategy, and post-market compliance expectations are dissected within the report to help companies calibrate R&D investment cycles, regulatory filing sequencing, and market launch pacing. In parallel, infection prevention and device reprocessing have become non-negotiable compliance considerations. EUS equipment must satisfy standard endoscope reprocessing validation protocols overseen by manufacturers including STERIS, making sterilization compatibility and validation documentation integral to product acceptance in tightly regulated clinical environments.
Beyond regulatory and reimbursement mechanics, the report examines how material sourcing and clinical support economics intersect with product strategy. Needle construction materials, processing requirements, and component engineering influence both performance differentiation and supply chain resilience. Simultaneously, the role of on-site application specialists—who deliver training, optimize procedural workflows, and reinforce adoption—emerges as a strategic investment rather than a support function, directly influencing institutional satisfaction and repeat purchasing behavior.
What the Research Delivers for 2026 Decision-Making
This study is engineered as an executive-grade instrument for strategic allocation, competitive positioning, and market timing. It moves beyond descriptive market snapshots to provide an operational playbook for navigating a sector where technological differentiation, reimbursement navigation, and regional adoption patterns jointly determine success. The content is organized to support cross-functional planning across R&D, commercial strategy, finance, and operations.
At a strategic level, the report delivers:
- A validated historical-to-forecast trajectory that establishes baseline scale, growth velocity, and structural inflection points across the 2020–2032 horizon.
- A multidimensional segmentation framework that clarifies how product categories, clinical applications, and geographic markets interact to create differentiation opportunities and concentration risks.
- A competitive landscape assessment that evaluates market concentration, portfolio breadth, component enabling roles, and innovation pipelines across leading and emerging players.
- An integrated market dynamics module covering reimbursement variability, regulatory clearance requirements, reprocessing validation demands, material cost considerations, and clinical enablement economics.
- Actionable interpretive layers designed to help executive teams align product roadmaps, pricing architectures, partnership strategies, and regional entry priorities with observed demand behavior and procedural economics.
The report is particularly intended to support decision-makers who must answer questions that extend far beyond aggregate growth rates: which product categories hold the most defensible expansion potential, how reimbursement and regulatory realities reshape adoption timelines, where competitive intensity is likely to intensify or fragment, and how institutional procurement behavior responds to tool performance, workflow integration, and service support. By mapping these variables within a coherent analytical structure, the research equips leadership teams to construct scenarios, stress-test assumptions, and prioritize resource deployment with greater confidence.
Translating Intelligence into Strategic Action
The EUS market in 2026 presents both maturation and momentum. Established players are deepening portfolio integration and advancing imaging platforms through partnerships and product launches, while specialized manufacturers and emerging innovators continue to pressure differentiation through consumable innovation, procedural accessibility, and workflow enablement. At the same time, reimbursement variability, regulatory clearance requirements, sterilization compliance expectations, and material-driven supply considerations shape the pace at which new technologies scale within clinical institutions. Against this backdrop, aggregate market size and growth trajectories provide necessary context, but only granular segmentation, competitive analysis, and dynamic factor modeling can inform defensible strategy.
Our Endoscopy Ultrasound Market research is built to bridge that gap. It distills historical performance, forecast indicators, segmentation architecture, competitive positioning, and operational dynamics into a unified view that supports capital planning, product portfolio decisions, market entry timing, and partnership evaluation. Organizations seeking precise figures, segmentation splits, regional revenue distribution, and application-level breakdowns will find those detailed dimensions embedded within the full report. The executive architecture previewed here is intended to demonstrate analytical rigor while directing decision-makers toward the complete dataset required for granular execution.
For strategy, finance, and commercial leadership teams preparing 2026 planning cycles, this research provides the structural intelligence necessary to move from market awareness to market execution. The complete study supplies the quantitative resolution, competitive benchmarking, and dynamic factor analysis that translate high-level growth signals into specific investment priorities, pricing strategies, rollout sequencing, and competitive responses. In a market where imaging clarity, procedural efficiency, and compliance readiness increasingly determine commercial outcomes, the difference between reactive positioning and proactive advantage lies in the depth of intelligence behind the decision.
For detailed analysis of this topic, please visit the official page: Endoscopy Ultrasound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Heat Exchanger Market Hits $20.01 Billion in 2025, Forecast to Reach $29.47 Billion by 2032
By pmarketresearch, 2026-09-15
Navigating Thermal Efficiency: Strategic Imperatives in the 2026 Heat Exchanger Market
In the complex ecosystem of global industrial infrastructure, the heat exchanger stands as a silent yet critical enabler of thermal efficiency. From the massive condensers in nuclear power plants to the compact units cooling data centers, these components dictate the operational viability of countless processes. As we move deeper into the decade, the Heat Exchanger Market is undergoing a transformation driven by capital intensity, regulatory tightening, and shifting geographic demand. PW Consulting's latest market research provides a comprehensive lens through which businesses can view these dynamics, offering the granular intelligence necessary to navigate the forecast period from 2026 through 2032.
This report is not merely a collection of statistics; it is a strategic toolkit designed for executives, procurement leaders, and investors. By synthesizing historical performance with forward-looking models, we uncover the layers of opportunity and risk that define the current landscape. The following analysis outlines the core components of this research, highlighting why immediate access to detailed market intelligence is vital for maintaining competitive advantage in an industry characterized by high concentration and evolving technical standards.
Market Trajectory and Economic Scale
The industrial sector values stability, yet the heat exchanger market has demonstrated consistent upward momentum. Based on historical analysis covering the period from 2020 to 2025, the market has scaled significantly, reflecting broader industrial output and energy demands. Our research models project this trajectory to continue, with the overall market valuation expected to reach approximately 20.83 billion USD in 2026. This figure serves as a critical baseline for annual budgeting and capital expenditure planning.
Looking further ahead, the forecast extends to 2032, where the market size is anticipated to expand substantially, driven by sustained investment in power generation and processing facilities. The Compound Annual Growth Rate (CAGR) during this forecast period is estimated at 5.5 percent. While this growth rate indicates a mature but healthy industry, it masks significant variations across different technology types and application sectors. Understanding where this growth concentrates is essential for allocating resources effectively. The report details the revenue units in billions of USD, providing a clear monetary framework for assessing market potential without getting lost in vague projections.
Segmentation and Technology Focus
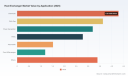
The market is divided into distinct technological categories, each serving specific industrial needs. Our analysis breaks down the landscape by type, including Shell & Tube, Plate & Frame, Air Cooled, Cooling Towers, and Others. Each segment presents unique manufacturing challenges and end-user requirements. For instance, Shell & Tube units remain dominant in heavy industry, while Plate & Frame solutions are critical for HVAC and refrigeration efficiency. The research provides a deep dive into the revenue contribution of each type, allowing firms to benchmark their portfolio against market share leaders.
Beyond technology, the application spectrum is equally diverse. Key sectors include Chemicals, Oil & Gas, Power Generation, HVAC, Automobile, Food & Beverages, and Others. The demand profile varies sharply between these verticals. Power generation and chemical processing typically require robust, high-pressure equipment, whereas HVAC and food applications demand precision and hygiene compliance. The report elucidates how these application verticals influence procurement cycles and specification requirements. By understanding the revenue splits across these segments, companies can identify underserved niches or over-saturated zones before committing to new product lines.
Geographic Dynamics and Regional Hubs
Geography plays a pivotal role in market accessibility and cost structures. The research provides a detailed breakdown of revenue by region, covering North America, Europe, Asia Pacific, Latin America, and Mideast and Africa. Asia Pacific currently represents a significant volume of activity, reflecting rapid industrialization and infrastructure development. Europe and North America maintain strong positions, driven by mature industrial bases and strict regulatory environments that necessitate high-quality, compliant equipment.
The report explores regional growth drivers, such as local manufacturing capabilities and import dependencies. For companies looking to expand their footprint, understanding the specific revenue contribution of each region is vital. It informs decisions regarding distribution networks, local partnerships, and pricing strategies. The data reveals where demand is most price-sensitive and where premium positioning is viable. This geographic intelligence is crucial for multinational corporations seeking to optimize their supply chains and for domestic players evaluating export opportunities.
Heat Exchanger Market
Competitive Landscape and Concentration
The Heat Exchanger Market is characterized by a high degree of concentration. Our analysis indicates that the top three competitors hold a CR3 of 65.0 percent, while the top five firms account for a CR5 of 78.0 percent. This level of consolidation suggests that market leadership is well-established, and new entrants face significant barriers related to scale, certification, and existing customer relationships. However, within the broader ecosystem, there are numerous specialized players carving out niches through customization and service excellence.
The report profiles key companies that define the competitive arena. Graham Corporation, headquartered in Batavia, NY, focuses on large shell and tube heat exchangers for industrial and power generation applications. Kelvion, Inc., based in Catoosa, OK, specializes in plate and fin heat exchangers for HVAC, refrigeration, and industrial processes. Perry Products Corporation in Newark, NJ, offers custom shell and tube heat exchangers and ASME-certified thermal fluid systems. These profiles extend to a wide array of specialists. Harris Thermal Transfer Products in Medford, WI, provides industrial heat exchangers for thermal management and process heating. Ward Vessel & Exchanger in New Kensington, PA, manufactures custom shell and tube heat exchangers and pressure vessels to ASME standards.
Further down the list, SPG Dry Cooling in Bridgewater, NJ, delivers dry cooling systems and heat exchangers for power plants and industrial applications. Bitzer US, Inc. in Peachtree Corners, GA, focuses on refrigeration and compressor heat exchangers. Taylor Forge Engineered Systems, Inc. in Paola, KS, supplies engineered heat transfer systems for industrial and refining sectors. American Exchanger Services, Inc. in Hartford, WI, distinguishes itself through heat exchanger services, repair, and maintenance. Croll Reynolds Company, Inc. in Parsippany, NJ, provides vacuum and heat exchange equipment for chemical and industrial processes. DC Fabricators Inc. in Florence, NJ, handles custom fabrication of heat exchangers and pressure vessels.
International presence is also significant. Holtec International in Camden, NJ, specializes in nuclear and industrial heat exchangers. Kansas City Deaerator Company in Stilwell, KS, focuses on deaerator and heat recovery heat exchangers. Maarky Thermal Systems in Cherry Hill, NJ, offers thermal management and heat exchange solutions. Sterling Deaerator Company in Cumming, GA, supplies deaerator heat exchangers for power and industrial use. Thermal Engineering Int'l (USA) Inc. in La Palma, CA, provides heat recovery and thermal engineering systems. On the global stage, Alfa Laval AB in Tullinge, Sweden, is known for gasketed plate and frame heat exchangers for industrial and HVAC applications. Danfoss A/S in Nordborg, Denmark, produces brazed plate heat exchangers for refrigeration and cooling systems. SPX Flow, Inc. in Charlotte, NC, manufactures scraped surface and industrial heat exchangers for food, beverage, and processing. WCR Heat Exchangers in Xenia, OH, is a key player in plate heat exchangers and replacement parts.
Understanding the specific offerings and geographic footprints of these entities is essential for competitive positioning. The report analyzes how these companies interact, compete, and collaborate within the supply chain.
Recent Developments and Industry Momentum
Market dynamics are frequently shifted by strategic moves from key players. Our research tracks recent developments that signal broader industry trends. In October 2025, WCR Heat Exchangers opened the largest U.S. plate heat exchanger manufacturing facility in Xenia, Ohio, featuring 212,000 square feet of capacity and multi-shift operations. This expansion underscores the demand for domestic manufacturing capacity and supply chain resilience.
Similarly, in January 2026, Danfoss began production at a new Monterrey facility in Mexico for brazed plate heat exchangers. This move aims to improve North American supply reliability, reflecting a trend toward nearshoring critical thermal components. Furthermore, in December 2025, SWEP introduced B327 and B224 brazed plate heat exchanger models specifically targeting data center cooling and district energy applications. This product launch highlights the growing intersection between thermal management and the digital infrastructure boom.
Looking forward, the Shanghai International Heat Exchanger & Heat Transfer Technology Expo, scheduled for June 2026, is set to feature new heat exchanger equipment, technologies, and materials from over 800 companies. As the leading China event for the sector, this exhibition represents a critical touchpoint for monitoring innovation pipelines and supplier networks in the Asia Pacific region. These events are not isolated; they are indicators of where capital is flowing and what technologies are gaining traction.
Regulatory, Material, and Cost Dynamics
Operating in the heat exchanger market requires navigating a complex web of regulations and cost factors. Raw material fluctuations have a direct impact on pricing and margins. According to the California Energy Commission, metallic heat exchanger costs have increased from less than 100 USD per kilowatt thermal to between 500 and 1000 USD per kilowatt thermal. This substantial rise affects project economics and necessitates careful lifecycle cost analysis.
Graphite Heat Exchanger Market
Regulatory compliance remains a non-negotiable aspect of fabrication and sales. ASME U, S, and R stamps are required for pressure vessel and heat exchanger fabrication under federal and state mechanical codes. Additionally, TEMA standards govern the mechanical design and fabrication of shell and tube heat exchangers worldwide. For HVAC and refrigeration sectors, AHRI certification programs for brazed and fusion-bonded plate heat exchangers ensure compliance with liquid-to-liquid heat transfer standards. The report details how adherence to these standards impacts manufacturing costs and market access.
Trade dynamics also influence the market. Industry Market Data projects substantial increases in U.S. imports of heat exchange units classified under HTS 8419.50.10 and 8419.50.50 through 2025. This data point, sourced from the U.S. Department of Commerce Bureau of Industry and Security, suggests shifting supply chain dependencies that companies must monitor to avoid disruption. Understanding these regulatory and material pressures is key to pricing strategy and risk management.
Strategic Value for 2026 Decision-Makers
The primary objective of this research is to empower decision-makers with actionable intelligence. In an environment defined by 5.5 percent CAGR and a total market size approaching 30 billion USD by 2032, the difference between capturing market share and losing ground often lies in the details. The report provides the segmentation splits, regional breakdowns, and competitor profiles necessary to validate strategic hypotheses.
For procurement managers, the data offers benchmarks for negotiations and supplier selection. For investors, it clarifies growth vectors and risk concentrations. For manufacturers, it highlights capacity planning needs and technology investment priorities. The high market concentration indicates that partnership strategies and M&A considerations are as important as organic growth plans.
PW Consulting's Heat Exchanger Market research compiles these elements into a cohesive narrative. We invite you to explore the full report to access the complete dataset, including specific revenue units for each segment and region, detailed company profiles, and in-depth analysis of regulatory impacts. The insights contained within are designed to transform uncertainty into structured opportunity. Secure your copy today to ensure your organization is aligned with the thermal trends shaping the next decade of industrial performance.
For detailed analysis of this topic, please visit the official page: Heat Exchanger Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Enzymes Market to Reach $12B by 2032, Growing at 6.4% CAGR
By pmarketresearch, 2026-09-15
Industrial Enzymes Market 2026: Strategic Intelligence for the Next Growth Cycle
Executive Overview
The industrial enzymes sector has entered a decisive phase of expansion, driven by converging pressures in sustainability, process efficiency, and regulatory modernization. At PW Consulting, our latest deep-dive research on the Industrial Enzymes Market is engineered not as a static statistical snapshot, but as a forward-looking decision architecture for executives who must navigate procurement, R&D allocation, and competitive positioning through 2032.
The global market has demonstrated consistent upward momentum, with historical valuation scaling from approximately 5.3 billion USD in 2020 to an estimated 7.4 billion USD in 2025. Looking ahead, the forecast corridor projects revenues climbing toward 7.75 billion USD in 2026 and ultimately approaching 12 billion USD by 2032. This trajectory reflects a compound annual growth rate of 6.4 percent, underscoring a market that is neither speculative nor merely cyclical, but structurally reinforced by industrial adoption across multiple end-use verticals.
For strategy leaders, the strategic imperative is clear: this is a market where early alignment with fermentation innovation, feedstock optimization, and application-specific formulation can define margin resilience and customer lock-in. Our comprehensive report translates these macro signals into actionable intelligence, mapping where value is being created, where bottlenecks are emerging, and how the competitive center of gravity is shifting.
Enzyme for Pulp & Paper Market
The 2026 Decision Architecture: Why This Research Matters Now
Industrial enzyme adoption no longer operates as a purely technical procurement decision. It sits at the intersection of capital allocation, supply chain reconfiguration, and sustainability compliance. As manufacturers pursue lower-energy processing routes, formulate plant-forward ingredients, and respond to tightening environmental standards, enzyme selection has become a strategic lever rather than an operational commodity.
Our analysis is calibrated to help executives answer three critical questions that will define performance in 2026 and beyond. First, which application segments are experiencing durable demand pull, and where is growth dependent on transient factors? Second, how should organizations anticipate pricing dynamics given evolving fermentation economics, feedstock volatility, and trade policy intervention? Third, what competitive moves are likely to reshape procurement leverage, partnership opportunities, and innovation roadmaps over the next five to seven years?
The report is built to support board-level scenario planning and operational strategy alike. It integrates industry context, competitive capability mapping, and forward demand trajectories into a cohesive framework, allowing leadership teams to test assumptions before committing capital or rewriting supply contracts.
Market Trajectory and Structural Dynamics
Growth Corridor and Demand Architecture
The historical record establishes a base of steady compounding, but the forward story is defined by acceleration points. The market has elongated from early-stage industrial processing adoption into a broader ecosystem where enzymes serve as critical inputs in bio-processing, formulation efficiency, and waste valorization. The forecast period from 2026 through 2032 captures the inflection where scale-up economics, regulatory approvals, and application diversification converge.
Demand is not uniform across the value chain. Growth is being shaped by several reinforcing dynamics:
- Rising demand for bioethanol and related bio-based processing pathways is reinforcing volume uptake in select industrial applications, reinforcing the role of enzymes as enabling catalysts in renewable feedstock conversion.
- Government approvals for new enzymes continue to unlock downstream adoption, particularly where functionality, safety, and process compatibility meet evolving regulatory thresholds.
- Microbial fermentation using plant-based feedstocks remains the dominant production architecture, but this very dependency makes feedstock logistics, yield optimization, and fermentation throughput central to cost competitiveness.
- Cumulative US tariffs through 2025 are reshaping sourcing, pricing, and localization strategies across the industrial enzymes value chain, prompting manufacturers and end-users to reconsider geographic exposure and supply redundancy.
In this environment, the strategic value of the report lies in separating durable demand from cyclical noise. Rather than presenting a flat growth narrative, our research decomposes the trajectory into the operational and regulatory forces that will determine which players capture disproportionate share.
Application and Type Dynamics Without the Fog
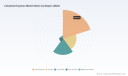
While the full segmentation architecture is presented in granular detail within the report, the strategic shape of the market is visible at the executive level. Food and beverage applications continue to anchor a significant portion of demand, reflecting broad formulation needs across processing efficiency, texture modification, and ingredient functionality. Biofuels and animal feed represent additional demand pillars with distinct growth drivers tied to energy transition pathways and livestock productivity optimization.
On the product architecture side, carbohydrate-active enzymes and protease-based solutions remain central to industrial processing, while lipases, polymerases, nucleases, and other specialized categories serve more targeted, higher-value niches. The report examines how these categories interact with application requirements, how formulation complexity affects pricing, and where technological differentiation is beginning to alter competitive positioning.
Critically, the research also evaluates how regulatory timing, validation cycles, and end-user qualification processes can create lag effects between innovation and commercial scale. For procurement and R&D leaders, this matters because the most promising enzyme class is not always the most immediately accessible one in a given jurisdiction or application category.
Competitive Landscape: Capability, Concentration, and Positioning
Market structure remains meaningfully concentrated, with a small group of multinational players holding a dominant share of revenue and innovation influence. The report analyzes this concentration not as a static fact, but as a dynamic condition shaped by R&D scale, fermentation capacity, application breadth, and partnership strategy. Cr3 concentration levels remain high, and Cr5 consolidation reinforces the reality that customers and investors are operating in an environment where scale, global distribution, and technical service capability confer meaningful advantage.
Several core companies anchor the competitive map, each with distinct strategic posture:
- Novonesis, headquartered in Denmark, emphasizes biosolutions for industrial bioprocessing, starch saccharification, grain processing, and high-performance biocatalysts across food and beverage, biofuels, and detergent applications.
- dsm-firmenich, based in the Netherlands, positions around enzyme solutions for processing ingredients including oils and fats, fermentation, fruit and vegetable processing, and starch saccharification.
- BASF SE, from Germany, focuses on high-performance industrial enzymes for grain processing, bio-ethanol production, animal nutrition, and detergents.
- Kerry Group plc, in Ireland, concentrates on enzymes for food and beverage processing, dairy, and plant-based applications.
- AB Enzymes GmbH, also based in Germany, offers formulated enzyme preparations for food, feed, technical, pulp and paper, baking, and plant-based food processing.
Beyond these major incumbents, the competition extends into specialized and regionally rooted players with differentiated technical capabilities:
- Amano Enzyme Inc., Japan, emphasizes specialty industrial enzymes including plant-based beverages, protein isolates, and non-dairy applications.
- Enzyme Development Corporation, United States, focuses on plant-based enzymes such as papain, ficin, thistle rennet, cellulases, and hemicellulases for food, beverage, and industrial uses.
- Dyadic International Inc., United States, develops recombinant enzymes and biocatalysts for biofuels, pulp and paper, brewing, specialty chemicals, and high-temperature industrial processes.
- Advanced Enzyme Technologies Limited, India, supports grain processing, brewing, dairy, oil and fat, and non-food applications with industrial enzyme solutions.
What distinguishes top-tier competitive analysis from a roster of company profiles is the examination of strategic behavior. The report maps where players are investing in capacity, where they are seeking regulatory or commercial advantage through product launches, and where collaboration is becoming a faster route to commercialization than internal development alone.
Strategic Implications for Industrial Strategy, Procurement, and Innovation
For executives, the market’s trajectory implies several actionable strategic themes. The first is supply chain localization and resilience. Trade policy exposure and fermentation economics are changing how procurement teams evaluate supplier geography, inventory buffering, and contract structures. The second is application-specific formulation as a margin defense. As commoditization pressures intensify in mature segments, differentiation through performance in targeted applications becomes a key path to pricing power.
The third theme is innovation speed relative to regulatory and qualification timelines. In practice, the winners are not only those with strong enzyme portfolios, but those who can navigate approvals, validate functionality, and integrate solutions into client processes with minimal friction. The fourth theme is partnership architecture. Recent industry activity suggests that recombinant enzyme development, biosolutions commercialization, and fermentation scale-up are increasingly collaborative endeavors, especially where speed to market and cross-application versatility matter.
Industrial Enzymes Market
The report translates these themes into strategic options. It identifies where to protect existing margin through supply design, where to pursue growth via application expansion, and where to monitor competitive threats that could alter bargaining power in sourcing negotiations.
Recent Developments Shaping 2026 Strategy
Recent corporate actions provide useful signals about where industry attention and capital are flowing. In October 2025, Lubrizol announced a 10 million USD investment to expand fermentation production capacity by five times at its Center of Skin Care Excellence in Gavà, Spain. This kind of capacity commitment reflects the growing importance of fermentation throughput and specialized production environments in competitive positioning.
In the product and partnership domain, recent activity illustrates the accelerating transition toward recombinant and non-animal enzyme solutions. In March 2026, Dyadic Applied BioSolutions and Inzymes ApS announced planned commercialization in 2026 of recombinant non-animal bovine chymosin for cheese and dairy processing following a successful development milestone. Separately, in December 2025, Dyadic and Fermbox Bio expanded their collaboration for commercializing animal-free proteins and enzymes across life science, food and nutrition, and bio-industrial markets.
These developments are not isolated product news. They point to a broader strategic current: recombinant platforms and partnership-led commercialization are becoming central to how next-generation enzyme solutions reach market. For competitors and customers alike, the implication is that sourcing options, formulation alternatives, and performance benchmarks are expanding more quickly than in prior cycles.
What the Full Report Delivers
The complete PW Consulting Industrial Enzymes Market research is structured to give leadership teams a dependable basis for strategic decision-making. It combines market sizing, segmentation, competitive profiling, and industry dynamics into a single analytical framework, while deliberately going beyond aggregate numbers to examine the operational and commercial forces shaping outcomes.
The report includes:
- Macro market trajectory and forecast architecture with a clear view of the 2026-2032 growth corridor.
- Segment-level analysis across region, enzyme type, and application, focused on commercial significance rather than raw tabulation.
- Competitor capability mapping and strategic posture assessment for leading multinational and specialized players.
- Industry context on fermentation-based production, feedstock dependency, and regulatory approval pathways as demand enablers.
- Trade policy and sourcing implications, including how tariff exposure is influencing localization and pricing strategies.
- Recent corporate developments and partnership signals that indicate where innovation and capacity investment are concentrating.
Throughout, the analysis is designed to support concrete decisions: which applications to prioritize, which suppliers or partners warrant deeper evaluation, where formulation or process innovation can create durable advantage, and how to anticipate shifts in market concentration and competitive intensity.
Conclusion: A Market Built for Strategic Advantage, Not Passive Participation
The industrial enzymes market is entering a period in which scale, technical specialization, regulatory timing, and supply chain design will separate resilient players from those merely reacting to change. With a market moving from 7.4 billion USD in 2025 toward an estimated 7.75 billion USD in 2026 and continuing upward toward 12 billion USD by 2032, the strategic stakes are rising in parallel with opportunity.
PW Consulting’s full report provides the depth required to turn these market signals into decisive action. For executives seeking clarity on where growth is structurally anchored, how competitive concentration shapes negotiation and innovation strategy, and which corporate developments genuinely matter for 2026 planning, the complete analysis is available through our dedicated Industrial Enzymes Market research page. There, the detailed segmentation, competitive evaluation, and forward-looking strategic framework are presented in full, enabling your team to move from awareness to execution with confidence.
For detailed analysis of this topic, please visit the official page: Industrial Enzymes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Solder Resist Ink Market to Reach $983M by 2032, CAGR 6.81%
By pmarketresearch, 2026-09-15
Navigating the Next Wave: Strategic Intelligence for the Solder Resist Ink Market (2026–2032)
The global electronics manufacturing landscape is undergoing a structural transformation, driven by the relentless miniaturization of devices, the proliferation of high-density interconnect technologies, and an increasingly stringent regulatory environment. At the heart of this evolution lies a critical yet often overlooked enabler: solder resist ink. As the protective and insulating layer that defines the functionality, reliability, and longevity of printed circuit boards and advanced semiconductor packaging, solder resist materials have evolved from commoditized commodities to highly engineered formulations. For executives, procurement leaders, and R&D directors operating in 2026, understanding the trajectory of this market is no longer optional—it is a strategic imperative.
This article serves as a strategic preview of PW Consulting’s newly released Solder Resist Ink Market research report. Rather than offering a superficial snapshot, this publication is engineered as a decision-grade intelligence asset, designed to cut through market noise, decode competitive dynamics, and map out actionable pathways for growth, risk mitigation, and supply chain resilience over the 2026–2032 forecast horizon.
The Macro Trajectory: Growth Anchored in Technological Crossroads
Over the past half-decade, the solder resist ink market has demonstrated a clear upward trajectory, expanding from approximately $450.0 million in 2020 to an estimated $620.0 million in 2025. This progression reflects more than cyclical recovery; it signals a fundamental shift in demand architecture. As electronics migrate into automotive, industrial automation, medical devices, and next-generation consumer applications, the requirements for solder resists have grown exponentially in terms of resolution, thermal stability, chemical resistance, and environmental compliance.
Looking ahead, the market is projected to reach $654.32 million in 2026 and continue its steady climb, culminating in an estimated $983.0 million by 2032. This expansion translates to a compound annual growth rate (CAGR) of 6.81% across the forecast period. Such a rate underscores a market that is neither stagnant nor purely speculative, but rather one aligned with sustained capital expenditure cycles in advanced electronics fabrication. For corporate strategists, this macro outlook provides a foundational baseline: demand will persist, but the distribution of that demand across technologies, applications, and geographies will increasingly reward players who can anticipate shifts rather than merely react to them.
Engineering the Future: Technological Shifts and Formulation Complexity
The core of today’s solder resist ink evolution lies in formulation science. As PCB line widths shrink and substrate complexities multiply, traditional liquid photoimageable formulations are being stress-tested alongside dry film, thermal curable, and UV curable alternatives. Each technology presents distinct trade-offs in terms of resolution capability, throughput efficiency, adhesion performance, and compatibility with advanced packaging workflows. The market is no longer dictated by a single dominant chemistry; instead, it is fragmenting into specialized niches where performance specifications dictate material selection.
Simultaneously, the push toward higher reliability standards in automotive and aerospace electronics, coupled with the thermal and mechanical demands of 5G infrastructure and high-performance computing, is forcing manufacturers to rethink curing profiles, cross-linking densities, and pigment dispersion techniques. Reports that merely catalog product types miss the point. What matters is how formulation architectures are being re-engineered to meet tighter tolerances, faster lamination cycles, and lower defect rates. Our research dissects these technological fault lines, mapping where innovation is concentrated, which curing mechanisms are gaining commercial traction, and how material scientists are balancing performance with manufacturability.
Solder Paste Market
Regulatory Pressures and Sustainability as Market Catalysts
Environmental and chemical compliance frameworks are no longer peripheral concerns; they are active drivers of product development and procurement strategy. The industry has witnessed a decisive pivot toward low-VOC and water-based ink systems, spurred by tightening environmental regulations and corporate sustainability mandates. European manufacturers have already introduced bio-based formulations achieving 100% halogen-free certification, signaling a new benchmark for eco-conscious material sourcing. Meanwhile, Apple’s Regulated Substances Specification has imposed strict 100 ppm limits on bisphenol chemicals in epoxy resin-based solder resist inks, effectively reshaping formulation pipelines for suppliers serving premium consumer electronics accounts.
Compounding these product-level mandates, REACH regulations and their subsequent amendments continue to restrict certain chemical substances, forcing R&D teams to navigate an increasingly complex compliance landscape. These dynamics do not merely add cost; they redefine competitive positioning. Companies that proactively integrate sustainable chemistries into their development roadmaps are building defensible moats, while laggards face mounting barriers to entry in tier-one supply chains. The report examines how regulatory trajectories are reshaping formulation priorities, altering supplier qualification cycles, and influencing long-term contract structures across key end-use sectors.
Supply Chain Volatility and the Raw Material Equation
Beyond formulation and compliance, the solder resist ink market is navigating a period of pronounced raw material volatility. US tariffs and geopolitical disruptions have introduced significant price fluctuations across precursor chemicals, resin systems, and pigment supply chains. These inputs are not interchangeable; they require precise engineering validation, lengthy qualification processes, and tightly controlled storage conditions. As a result, cost volatility cannot be easily absorbed or passed through without strategic planning.
For procurement and operations leaders, this environment demands a shift from transactional sourcing to portfolio-based supply chain architecture. Diversification, regional hedging, and qualification of alternative input streams are becoming critical levers for margin protection and production continuity. Our analysis maps the raw material exposure points across the value chain, identifies which formulation categories are most sensitive to input price swings, and outlines procurement strategies that balance cost efficiency with supply assurance in an unpredictable macroeconomic climate.
Competitive Architecture: Specialists, Integrators, and Strategic Maneuvers
The competitive landscape of the solder resist ink market is characterized by a high degree of concentration. The top three players command a combined market share of approximately 67.5%, while the top five extend their influence to roughly 82.3%. This concentration reflects the capital intensity of formulation R&D, the long qualification cycles required by PCB and semiconductor packaging manufacturers, and the technical expertise necessary to serve advanced applications. Yet within this consolidated structure, distinct strategic archetypes are emerging.
Japanese manufacturers continue to anchor the market with deep formulation expertise. Taiyo Ink Mfg. Co., Ltd. has built a reputation for industry-leading solder resist inks tailored to high-resolution PCB and advanced packaging requirements. Resonac Holdings Corporation complements this positioning by producing photosensitive solder resist films and inks specifically engineered for semiconductor packages and PCB substrates, recently expanding its footprint through the launch of an R&D center for next-generation semiconductor package technology under the US-JOINT Consortium. Tamura Corporation offers photoimageable solder resist inks and masks spanning rigid and flexible PCB applications, while San-Ei Kagaku Co., Ltd. focuses on solder resist inks alongside stripping and permanent hole plugging solutions for semiconductor substrates. Sumitomo Bakelite Co., Ltd. rounds out this cohort with epoxy-based solder resist inks designed for demanding PCB environments.
Across the Pacific, MacDermid Alpha Electronics Solutions and Huntsman Corporation bring complementary strengths. MacDermid Alpha supplies solder resist inks alongside a broader portfolio of PCB chemistry products, enabling integrated material solutions for complex fabrication flows. Huntsman leverages its epoxy chemistry heritage to deliver specialized solder resist formulations that address specific thermal and mechanical performance targets. These players illustrate how cross-portfolio synergies can accelerate customer qualification and deepen account penetration.
In Asia, regional specialists are capturing share through targeted product development and proximity to high-volume manufacturing hubs. Eternal Materials Co., Ltd. provides dry film solder masks and photoimageable materials for PCB and IC substrates, actively showcasing advanced polymer and UV technologies at major industry events such as CHINAPLAS 2026 and the American Coatings Show, where it has also highlighted durable resins and low-VOC solutions. Shenzhen Rongda Photosensitive Science & Technology Co., Ltd. and Jiangsu Kuangshun Photosensitivity New-material Stock Co., Ltd. concentrate on liquid photoimageable solder resist inks for circuit board production, reinforcing China’s role as both a manufacturing base and a growing source of formulation innovation. Kolon Industries, Inc. supplies dry film photoimageable solder resists tailored for flexible PCB applications, while Chang Chun Group integrates solder resist products within its broader electronics materials portfolio, leveraging scale and cross-category distribution.
Recent corporate activities underscore the strategic tempo of this market. Tamura Corporation exhibited solder resist masks at the SNEC PV POWER EXPO in May 2026, signaling continued investment in cross-industry applications. Eternal Materials has maintained a visible presence across international trade platforms, reinforcing its focus on durable resins and environmentally aligned formulations. Resonac’s R&D launch demonstrates how leading players are aligning research infrastructure with emerging semiconductor packaging demands. These developments are not isolated; they reflect a broader pattern of targeted exhibition participation, consortium engagement, and application-specific R&D investment that distinguishes market leaders from followers.
From Data to Decision: What the Full Report Delivers
Market intelligence is only as valuable as its translatability into action. PW Consulting’s Solder Resist Ink Market report is structured to bridge the gap between high-level trends and operational decision-making. The publication goes beyond aggregate figures to unpack the structural forces shaping supply, demand, and competitive positioning across the 2026–2032 horizon.
Readers will find:
- A detailed segmentation analysis that dissects market dynamics by type, application, and regional deployment patterns, revealing where growth is concentrated and which sub-segments are experiencing the fastest rate of change.
- An in-depth examination of the competitive landscape, mapping company positions, strategic focus areas, product portfolio coverage, and recent corporate moves that signal shifting market power.
- An assessment of regulatory and sustainability drivers, including how low-VOC mandates, halogen-free benchmarks, and chemical substance restrictions are altering formulation roadmaps and supplier qualification criteria.
- A supply chain and raw material analysis that identifies input volatility exposure, regional sourcing considerations, and strategic procurement approaches for mitigating cost and continuity risks.
- Forward-looking scenario analysis that connects technological adoption curves, end-use industry expansion, and macroeconomic factors to project plausible market trajectories and inflection points.
- Actionable insights for strategic planning, including recommendations for R&D prioritization, market entry or expansion timing, partnership and acquisition targets, and risk mitigation frameworks tailored to different company profiles.
The report is designed for executives who need more than a static data table. It provides the contextual architecture required to interpret market signals, evaluate competitive threats, and align internal capabilities with external demand shifts. Whether you are assessing portfolio expansion, sourcing strategy, technology investment, or regional market entry, the analysis is structured to inform concrete next steps rather than abstract observations.
Strategic Imperatives for 2026 and Beyond
As the solder resist ink market advances toward its 2032 horizon, the organizations that will capture disproportionate value are those that treat material selection as a strategic lever rather than a tactical specification. Several imperatives emerge clearly from the current landscape.
First, formulation agility must become a core competency. The convergence of higher resolution requirements, stricter chemical compliance, and diverse curing preferences means that rigid product portfolios will increasingly fall behind. Companies that invest in flexible development pipelines, rapid prototyping capabilities, and close collaboration with end-users will be better positioned to capture premium segments and secure long-term contracts.
Solder Resist Ink Market
Second, sustainability is transitioning from a compliance checkbox to a competitive differentiator. Low-VOC, water-based, bio-based, and halogen-free formulations are no longer niche alternatives; they are becoming baseline expectations in tier-one supply chains. Organizations that embed environmental performance into their product architecture early will reduce qualification friction, expand addressable accounts, and align with procurement policies that increasingly weight sustainability alongside cost and performance.
Third, supply chain resilience requires proactive architecture. Raw material volatility, tariff exposure, and geopolitical uncertainty are not transient disruptions; they are structural features of the current operating environment. Building diversified input streams, qualifying alternative suppliers, and developing regional hedging strategies will separate organizations that can maintain margin stability from those that are forced into reactive cost-cutting.
Fourth, competitive positioning will increasingly depend on application-specific expertise. The market is not moving uniformly; different end-use sectors demand different performance profiles, qualification timelines, and technical support models. Players that align their R&D, sales, and service capabilities with the specific needs of PCB manufacturing, semiconductor packaging, LED applications, and emerging segments will outperform those relying on generic product offerings.
Finally, intelligence must precede action. The pace of technological change, regulatory evolution, and competitive maneuvering in this market makes assumptions dangerous. Access to granular, forward-looking analysis enables leaders to time investments, prioritize resources, and anticipate shifts before they become industry consensus.
Conclusion: Turning Market Complexity into Strategic Advantage
The solder resist ink market stands at a critical juncture. Demand is expanding, technologies are diversifying, regulations are tightening, and competitive dynamics are intensifying. For organizations operating in this space, the difference between incremental growth and market leadership will be determined by the quality of strategic insight guiding their decisions. PW Consulting’s Solder Resist Ink Market report is built to provide that insight. It maps the terrain, decodes the forces shaping it, and equips decision-makers with the clarity needed to act confidently in 2026 and beyond.
The full report contains the detailed segmentation breakdowns, competitive positioning matrices, scenario analyses, and actionable recommendations required to translate market intelligence into executable strategy. To access the complete dataset, explore the full segmentation architecture, and gain the comprehensive competitive and regulatory analysis necessary for informed decision-making, we invite you to visit the official PW Consulting report page. There, you will find the complete market intelligence framework designed to support your strategic planning, sourcing decisions, R&D prioritization, and competitive positioning through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Solder Resist Ink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cationic Starch Market to Reach $2.34B by 2032, Growing at 4.89% CAGR from 2026
By pmarketresearch, 2026-09-15
Strategic Intelligence for 2026: Navigating the Cationic Starch Market
Executive Overview and Market Trajectory
The global cationic starch market represents a critical nexus of industrial chemistry, supply chain resilience, and sustainability-driven innovation. As we stand at the threshold of the forecast period extending through 2032, understanding the precise contours of this market is no longer optional for executive leadership. Our latest research report offers a comprehensive diagnostic of the industry, designed specifically to equip decision-makers with the actionable intelligence required to navigate the complexities of the coming years. The market has demonstrated a clear and sustained growth trajectory from the historical base of 2020 through 2025, culminating in a robust valuation in the base year. Looking forward, the industry is projected to expand steadily, with a compound annual growth rate of 4.89 percent over the forecast horizon. This growth is not merely statistical; it reflects a fundamental shift in how industrial sectors utilize starch derivatives for performance enhancement, surface sizing, and eco-friendly formulations. The narrative of the next seven years will be defined by the interplay between raw material accessibility, functional performance demands, and the accelerating pressure for sustainable manufacturing practices. Stakeholders who possess granular visibility into these dynamics will be best positioned to optimize procurement, refine product portfolios, and capture emerging value pools.
Macroeconomic Dimensions and Historical Momentum
The market size data paints a picture of consistent upward momentum. In 2020, the global revenue stood at 1362.5 million USD, reflecting a market that was already established but poised for acceleration. The subsequent years observed steady expansion, with 2021 recording 1432.15 million USD, 2022 reaching 1467.59 million USD, 2023 climbing to 1568.36 million USD, and 2024 advancing to 1631.25 million USD. The base year of 2025 closed at 1712.5 million USD, demonstrating a compound growth pattern that has laid a solid foundation for the forecast period. As we move into the outlook years, the trajectory continues its upward path. The market is expected to reach 1768.32 million USD in 2026, followed by significant jumps to 1913.96 million USD in 2027, 1968.12 million USD in 2028, and 2064.9 million USD in 2029. The momentum builds further as the forecast period progresses toward 2030, with projections indicating a valuation of 2198.22 million USD, sustained by a projected 2222.05 million USD in 2031, and ultimately closing the forecast window at 2342.0 million USD in 2032. This progression underscores a market that is not only growing but doing so with structural resilience, absorbing macroeconomic fluctuations while delivering predictable incremental value. For corporate strategists, this historical and projected data serves as a vital anchor for volume planning, capacity investment, and long-term revenue modeling.
Executive Brief: Unlocking the 2026 Cationic Starch Intelligence
The Strategic Imperative of Granular Market Intelligence
In an environment where raw material price volatility remains the most immediate threat to production economics, surface-level market summaries are insufficient for high-stakes decision-making. The cationic starch sector is particularly sensitive to feedstock dynamics, with major corn-producing regions accounting for over 85 percent of global corn production used in cationic starch feedstock. Simultaneously, regulatory frameworks are tightening, as evidenced by technical reports identifying environmental impacts including particulate matter emissions from corn wet-milling operations. These factors, combined with the shifting demand patterns across end-use sectors and the consolidation of competitive forces, create a landscape where precision intelligence is a primary competitive differentiator. Our newly released market research study is engineered to cut through the noise. It provides a multi-dimensional analysis that goes beyond aggregate figures to explore the underlying mechanics of supply, demand, pricing drivers, and competitive positioning. The report is designed to answer the critical questions that executives face: Where is value migrating? Which application segments are undergoing structural transformation? How will raw material cost trajectories impact margin profiles? What strategic moves are incumbents making to secure market share? By addressing these questions with rigorous methodology and verified data, the study delivers a clear roadmap for 2026 and beyond.
Cationic Conditioning Polymers Market
Core Analytical Dimensions Covered in the Report
The full research document delivers a detailed dissection of the market across multiple axes, ensuring that every strategic function within an organization finds relevant, actionable insights. The analysis begins with a comprehensive breakdown of market segmentation, examining how the industry is distributed across different typologies and regional landscapes. This includes an in-depth evaluation of how corn-derived, potato-derived, tapioca-derived, wheat-derived, and other starch variants perform within the global supply matrix. The regional dimension explores the distinct demand characteristics and supply chain configurations across major geographic territories, highlighting disparities in growth velocity, consumption intensity, and logistical maturity. A critical component of the analysis focuses on application-driven demand, dissecting how sectors such as paper making performance, the textile industry, adhesives, and other specialized uses are shaping consumption patterns. Paper making performance remains a dominant driver, reflecting the material's fundamental role in surface sizing, dry strength enhancement, and retention aid applications. The textile and adhesives segments are examined for their evolving functional requirements and substitution potential. Crucially, the report integrates real-time industry context, weaving in the latest developments and regulatory signals that are actively reshaping market behavior. This includes an analysis of how enzyme-assisted modification technologies are enabling next-generation bio-based cationic starches, and how proprietary enzymatic processes are reducing energy consumption in production. By synthesizing these dimensions, the study provides a holistic view of the market that is both technically rigorous and commercially relevant.
Competitive Landscape and Strategic Maneuvers
The competitive architecture of the cationic starch market is characterized by a concentrated yet dynamic field of players. Our analysis reveals a market structure where the top three companies command a combined share of 55 percent, while the top five collectively hold 62 percent. This concentration indicates a mature market with established leaders, yet it also leaves substantial room for regional specialists and niche players to compete on differentiation, cost efficiency, and service agility. Key enterprises shaping the landscape include ADM, headquartered in Chicago, Illinois, which produces cationic starch through corn wet-milling operations for paper surface sizing and industrial applications. Starch Asia, based in Bangkok, Thailand, produces and supplies cationic starch derived from prime tapioca starch for worldwide markets including Asia, Europe, and the USA. In India, Mahalaxmi Starch Products in Ahmedabad manufactures cationic starch powder primarily for industrial applications such as papermaking, while Bharat Starch in Jamnagar focuses on enhancing paper strength and productivity. Formonix Starch operates across India, manufacturing cationic starch from maize, tapioca, and potato for the paper industry. TNPL, located in Tirunelveli, Tamil Nadu, procures cationic starch for use in board machine operations within its paper production. These companies represent a cross-section of global integrators, regional suppliers, and integrated downstream users, each employing distinct strategies to navigate the market.
Recent Strategic Developments and Industry Signals
The competitive dynamics are further illuminated by a series of recent strategic moves that signal where the market is heading. In March 2025, Ingredion launched an eco-friendly cationic starch derived from non-GMO corn for papermaking and food applications, highlighting the growing intersection of sustainability and product formulation. By June 2025, Cargill announced a strategic partnership with a biotech startup for enzyme-assisted starch modification, developing next-generation bio-based cationic starches, a move that underscores the industry's pivot toward advanced biotechnological production pathways. ADM continued its consolidation strategy in August 2025 by acquiring a regional specialty starch producer to expand its functional starch derivatives portfolio, reinforcing the trend of vertical and horizontal integration among major players. In September 2025, Avebe introduced a proprietary enzymatic modification process reducing energy consumption in cationic starch production, directly addressing cost and sustainability pressures. Meanwhile, procurement activity remains active, as evidenced by an October 2025 tender award to an Indian paper mill for the procurement of cationic starch in jumbo bags for unit board operations. These developments are not isolated events; they are indicative of broader shifts in technology, sustainability, supply chain structure, and end-user procurement behavior. Our report analyzes these moves in detail, providing context on how they alter competitive positioning, influence pricing dynamics, and create new opportunities or threats for market participants.
Navigating Raw Material Volatility and Regulatory Currents
A nuanced understanding of the cationic starch market requires close attention to the raw material and regulatory environment that underpins production economics. The industry is deeply exposed to agricultural commodity markets, where price fluctuations can rapidly impact manufacturing cost structures. USDA projections for the 2025/26 season-average corn price of 4.20 USD per bushel reflected a record crop of 15.585 billion bushels and higher ending stocks, setting a backdrop of relative abundance. However, forward indicators suggest corn prices are expected to stagnate around 4.10 USD per bushel for the 2026 marketing year, influenced by sustained high production and supply increases. Despite this apparent stability, raw material price volatility for corn, potato, cassava, and wheat remains the most immediate threat to cationic starch production costs. The ability to hedge, contract, or optimize feedstock blends is therefore a critical competency for producers and downstream users alike. On the regulatory front, the 2025 Technical Report on cornstarch identified environmental impacts including particulate matter emissions from corn wet-milling operations, signaling tightening scrutiny on manufacturing practices. These regulatory and environmental factors are driving innovation in process efficiency and alternative modification methods, as companies seek to reduce energy intensity and emissions while maintaining product performance. Our market research integrates these macro-level forces, mapping them against regional and segment-level demand to reveal where cost pressures are most acute, where regulatory adaptation is creating barriers or opportunities, and how companies are responding through formulation innovation and operational restructuring.
Actionable Intelligence for 2026 and the Forecast Horizon
The true value of this research lies in its ability to translate complex data into strategic direction. For procurement leaders, the report offers a clear view of supply chain configurations, feedstock dependency patterns, and pricing drivers, enabling more resilient sourcing strategies. For product development and R&D teams, the analysis of application performance, type-specific characteristics, and recent technological breakthroughs provides a framework for innovation prioritization. For commercial and strategy executives, the competitive landscape mapping, concentration dynamics, and recent corporate moves offer a playbook for positioning, partnership evaluation, and market entry or expansion decisions. For sustainability and compliance officers, the integration of regulatory signals, environmental impact data, and eco-friendly product launches delivers the context needed to align operational practices with evolving standards and stakeholder expectations. The forecast period through 2032 is examined not as a static projection but as a scenario space where multiple variables interact. Growth rates, segment shifts, regional divergences, and competitive realignments are modeled and explained, allowing users to stress-test assumptions and prepare for a range of outcomes. By anchoring these forward-looking insights in rigorous historical analysis and current industry intelligence, the report minimizes uncertainty and maximizes decision confidence.
Data-Driven Precision: What the Full Study Delivers
This executive preview has highlighted the structural pillars of our latest cationic starch market research, but the complete study contains a depth of detail that is essential for operationalizing strategy. The full report includes precise segmentation splits across regions, types, and applications, providing the granular breakdowns that executives need to allocate resources, forecast demand, and identify high-potential niches. It details the revenue contributions, growth trajectories, and inter-segment dynamics that shape the overall market evolution. It explores the regional demand profiles and supply chain characteristics that differentiate markets across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. It dissects the performance of each starch type within the broader ecosystem, revealing relative strengths, constraints, and substitution dynamics. It evaluates application-specific consumption patterns, cost structures, and performance drivers across paper making performance, textile industry, adhesives, and other segments. It assesses the competitive strategies, market positions, and recent developments of key companies, including ADM, Starch Asia, Mahalaxmi Starch Products, Bharat Starch, Formonix Starch, TNPL, and others. It synthesizes raw material trends, regulatory developments, and technological innovations into a coherent narrative of market dynamics. All of this is presented with methodological transparency, data verification, and strategic commentary that connects numbers to actions.
How to Access the Complete Strategic Blueprint
The insights summarized here represent the strategic architecture of the report, but the detailed segmentation data, regional and application-specific revenue figures, company-level competitive analysis, and forward-looking scenario modeling are available only in the full document. For organizations that require precise market sizing, segment-level growth rates, competitive share analysis, and actionable recommendations tailored to functional decision-making, the complete study provides the comprehensive intelligence necessary to execute with precision. The market is moving, and the decisions made in 2026 will shape competitive standing through the end of the decade. Access the full report to equip your leadership team with the data, analysis, and strategic context needed to navigate this market with confidence.
Cationic Starch Market
For detailed analysis of this topic, please visit the official page: Cationic Starch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com