

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Endoscopy Ultrasound Market Hits $1,340M in 2025, Forecasts 7.1% CAGR Through 2032

Strategic Intelligence for the Endoscopy Ultrasound Market 2026–2032
The landscape of advanced gastrointestinal imaging is undergoing a structural transformation. Driven by rising oncology screening volumes, strategic partnerships accelerating imaging clarity, and an increasingly dense competitive field, the endoscopy ultrasound (EUS) sector demands rigorous, forward-looking intelligence. This analysis distills the foundational architecture of our latest Endoscopy Ultrasound Market research, a comprehensive study designed specifically to equip executive teams, product leaders, and strategy officers with actionable decision frameworks for 2026 and the forecasting window through 2032.
Policymakers, investors, and corporate planners navigating this space in 2026 face a dual imperative: capture the momentum of a maturing yet rapidly expanding market while navigating intricate reimbursement gradients, evolving regulatory clearances, and material-driven supply chain considerations. The study at the center of this article is constructed not merely to report historical trajectories, but to translate them into defensible strategic pathways. Several foundational market metrics anchor this intelligence. Tracing performance across the 2020–2025 historical window, the market closed 2020 at approximately 950.0 million USD and climbed through successive annual increments, reaching roughly 1,340.0 million USD by the 2025 base year. Looking ahead into the 2026–2032 forecast period, the trajectory sustains a compound annual growth rate of 7.1 percent. By the end of the window, projected market revenue approaches 2,170.0 million USD, with intermediate milestones mapping a steady expansion through 2026, 2027, and beyond. Revenue figures are presented in millions of USD. These aggregate indicators establish the scale of the opportunity; the study then deconstructs the underlying mechanics that truly drive investment rationale.
Decoding the Structural Pillars of Growth
Understanding why the EUS market expands requires more than top-line tracking. Our research dissects the ecosystem across three interlocking axes: product architecture, clinical application pathways, and geographic distribution of demand. Each axis introduces distinct commercial dynamics, procurement behaviors, and adoption curves that together dictate where margin expansion, market share capture, and capacity investments will materialize.
On the product side, the market is segmented across endoscopes, ultrasound processors, ultrasound needles, and ultrasound probes. These categories do not grow in isolation. Processors function as the technological core, dictating image fidelity, workflow integration, and upgrade cycles that influence downstream accessory purchasing. Endoscopic platforms and specialized probes determine diagnostic reach and therapeutic versatility, while needle systems represent a high-frequency consumable layer with direct implications for procedural throughput and cost-per-case economics. The interplay between capital equipment refreshes and recurring consumable demand creates a multi-layered revenue architecture that procurement teams must model carefully when forecasting share and pricing power.
Endoscopy Ultrasound Market
Application segmentation further clarifies where clinical volume concentrates. The market is anchored by two dominant clinical domains: oncology and gastroenterology. Oncology procedures drive substantial volume due to staging requirements, tissue acquisition protocols, and the expanding use of EUS in guiding minimally invasive interventions. Gastroenterology applications maintain steady, high-utilization pathways for diagnostic evaluation, biliary and pancreatic assessments, and therapeutic maneuvers. The study examines how procedural coding structures, outpatient reimbursement patterns, and institutional procurement guidelines shape demand elasticity in each domain, revealing where volume growth translates directly into durable revenue and where reimbursement variability introduces margin uncertainty.
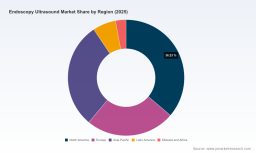
Geographic distribution compounds these dynamics. Demand is not uniformly weighted across regions. The study maps concentration patterns that highlight mature, high-density markets alongside emerging regions exhibiting different adoption velocities, regulatory maturation timelines, and infrastructure readiness. Understanding which regions contribute the largest revenue pools, and which are positioned for accelerated procedural diffusion, is essential for clinical rollout planning, distributor partnerships, and localized pricing strategies.
Competitive Architecture and Tactical Positioning
The EUS marketplace is characterized by a concentrated yet highly competitive supplier ecosystem. Our research quantifies industry concentration, revealing a market where a small cohort of leading firms commands significant share, while a broader tier of specialized manufacturers, component suppliers, and emerging innovators competes for procedural footprint and hospital formulary placement. This concentration profile shapes bargaining dynamics, partnership opportunities, and barriers to entry in distinct ways.
At the forefront of comprehensive EUS portfolios stand organizations such as Olympus Corporation, Boston Scientific Corporation, Medtronic plc, FUJIFILM Holdings Corporation, and Pentax Medical. These players don't merely supply equipment; they engineer integrated diagnostic-therapeutic ecosystems. Olympus has consistently broadened its lineup with processors, echoendoscopes, miniature probes, and needle systems, while also advancing advanced imaging platforms through strategic technology partnerships. Recent activity underscores this momentum: in May 2026, Olympus introduced the Aplio i800 EUS Premium Ultrasound System in the United States via a partnership with Canon, targeting advanced imaging capabilities, and simultaneously showcased an expanded EUS solutions portfolio at Digestive Disease Week 2026. Earlier, in September 2025, FUJIFILM Holdings Corporation launched the Arietta 850 EUS processor alongside 700 Series linear scopes at the American College of Gastroenterology annual meeting, emphasizing enhanced image clarity for diagnostic and interventional workflows.
Worldwide Ultra HD Endoscope Market
Beyond the integrated giants, a specialized layer of players competes intensely around high-frequency consumables and targeted procedural tools. Companies including ConMed Corporation, Cook Medical, Medi-Globe Corporation, and B. Braun deliver EUS endoscopes, needles, stents, and accessories that intersect directly with the procedural cost structure. Needle technology, in particular, carries material and performance implications that ripple through both clinical adoption and procurement economics, with biopsy needles increasingly relying on medical-grade nitinol and multi-layer shear designs to secure consistent tissue acquisition.
Perhaps most strategically interesting is the emergence of innovators targeting workflow accessibility and technology democratization. EndoSound, Inc. exemplifies this approach with its Vision System, designed to transform standard upper GI endoscopes into full EUS-capable platforms. Meanwhile, auxiliary suppliers such as STERIS plc and Nihon Dempa Kogyo Co., Ltd. anchor the ecosystem through endoscope reprocessing and sterilization validation, and ultrasonic component supply, respectively. These enabling players illustrate how the competitive field extends well beyond the instrument manufacturer, encompassing sterilization compliance, component engineering, and clinical enablement services.
The presence of additional platform developers and therapeutic contributors—spanning entities like HUACO Healthcare Technologies, Limaca Medical, Philips, Smith & Nephew, and SonoScape Medical Corp.—further diversifies the landscape. Our study evaluates how this layered player base shapes pricing pressure, innovation cadence, procurement bundling behavior, and regional market entry strategies. It also assesses how certified clinical application specialists drive on-site training and procedural optimization, a factor that increasingly differentiates vendors in a market where adoption velocity hinges on skill transfer as much as hardware performance.
Market Dynamics: Reimbursement, Regulation, and Operational Realities
Strategic decision-making in EUS requires a clear grasp of the operational and regulatory scaffolding that governs commercialization. The study integrates these dynamics not as peripheral context, but as core variables that influence market entry timing, product clearance pathways, and the financial viability of procedural programs.
Reimbursement structures exert a direct influence on institutional adoption. EUS procedures are generally billed under standard outpatient CPT codes, yet Medicare national average payments vary, and coverage nuances differ across payer types and care settings. These reimbursement gradients affect hospital investment calculus, clinical volume projections, and the speed at which new technologies achieve cost neutrality within departmental budgets. The report maps how coding ambiguity and payment variability shape procurement risk and where service bundling, training support, and workflow efficiency arguments become essential to overcome reimbursement friction.
Regulatory pathways remain equally consequential. New EUS devices require FDA 510(k) clearance, a process that recent premarket notifications—such as those associated with Olympus EVIS EUS ENDOSCOPIC ULTRASOUND CENTER EU-ME3 and the EndoSound Vision System—demonstrate continues to gate innovation velocity and commercialization timelines. Clearance timelines, predicate strategy, and post-market compliance expectations are dissected within the report to help companies calibrate R&D investment cycles, regulatory filing sequencing, and market launch pacing. In parallel, infection prevention and device reprocessing have become non-negotiable compliance considerations. EUS equipment must satisfy standard endoscope reprocessing validation protocols overseen by manufacturers including STERIS, making sterilization compatibility and validation documentation integral to product acceptance in tightly regulated clinical environments.
Beyond regulatory and reimbursement mechanics, the report examines how material sourcing and clinical support economics intersect with product strategy. Needle construction materials, processing requirements, and component engineering influence both performance differentiation and supply chain resilience. Simultaneously, the role of on-site application specialists—who deliver training, optimize procedural workflows, and reinforce adoption—emerges as a strategic investment rather than a support function, directly influencing institutional satisfaction and repeat purchasing behavior.
What the Research Delivers for 2026 Decision-Making
This study is engineered as an executive-grade instrument for strategic allocation, competitive positioning, and market timing. It moves beyond descriptive market snapshots to provide an operational playbook for navigating a sector where technological differentiation, reimbursement navigation, and regional adoption patterns jointly determine success. The content is organized to support cross-functional planning across R&D, commercial strategy, finance, and operations.
At a strategic level, the report delivers:
- A validated historical-to-forecast trajectory that establishes baseline scale, growth velocity, and structural inflection points across the 2020–2032 horizon.
- A multidimensional segmentation framework that clarifies how product categories, clinical applications, and geographic markets interact to create differentiation opportunities and concentration risks.
- A competitive landscape assessment that evaluates market concentration, portfolio breadth, component enabling roles, and innovation pipelines across leading and emerging players.
- An integrated market dynamics module covering reimbursement variability, regulatory clearance requirements, reprocessing validation demands, material cost considerations, and clinical enablement economics.
- Actionable interpretive layers designed to help executive teams align product roadmaps, pricing architectures, partnership strategies, and regional entry priorities with observed demand behavior and procedural economics.
The report is particularly intended to support decision-makers who must answer questions that extend far beyond aggregate growth rates: which product categories hold the most defensible expansion potential, how reimbursement and regulatory realities reshape adoption timelines, where competitive intensity is likely to intensify or fragment, and how institutional procurement behavior responds to tool performance, workflow integration, and service support. By mapping these variables within a coherent analytical structure, the research equips leadership teams to construct scenarios, stress-test assumptions, and prioritize resource deployment with greater confidence.
Translating Intelligence into Strategic Action
The EUS market in 2026 presents both maturation and momentum. Established players are deepening portfolio integration and advancing imaging platforms through partnerships and product launches, while specialized manufacturers and emerging innovators continue to pressure differentiation through consumable innovation, procedural accessibility, and workflow enablement. At the same time, reimbursement variability, regulatory clearance requirements, sterilization compliance expectations, and material-driven supply considerations shape the pace at which new technologies scale within clinical institutions. Against this backdrop, aggregate market size and growth trajectories provide necessary context, but only granular segmentation, competitive analysis, and dynamic factor modeling can inform defensible strategy.
Our Endoscopy Ultrasound Market research is built to bridge that gap. It distills historical performance, forecast indicators, segmentation architecture, competitive positioning, and operational dynamics into a unified view that supports capital planning, product portfolio decisions, market entry timing, and partnership evaluation. Organizations seeking precise figures, segmentation splits, regional revenue distribution, and application-level breakdowns will find those detailed dimensions embedded within the full report. The executive architecture previewed here is intended to demonstrate analytical rigor while directing decision-makers toward the complete dataset required for granular execution.
For strategy, finance, and commercial leadership teams preparing 2026 planning cycles, this research provides the structural intelligence necessary to move from market awareness to market execution. The complete study supplies the quantitative resolution, competitive benchmarking, and dynamic factor analysis that translate high-level growth signals into specific investment priorities, pricing strategies, rollout sequencing, and competitive responses. In a market where imaging clarity, procedural efficiency, and compliance readiness increasingly determine commercial outcomes, the difference between reactive positioning and proactive advantage lies in the depth of intelligence behind the decision.
For detailed analysis of this topic, please visit the official page: Endoscopy Ultrasound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com