

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Solder Resist Ink Market to Reach $983M by 2032, CAGR 6.81%

Navigating the Next Wave: Strategic Intelligence for the Solder Resist Ink Market (2026–2032)
The global electronics manufacturing landscape is undergoing a structural transformation, driven by the relentless miniaturization of devices, the proliferation of high-density interconnect technologies, and an increasingly stringent regulatory environment. At the heart of this evolution lies a critical yet often overlooked enabler: solder resist ink. As the protective and insulating layer that defines the functionality, reliability, and longevity of printed circuit boards and advanced semiconductor packaging, solder resist materials have evolved from commoditized commodities to highly engineered formulations. For executives, procurement leaders, and R&D directors operating in 2026, understanding the trajectory of this market is no longer optional—it is a strategic imperative.
This article serves as a strategic preview of PW Consulting’s newly released Solder Resist Ink Market research report. Rather than offering a superficial snapshot, this publication is engineered as a decision-grade intelligence asset, designed to cut through market noise, decode competitive dynamics, and map out actionable pathways for growth, risk mitigation, and supply chain resilience over the 2026–2032 forecast horizon.
The Macro Trajectory: Growth Anchored in Technological Crossroads
Over the past half-decade, the solder resist ink market has demonstrated a clear upward trajectory, expanding from approximately $450.0 million in 2020 to an estimated $620.0 million in 2025. This progression reflects more than cyclical recovery; it signals a fundamental shift in demand architecture. As electronics migrate into automotive, industrial automation, medical devices, and next-generation consumer applications, the requirements for solder resists have grown exponentially in terms of resolution, thermal stability, chemical resistance, and environmental compliance.
Looking ahead, the market is projected to reach $654.32 million in 2026 and continue its steady climb, culminating in an estimated $983.0 million by 2032. This expansion translates to a compound annual growth rate (CAGR) of 6.81% across the forecast period. Such a rate underscores a market that is neither stagnant nor purely speculative, but rather one aligned with sustained capital expenditure cycles in advanced electronics fabrication. For corporate strategists, this macro outlook provides a foundational baseline: demand will persist, but the distribution of that demand across technologies, applications, and geographies will increasingly reward players who can anticipate shifts rather than merely react to them.
Engineering the Future: Technological Shifts and Formulation Complexity
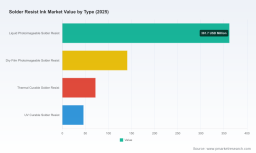
The core of today’s solder resist ink evolution lies in formulation science. As PCB line widths shrink and substrate complexities multiply, traditional liquid photoimageable formulations are being stress-tested alongside dry film, thermal curable, and UV curable alternatives. Each technology presents distinct trade-offs in terms of resolution capability, throughput efficiency, adhesion performance, and compatibility with advanced packaging workflows. The market is no longer dictated by a single dominant chemistry; instead, it is fragmenting into specialized niches where performance specifications dictate material selection.
Simultaneously, the push toward higher reliability standards in automotive and aerospace electronics, coupled with the thermal and mechanical demands of 5G infrastructure and high-performance computing, is forcing manufacturers to rethink curing profiles, cross-linking densities, and pigment dispersion techniques. Reports that merely catalog product types miss the point. What matters is how formulation architectures are being re-engineered to meet tighter tolerances, faster lamination cycles, and lower defect rates. Our research dissects these technological fault lines, mapping where innovation is concentrated, which curing mechanisms are gaining commercial traction, and how material scientists are balancing performance with manufacturability.
Solder Paste Market
Regulatory Pressures and Sustainability as Market Catalysts
Environmental and chemical compliance frameworks are no longer peripheral concerns; they are active drivers of product development and procurement strategy. The industry has witnessed a decisive pivot toward low-VOC and water-based ink systems, spurred by tightening environmental regulations and corporate sustainability mandates. European manufacturers have already introduced bio-based formulations achieving 100% halogen-free certification, signaling a new benchmark for eco-conscious material sourcing. Meanwhile, Apple’s Regulated Substances Specification has imposed strict 100 ppm limits on bisphenol chemicals in epoxy resin-based solder resist inks, effectively reshaping formulation pipelines for suppliers serving premium consumer electronics accounts.
Compounding these product-level mandates, REACH regulations and their subsequent amendments continue to restrict certain chemical substances, forcing R&D teams to navigate an increasingly complex compliance landscape. These dynamics do not merely add cost; they redefine competitive positioning. Companies that proactively integrate sustainable chemistries into their development roadmaps are building defensible moats, while laggards face mounting barriers to entry in tier-one supply chains. The report examines how regulatory trajectories are reshaping formulation priorities, altering supplier qualification cycles, and influencing long-term contract structures across key end-use sectors.
Supply Chain Volatility and the Raw Material Equation
Beyond formulation and compliance, the solder resist ink market is navigating a period of pronounced raw material volatility. US tariffs and geopolitical disruptions have introduced significant price fluctuations across precursor chemicals, resin systems, and pigment supply chains. These inputs are not interchangeable; they require precise engineering validation, lengthy qualification processes, and tightly controlled storage conditions. As a result, cost volatility cannot be easily absorbed or passed through without strategic planning.
For procurement and operations leaders, this environment demands a shift from transactional sourcing to portfolio-based supply chain architecture. Diversification, regional hedging, and qualification of alternative input streams are becoming critical levers for margin protection and production continuity. Our analysis maps the raw material exposure points across the value chain, identifies which formulation categories are most sensitive to input price swings, and outlines procurement strategies that balance cost efficiency with supply assurance in an unpredictable macroeconomic climate.
Competitive Architecture: Specialists, Integrators, and Strategic Maneuvers
The competitive landscape of the solder resist ink market is characterized by a high degree of concentration. The top three players command a combined market share of approximately 67.5%, while the top five extend their influence to roughly 82.3%. This concentration reflects the capital intensity of formulation R&D, the long qualification cycles required by PCB and semiconductor packaging manufacturers, and the technical expertise necessary to serve advanced applications. Yet within this consolidated structure, distinct strategic archetypes are emerging.
Japanese manufacturers continue to anchor the market with deep formulation expertise. Taiyo Ink Mfg. Co., Ltd. has built a reputation for industry-leading solder resist inks tailored to high-resolution PCB and advanced packaging requirements. Resonac Holdings Corporation complements this positioning by producing photosensitive solder resist films and inks specifically engineered for semiconductor packages and PCB substrates, recently expanding its footprint through the launch of an R&D center for next-generation semiconductor package technology under the US-JOINT Consortium. Tamura Corporation offers photoimageable solder resist inks and masks spanning rigid and flexible PCB applications, while San-Ei Kagaku Co., Ltd. focuses on solder resist inks alongside stripping and permanent hole plugging solutions for semiconductor substrates. Sumitomo Bakelite Co., Ltd. rounds out this cohort with epoxy-based solder resist inks designed for demanding PCB environments.
Across the Pacific, MacDermid Alpha Electronics Solutions and Huntsman Corporation bring complementary strengths. MacDermid Alpha supplies solder resist inks alongside a broader portfolio of PCB chemistry products, enabling integrated material solutions for complex fabrication flows. Huntsman leverages its epoxy chemistry heritage to deliver specialized solder resist formulations that address specific thermal and mechanical performance targets. These players illustrate how cross-portfolio synergies can accelerate customer qualification and deepen account penetration.
In Asia, regional specialists are capturing share through targeted product development and proximity to high-volume manufacturing hubs. Eternal Materials Co., Ltd. provides dry film solder masks and photoimageable materials for PCB and IC substrates, actively showcasing advanced polymer and UV technologies at major industry events such as CHINAPLAS 2026 and the American Coatings Show, where it has also highlighted durable resins and low-VOC solutions. Shenzhen Rongda Photosensitive Science & Technology Co., Ltd. and Jiangsu Kuangshun Photosensitivity New-material Stock Co., Ltd. concentrate on liquid photoimageable solder resist inks for circuit board production, reinforcing China’s role as both a manufacturing base and a growing source of formulation innovation. Kolon Industries, Inc. supplies dry film photoimageable solder resists tailored for flexible PCB applications, while Chang Chun Group integrates solder resist products within its broader electronics materials portfolio, leveraging scale and cross-category distribution.
Recent corporate activities underscore the strategic tempo of this market. Tamura Corporation exhibited solder resist masks at the SNEC PV POWER EXPO in May 2026, signaling continued investment in cross-industry applications. Eternal Materials has maintained a visible presence across international trade platforms, reinforcing its focus on durable resins and environmentally aligned formulations. Resonac’s R&D launch demonstrates how leading players are aligning research infrastructure with emerging semiconductor packaging demands. These developments are not isolated; they reflect a broader pattern of targeted exhibition participation, consortium engagement, and application-specific R&D investment that distinguishes market leaders from followers.
From Data to Decision: What the Full Report Delivers
Market intelligence is only as valuable as its translatability into action. PW Consulting’s Solder Resist Ink Market report is structured to bridge the gap between high-level trends and operational decision-making. The publication goes beyond aggregate figures to unpack the structural forces shaping supply, demand, and competitive positioning across the 2026–2032 horizon.
Readers will find:
- A detailed segmentation analysis that dissects market dynamics by type, application, and regional deployment patterns, revealing where growth is concentrated and which sub-segments are experiencing the fastest rate of change.
- An in-depth examination of the competitive landscape, mapping company positions, strategic focus areas, product portfolio coverage, and recent corporate moves that signal shifting market power.
- An assessment of regulatory and sustainability drivers, including how low-VOC mandates, halogen-free benchmarks, and chemical substance restrictions are altering formulation roadmaps and supplier qualification criteria.
- A supply chain and raw material analysis that identifies input volatility exposure, regional sourcing considerations, and strategic procurement approaches for mitigating cost and continuity risks.
- Forward-looking scenario analysis that connects technological adoption curves, end-use industry expansion, and macroeconomic factors to project plausible market trajectories and inflection points.
- Actionable insights for strategic planning, including recommendations for R&D prioritization, market entry or expansion timing, partnership and acquisition targets, and risk mitigation frameworks tailored to different company profiles.
The report is designed for executives who need more than a static data table. It provides the contextual architecture required to interpret market signals, evaluate competitive threats, and align internal capabilities with external demand shifts. Whether you are assessing portfolio expansion, sourcing strategy, technology investment, or regional market entry, the analysis is structured to inform concrete next steps rather than abstract observations.
Strategic Imperatives for 2026 and Beyond
As the solder resist ink market advances toward its 2032 horizon, the organizations that will capture disproportionate value are those that treat material selection as a strategic lever rather than a tactical specification. Several imperatives emerge clearly from the current landscape.
First, formulation agility must become a core competency. The convergence of higher resolution requirements, stricter chemical compliance, and diverse curing preferences means that rigid product portfolios will increasingly fall behind. Companies that invest in flexible development pipelines, rapid prototyping capabilities, and close collaboration with end-users will be better positioned to capture premium segments and secure long-term contracts.
Solder Resist Ink Market
Second, sustainability is transitioning from a compliance checkbox to a competitive differentiator. Low-VOC, water-based, bio-based, and halogen-free formulations are no longer niche alternatives; they are becoming baseline expectations in tier-one supply chains. Organizations that embed environmental performance into their product architecture early will reduce qualification friction, expand addressable accounts, and align with procurement policies that increasingly weight sustainability alongside cost and performance.
Third, supply chain resilience requires proactive architecture. Raw material volatility, tariff exposure, and geopolitical uncertainty are not transient disruptions; they are structural features of the current operating environment. Building diversified input streams, qualifying alternative suppliers, and developing regional hedging strategies will separate organizations that can maintain margin stability from those that are forced into reactive cost-cutting.
Fourth, competitive positioning will increasingly depend on application-specific expertise. The market is not moving uniformly; different end-use sectors demand different performance profiles, qualification timelines, and technical support models. Players that align their R&D, sales, and service capabilities with the specific needs of PCB manufacturing, semiconductor packaging, LED applications, and emerging segments will outperform those relying on generic product offerings.
Finally, intelligence must precede action. The pace of technological change, regulatory evolution, and competitive maneuvering in this market makes assumptions dangerous. Access to granular, forward-looking analysis enables leaders to time investments, prioritize resources, and anticipate shifts before they become industry consensus.
Conclusion: Turning Market Complexity into Strategic Advantage
The solder resist ink market stands at a critical juncture. Demand is expanding, technologies are diversifying, regulations are tightening, and competitive dynamics are intensifying. For organizations operating in this space, the difference between incremental growth and market leadership will be determined by the quality of strategic insight guiding their decisions. PW Consulting’s Solder Resist Ink Market report is built to provide that insight. It maps the terrain, decodes the forces shaping it, and equips decision-makers with the clarity needed to act confidently in 2026 and beyond.
The full report contains the detailed segmentation breakdowns, competitive positioning matrices, scenario analyses, and actionable recommendations required to translate market intelligence into executable strategy. To access the complete dataset, explore the full segmentation architecture, and gain the comprehensive competitive and regulatory analysis necessary for informed decision-making, we invite you to visit the official PW Consulting report page. There, you will find the complete market intelligence framework designed to support your strategic planning, sourcing decisions, R&D prioritization, and competitive positioning through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Solder Resist Ink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com