

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Voluntary Carbon Offsets Market to Hit $13.56B by 2032, 30.7% CAGR

Beyond Compliance: Strategic Intelligence for the 2026 Voluntary Carbon Offsets Market
The voluntary carbon market has entered a decisive phase. After a period of volatility and intense scrutiny regarding project integrity, the sector is recalibrating around quality, transparency, and measurable impact. For corporate sustainability leaders, procurement officers, and strategic planners, navigating this landscape demands more than surface-level metrics. It requires a granular understanding of supply dynamics, regulatory trajectories, and the competitive positioning of key market participants.
PW Consulting's latest market research on the Voluntary Carbon Offsets Market offers a structured view of this evolution. Drawing on historical data from 2020 through 2025 and projecting forward to 2032, the study provides a foundation for evidence-based decision-making in 2026 and beyond. The following analysis outlines the strategic value of this research, highlights the operational content embedded within the report, and frames the competitive and regulatory forces shaping the next phase of market development.
Market Trajectory and the 2026 Inflection Point
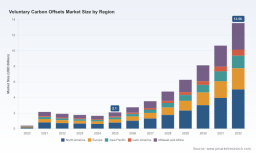
The historical record reveals a market that has matured through cycles of expansion, contraction, and reevaluation. Between 2020 and 2025, total revenue progressed from approximately $0.4 billion to $2.1 billion, reflecting both surging corporate interest in climate commitments and subsequent corrections driven by concerns over credit quality and additionality. The trajectory is not linear. Periods of rapid growth were followed by consolidation and a sharper focus on verification standards, project selection, and methodological rigor.
Looking ahead, the forecast period from 2026 to 2032 signals a reacceleration under clearer structural conditions. The market is projected to grow at a compound annual growth rate of 30.7%, reaching a revenue base of approximately $2.75 billion in 2026 and expanding to $13.56 billion by 2032. These figures are not merely top-line indicators; they encode underlying shifts in demand composition, project type preferences, and regional participation patterns. For 2026 planning cycles, the inflection point matters because it coincides with a wave of regulatory clarity, new methodology rollouts, and a recalibration of corporate offsetting strategies. Organizations that understand the shape of this growth, rather than simply its magnitude, will be better positioned to allocate budgets, structure procurement contracts, and align offsetting activities with broader decarbonization pathways.
The research frames this growth within strategic questions that matter for 2026 decision-making: which project categories are gaining share, how does demand differ across application areas, and what does regional participation reveal about supply availability and pricing dynamics? The answers are developed in depth within the report, where granular segmentation data is presented alongside qualitative analysis of market drivers and constraints.
Regulatory and Structural Dynamics Reshaping the Landscape
The voluntary carbon market does not operate in a vacuum. Recent developments have introduced both pressure and opportunity, reshaping the economics of credit procurement and the criteria for high-integrity sourcing. A series of regulatory and institutional milestones during late 2025 and early 2026 stand out as particularly consequential.
Voluntary Carbon Offsets Market
The European Commission's adoption of rules for an EU-wide voluntary certification framework for carbon removals and carbon farming under the CRCF Regulation marks a new era of institutional oversight. This framework, accompanied by Implementing Regulation (EU) 2025/2358 introducing transparency standards for voluntary carbon credit certification schemes, elevates the bar for documentation, traceability, and disclosure. For companies sourcing credits in or linked to European markets, these standards create both compliance considerations and competitive differentiators for providers who can demonstrate alignment.
Simultaneously, the Integrity Council for the Voluntary Carbon Market (ICVCM) has advanced the Core Carbon Principles as a global benchmark for high-integrity voluntary carbon credits. Assessment activity ongoing through 2025 has begun to separate projects and methodologies that meet these benchmarks from those that do not. This process is influencing buyer behavior, as organizations increasingly seek credits with verifiable integrity credentials to protect against reputational and regulatory risk.
Methodological innovation continues to progress. Verra's announcement of the forthcoming Scope 3 Standard Program, intended to support corporate supply chain decarbonization using voluntary carbon credits, signals an expansion of use cases beyond direct operational offsets. In parallel, Equitable Earth launched its new REDD+ methodology, M002, aimed at addressing quality issues in voluntary carbon markets, while the Scaling JREDD+ Coalition, involving the World Bank and the Initiative for Sustainable Forest Landscapes, was launched to advance jurisdictional REDD+ in voluntary markets. These developments reflect a broader push toward jurisdictional approaches and higher-quality nature-based solutions.
Price dynamics remain a critical consideration. Typical voluntary carbon offset prices range from $5 to $10 per tonne for nature-based credits, with tech-based carbon dioxide removal credits exceeding $170 per tonne. This wide range underscores the importance of understanding credit type, project maturity, co-benefit profiles, and certification status when interpreting market levels. The report situates these pricing observations within a broader analysis of supply constraints, demand elasticity, and the strategic implications for procurement planning.
What the Report Delivers: Operational Content for 2026 Planning
This research is structured to support actionable decision-making rather than abstract market description. The report's content is designed to help organizations translate market signals into procurement strategies, risk assessments, and investment theses.
Key components include a detailed segmentation analysis covering regions, project types, and application areas. The segmentation reveals how demand is distributed across corporate net-zero commitments, energy and utilities, consumer goods and retail, and agriculture, while also distinguishing between avoidance and reduction projects and removal projects. Regional participation patterns are examined to highlight where supply and demand dynamics are converging or diverging. Rather than presenting these splits as static figures, the analysis connects them to underlying structural factors such as regulatory exposure, corporate reporting requirements, and project pipeline availability.
Carbon Offset/Carbon Credit Trading Service Market
The report also provides a comprehensive competitive landscape assessment. Profiles of leading market participants cover their operational focus, geographic footprint, and strategic positioning. Coverage spans organizations that provide voluntary carbon offset credits and integrated sustainability consulting, those developing high-integrity project portfolios, and firms specializing in renewable energy, energy efficiency, conservation forestry, and reforestation-based offsets. This competitive mapping helps buyers evaluate supplier capabilities, understand differentiation in sourcing models, and anticipate how market participants may adapt to new regulatory and integrity standards.
Beyond company profiles, the study incorporates recent developments and industry context to frame near-term market behavior. This includes regulatory milestones, methodology launches, coalition formations, and certification assessments that are actively reshaping sourcing strategies. By integrating these developments with historical and forecasted market data, the report enables readers to interpret short-term fluctuations within a longer-term structural context.
Competitive Positioning and Strategic Implications
The voluntary carbon offsets market features a diverse set of participants, each with distinct sourcing models, project specializations, and geographic strengths. Understanding this landscape is essential for buyers seeking to construct resilient procurement portfolios and for investors or partners evaluating market entry and expansion opportunities.
Among the companies profiled, several exhibit clear strategic orientations. Some providers emphasize integrated sustainability consulting alongside offset credit supply, positioning themselves as advisors rather than purely transactional intermediaries. Others focus on high-integrity projects, leveraging rigorous certification and transparent project selection as differentiators. Specialized players concentrate on particular project categories, such as renewable energy and energy efficiency, conservation forestry, or reforestation and conservation, aligning their offerings with specific buyer preferences and co-benefit considerations.
This diversity of models matters because market conditions increasingly reward specialization and integrity. As transparency standards tighten and integrity benchmarks gain traction, suppliers with robust project pipelines, clear certification pathways, and strong documentation practices are likely to gain relative advantage. Conversely, the market may consolidate around providers who can demonstrate alignment with emerging regulatory expectations, including the EU certification framework and ICVCM assessments. The report's competitive analysis highlights these dynamics, offering readers a basis for evaluating supplier selection criteria and anticipating shifts in market share.
Market concentration data provides additional context. The combined share of the top three and top five participants indicates a landscape that remains relatively fragmented at the top, with room for both established players and new entrants to influence sourcing flows. This fragmentation suggests that buyers have meaningful choice, but it also underscores the importance of due diligence in assessing credit quality, project documentation, and supplier reliability.
Navigating 2026 Decision Points with Structured Intelligence
For organizations making decisions in 2026, the voluntary carbon market presents a set of interconnected challenges and opportunities. Procurement teams must balance cost considerations against integrity requirements. Strategy teams must align offsetting activity with broader decarbonization goals, including supply chain emissions addressed through emerging standards. Risk teams must monitor regulatory developments, certification assessments, and price volatility across different credit types.
The report supports these decisions by connecting market data to practical questions. It helps clarify where demand is originating, how project types are evolving, and what regional patterns imply for supply access. It frames competitive dynamics in a way that informs supplier evaluation and portfolio construction. And it embeds recent regulatory and methodological developments within a market context, enabling readers to anticipate how standards, transparency requirements, and new methodologies may influence credit availability and pricing over the forecast period.
Importantly, the research is designed to reveal enough structural insight to guide strategy while reserving detailed segmentation figures and granular breakdowns for the full analysis. This approach reflects the reality that the most consequential decisions often depend on precise data that must be evaluated in context. Readers seeking to map out procurement pathways, assess regional supply considerations, or benchmark competitive positioning will find the complete segmentation data and supporting analysis essential to their work.
Accessing the Full Strategic Brief
The voluntary carbon offsets market is moving from a phase of experimentation and volatility toward one defined by integrity standards, regulatory clarity, and more disciplined procurement. For 2026 decision-makers, that transition creates both the need and the opportunity to act on robust market intelligence.
PW Consulting's Voluntary Carbon Offsets Market research provides the depth required to navigate that transition. By combining historical trajectory, forecast projections, segmentation analysis, competitive profiling, and recent industry developments, the report equips leaders with a structured view of where the market has been and where it is heading. The full analysis includes the detailed data necessary to convert strategic insight into procurement plans, supplier evaluations, and investment judgments.
To access the complete segmentation data, regional and application breakdowns, and the full competitive landscape assessment, readers are encouraged to visit the source page for this market research. The complete report provides the granular intelligence needed to support confident, evidence-based decisions throughout 2026 and the forecast period ahead.
For detailed analysis of this topic, please visit the official page: Voluntary Carbon Offsets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com