

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Heat Exchanger Market Hits $20.01 Billion in 2025, Forecast to Reach $29.47 Billion by 2032

Navigating Thermal Efficiency: Strategic Imperatives in the 2026 Heat Exchanger Market
In the complex ecosystem of global industrial infrastructure, the heat exchanger stands as a silent yet critical enabler of thermal efficiency. From the massive condensers in nuclear power plants to the compact units cooling data centers, these components dictate the operational viability of countless processes. As we move deeper into the decade, the Heat Exchanger Market is undergoing a transformation driven by capital intensity, regulatory tightening, and shifting geographic demand. PW Consulting's latest market research provides a comprehensive lens through which businesses can view these dynamics, offering the granular intelligence necessary to navigate the forecast period from 2026 through 2032.
This report is not merely a collection of statistics; it is a strategic toolkit designed for executives, procurement leaders, and investors. By synthesizing historical performance with forward-looking models, we uncover the layers of opportunity and risk that define the current landscape. The following analysis outlines the core components of this research, highlighting why immediate access to detailed market intelligence is vital for maintaining competitive advantage in an industry characterized by high concentration and evolving technical standards.
Market Trajectory and Economic Scale
The industrial sector values stability, yet the heat exchanger market has demonstrated consistent upward momentum. Based on historical analysis covering the period from 2020 to 2025, the market has scaled significantly, reflecting broader industrial output and energy demands. Our research models project this trajectory to continue, with the overall market valuation expected to reach approximately 20.83 billion USD in 2026. This figure serves as a critical baseline for annual budgeting and capital expenditure planning.
Looking further ahead, the forecast extends to 2032, where the market size is anticipated to expand substantially, driven by sustained investment in power generation and processing facilities. The Compound Annual Growth Rate (CAGR) during this forecast period is estimated at 5.5 percent. While this growth rate indicates a mature but healthy industry, it masks significant variations across different technology types and application sectors. Understanding where this growth concentrates is essential for allocating resources effectively. The report details the revenue units in billions of USD, providing a clear monetary framework for assessing market potential without getting lost in vague projections.
Segmentation and Technology Focus
The market is divided into distinct technological categories, each serving specific industrial needs. Our analysis breaks down the landscape by type, including Shell & Tube, Plate & Frame, Air Cooled, Cooling Towers, and Others. Each segment presents unique manufacturing challenges and end-user requirements. For instance, Shell & Tube units remain dominant in heavy industry, while Plate & Frame solutions are critical for HVAC and refrigeration efficiency. The research provides a deep dive into the revenue contribution of each type, allowing firms to benchmark their portfolio against market share leaders.
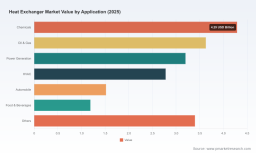
Beyond technology, the application spectrum is equally diverse. Key sectors include Chemicals, Oil & Gas, Power Generation, HVAC, Automobile, Food & Beverages, and Others. The demand profile varies sharply between these verticals. Power generation and chemical processing typically require robust, high-pressure equipment, whereas HVAC and food applications demand precision and hygiene compliance. The report elucidates how these application verticals influence procurement cycles and specification requirements. By understanding the revenue splits across these segments, companies can identify underserved niches or over-saturated zones before committing to new product lines.
Geographic Dynamics and Regional Hubs
Geography plays a pivotal role in market accessibility and cost structures. The research provides a detailed breakdown of revenue by region, covering North America, Europe, Asia Pacific, Latin America, and Mideast and Africa. Asia Pacific currently represents a significant volume of activity, reflecting rapid industrialization and infrastructure development. Europe and North America maintain strong positions, driven by mature industrial bases and strict regulatory environments that necessitate high-quality, compliant equipment.
The report explores regional growth drivers, such as local manufacturing capabilities and import dependencies. For companies looking to expand their footprint, understanding the specific revenue contribution of each region is vital. It informs decisions regarding distribution networks, local partnerships, and pricing strategies. The data reveals where demand is most price-sensitive and where premium positioning is viable. This geographic intelligence is crucial for multinational corporations seeking to optimize their supply chains and for domestic players evaluating export opportunities.
Heat Exchanger Market
Competitive Landscape and Concentration
The Heat Exchanger Market is characterized by a high degree of concentration. Our analysis indicates that the top three competitors hold a CR3 of 65.0 percent, while the top five firms account for a CR5 of 78.0 percent. This level of consolidation suggests that market leadership is well-established, and new entrants face significant barriers related to scale, certification, and existing customer relationships. However, within the broader ecosystem, there are numerous specialized players carving out niches through customization and service excellence.
The report profiles key companies that define the competitive arena. Graham Corporation, headquartered in Batavia, NY, focuses on large shell and tube heat exchangers for industrial and power generation applications. Kelvion, Inc., based in Catoosa, OK, specializes in plate and fin heat exchangers for HVAC, refrigeration, and industrial processes. Perry Products Corporation in Newark, NJ, offers custom shell and tube heat exchangers and ASME-certified thermal fluid systems. These profiles extend to a wide array of specialists. Harris Thermal Transfer Products in Medford, WI, provides industrial heat exchangers for thermal management and process heating. Ward Vessel & Exchanger in New Kensington, PA, manufactures custom shell and tube heat exchangers and pressure vessels to ASME standards.
Further down the list, SPG Dry Cooling in Bridgewater, NJ, delivers dry cooling systems and heat exchangers for power plants and industrial applications. Bitzer US, Inc. in Peachtree Corners, GA, focuses on refrigeration and compressor heat exchangers. Taylor Forge Engineered Systems, Inc. in Paola, KS, supplies engineered heat transfer systems for industrial and refining sectors. American Exchanger Services, Inc. in Hartford, WI, distinguishes itself through heat exchanger services, repair, and maintenance. Croll Reynolds Company, Inc. in Parsippany, NJ, provides vacuum and heat exchange equipment for chemical and industrial processes. DC Fabricators Inc. in Florence, NJ, handles custom fabrication of heat exchangers and pressure vessels.
International presence is also significant. Holtec International in Camden, NJ, specializes in nuclear and industrial heat exchangers. Kansas City Deaerator Company in Stilwell, KS, focuses on deaerator and heat recovery heat exchangers. Maarky Thermal Systems in Cherry Hill, NJ, offers thermal management and heat exchange solutions. Sterling Deaerator Company in Cumming, GA, supplies deaerator heat exchangers for power and industrial use. Thermal Engineering Int'l (USA) Inc. in La Palma, CA, provides heat recovery and thermal engineering systems. On the global stage, Alfa Laval AB in Tullinge, Sweden, is known for gasketed plate and frame heat exchangers for industrial and HVAC applications. Danfoss A/S in Nordborg, Denmark, produces brazed plate heat exchangers for refrigeration and cooling systems. SPX Flow, Inc. in Charlotte, NC, manufactures scraped surface and industrial heat exchangers for food, beverage, and processing. WCR Heat Exchangers in Xenia, OH, is a key player in plate heat exchangers and replacement parts.
Understanding the specific offerings and geographic footprints of these entities is essential for competitive positioning. The report analyzes how these companies interact, compete, and collaborate within the supply chain.
Recent Developments and Industry Momentum
Market dynamics are frequently shifted by strategic moves from key players. Our research tracks recent developments that signal broader industry trends. In October 2025, WCR Heat Exchangers opened the largest U.S. plate heat exchanger manufacturing facility in Xenia, Ohio, featuring 212,000 square feet of capacity and multi-shift operations. This expansion underscores the demand for domestic manufacturing capacity and supply chain resilience.
Similarly, in January 2026, Danfoss began production at a new Monterrey facility in Mexico for brazed plate heat exchangers. This move aims to improve North American supply reliability, reflecting a trend toward nearshoring critical thermal components. Furthermore, in December 2025, SWEP introduced B327 and B224 brazed plate heat exchanger models specifically targeting data center cooling and district energy applications. This product launch highlights the growing intersection between thermal management and the digital infrastructure boom.
Looking forward, the Shanghai International Heat Exchanger & Heat Transfer Technology Expo, scheduled for June 2026, is set to feature new heat exchanger equipment, technologies, and materials from over 800 companies. As the leading China event for the sector, this exhibition represents a critical touchpoint for monitoring innovation pipelines and supplier networks in the Asia Pacific region. These events are not isolated; they are indicators of where capital is flowing and what technologies are gaining traction.
Regulatory, Material, and Cost Dynamics
Operating in the heat exchanger market requires navigating a complex web of regulations and cost factors. Raw material fluctuations have a direct impact on pricing and margins. According to the California Energy Commission, metallic heat exchanger costs have increased from less than 100 USD per kilowatt thermal to between 500 and 1000 USD per kilowatt thermal. This substantial rise affects project economics and necessitates careful lifecycle cost analysis.
Graphite Heat Exchanger Market
Regulatory compliance remains a non-negotiable aspect of fabrication and sales. ASME U, S, and R stamps are required for pressure vessel and heat exchanger fabrication under federal and state mechanical codes. Additionally, TEMA standards govern the mechanical design and fabrication of shell and tube heat exchangers worldwide. For HVAC and refrigeration sectors, AHRI certification programs for brazed and fusion-bonded plate heat exchangers ensure compliance with liquid-to-liquid heat transfer standards. The report details how adherence to these standards impacts manufacturing costs and market access.
Trade dynamics also influence the market. Industry Market Data projects substantial increases in U.S. imports of heat exchange units classified under HTS 8419.50.10 and 8419.50.50 through 2025. This data point, sourced from the U.S. Department of Commerce Bureau of Industry and Security, suggests shifting supply chain dependencies that companies must monitor to avoid disruption. Understanding these regulatory and material pressures is key to pricing strategy and risk management.
Strategic Value for 2026 Decision-Makers
The primary objective of this research is to empower decision-makers with actionable intelligence. In an environment defined by 5.5 percent CAGR and a total market size approaching 30 billion USD by 2032, the difference between capturing market share and losing ground often lies in the details. The report provides the segmentation splits, regional breakdowns, and competitor profiles necessary to validate strategic hypotheses.
For procurement managers, the data offers benchmarks for negotiations and supplier selection. For investors, it clarifies growth vectors and risk concentrations. For manufacturers, it highlights capacity planning needs and technology investment priorities. The high market concentration indicates that partnership strategies and M&A considerations are as important as organic growth plans.
PW Consulting's Heat Exchanger Market research compiles these elements into a cohesive narrative. We invite you to explore the full report to access the complete dataset, including specific revenue units for each segment and region, detailed company profiles, and in-depth analysis of regulatory impacts. The insights contained within are designed to transform uncertainty into structured opportunity. Secure your copy today to ensure your organization is aligned with the thermal trends shaping the next decade of industrial performance.
For detailed analysis of this topic, please visit the official page: Heat Exchanger Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com