

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Spray Dryer Market Hits $6.59B in 2025, Projects 6.51% CAGR Through 2032

Navigating the Spray Drying Landscape: Strategic Imperatives for 2026 and Beyond
The global spray dryer market is entering a phase of disciplined expansion. Between 2020 and 2025, industry valuations climbed from 4,617.0 million USD to 6,590.0 million USD, reflecting a compound annual growth rate of 6.51 percent across the forecast horizon extending to 2032. This trajectory is not merely a function of incremental demand. It signals a structural recalibration of how powdered intermediates, active ingredients, and consumer-ready formulations are engineered, scaled, and commercialized. For executives mapping capital allocation, product roadmaps, and supply chain resilience in 2026, understanding the operational and regulatory forces shaping atomization technology has shifted from a technical consideration to a board-level priority.
The Trajectory: From Recovery to Sustained Expansion
The historical record from 2020 through 2025 demonstrates how quickly industrial and consumer-facing sectors can amplify throughput when formulation economics favor dry powder architectures. After a 2021 peak, the market experienced a brief contraction in 2022 before resuming a steady upward path, culminating in an estimated valuation above the 6,000 million USD threshold. The forward projection maintains this momentum, with valuations anticipated to surpass the 10,000 million USD mark by the early 2030s. This expansion is anchored in three interconnected drivers: the migration of traditional liquid or slurry processes toward powder-based formats, the integration of precision drying into continuous manufacturing pipelines, and the increasing requirement for batch-to-batch reproducibility in highly regulated categories. Companies that rely on legacy single-stage drying or outsourced powder conversion are finding that capital efficiency, shelf-stability requirements, and cold-chain compression are collectively pulling atomization capabilities inward, closer to the formulation stage.
Yet the headline trajectory only tells part of the story. The operational reality of spray drying remains heavily influenced by energy intensity, capital expenditure cycles, and the specialized labor required to maintain sanitary and process-valid conditions. Large-scale industrial units routinely involve multi-million-dollar investments, and the ongoing operational profile demands trained personnel for routine maintenance, cleaning protocols, and sanitation routines. These structural cost dynamics mean that capacity decisions cannot be decoupled from efficiency modeling, utility pricing, and the long-term total cost of ownership. Executives evaluating expansion or retrofit programs must weigh not only throughput ceilings but also the operational discipline required to sustain them. The market’s growth is real, but it rewards disciplined engineering rather than speculative overbuilding.
Competitive Architecture and Strategic Positioning
The competitive landscape is characterized by a high degree of consolidation among tier-one suppliers. The top three firms collectively command an estimated 68.5 percent of market share, while the leading five players extend that influence to 78.2 percent. This concentration indicates that scale, engineering heritage, and application-specific process knowledge create meaningful barriers to entry. It also means that late-stage entrants or commoditized hardware suppliers face mounting pressure to differentiate through automation, integration, and lifecycle support rather than equipment price alone.
Several companies define the current architecture of the sector. GEA Group AG, headquartered in Düsseldorf, Germany, provides specialized spray drying solutions spanning dairy, food ingredients, pharmaceutical, and instant coffee production, with GEA NIRO® plants serving as a reference point for integrated drying and particle processing. SPX FLOW, Inc., based in Charlotte, North Carolina, offers Anhydro-branded spray dryers tailored to food, dairy, and pharmaceutical powders, emphasizing advanced atomization and process technology. Tetra Pak International SA, operating from Pully, Switzerland, delivers automated spray drying systems for dairy, whey, and plant-based powders using Wide Body technology, aligning drying capability with broader processing and packaging ecosystems.
Beyond the large-scale industrial leaders, the market includes firms that address adjacent but strategically important niches. BÜCHI Labortechnik AG, headquartered in Flawil, Switzerland, manufactures laboratory and pilot-scale spray dryers for research, quality control, and small-scale pharmaceutical and chemical applications, enabling formulation teams to de-risk scale-up before committing to full production assets. VetterTec GmbH, based in Kassel, Germany, supplies customized industrial spray dryers for food, chemical, and starch industries, offering pilot to full-scale units built on more than forty years of experience. Pulse Combustion Systems, located in Arizona, develops pulse atomization spray dryers aimed at energy-efficient drying across food, chemical, mineral, and pharmaceutical powders, positioning energy performance as a core differentiator. Dedert Corporation, based in Homewood, Illinois, supplies U.S.-made spray dryers for starch, food, and industrial powder production. Changzhou Jinqiao Spray Drying and Engineering Co., Ltd. operates from Changzhou, Jiangsu, China, manufacturing milk and food spray dryers with precision engineering and automation designed for dairy applications.
Recent activity underscores how these players are positioning themselves for the next cycle. In August 2025, GEA Group AG introduced an advanced pharmaceutical spray dryer to Chugai Pharmaceutical, targeting enhanced product development and manufacturing capabilities. In March 2025, RISE PFI installed a new spray dryer in a laboratory setting to improve the efficient separation of solids from liquids or suspensions into powder. These developments are indicative of two broader trends: first, the continued push to bring higher-performance drying into specialized formulation and R&D environments, and second, the growing expectation that drying equipment will be evaluated not just for throughput but for reproducibility, modular integration, and process control.
Regulatory and Operational Dynamics Redefining Requirements
The operating environment for spray drying infrastructure is being reshaped by regulatory expectations and process-validation demands. As of February 2, 2026, the FDA Quality Management System Regulation became effective, incorporating ISO 13485:2016 for medical device manufacturers, including spray dryers used in pharmaceutical production. This alignment raises the bar for documentation, design controls, and management-system rigor across equipment that interfaces with regulated product streams. In parallel, industry standards for process validation and design space optimization under quality-by-design principles continue to be required under FDA guidance for spray dryers in pharmaceutical applications. For manufacturers, this means that drying is no longer treated as an isolated unit operation. It must be demonstrably integrated into a controlled, validated, and auditable process architecture.
These dynamics carry direct implications for sourcing, commissioning, and lifecycle management. Equipment that supports traceability, configurable control logic, and robust cleaning and sanitation pathways is increasingly favored, especially where formulation integrity and cross-contamination risk must be tightly managed. At the same time, the necessity for trained personnel to perform regular maintenance, cleaning, and sanitation highlights a labor dimension that is often underestimated during feasibility studies. The operational burden of sustaining compliant, high-uptime drying lines means that service networks, operator training, and remote diagnostics are becoming part of the competitive value proposition rather than afterthoughts.
Energy and capital intensity remain foundational considerations. Spray drying is inherently power-demanding, and the scale required for industrial throughput often translates into significant capital outlays and operating costs. As utilities pricing and sustainability mandates continue to influence return-on-investment calculations, procurement teams are scrutinizing atomizer selection, thermal efficiency, and integration with broader plant energy systems. This is where differentiated technologies and customized engineering can shift the economics of a project, but only when they are evaluated against real process requirements rather than isolated equipment specifications.
Segment Architecture and Decision-Relevant Trade-offs
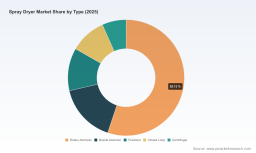
The market’s structure is divided across type, application, and geography, and each lens reveals different strategic trade-offs. By type, the landscape includes rotary atomizer, nozzle atomizer, fluidized, closed loop, and centrifugal configurations. Each technology family carries distinct implications for particle size distribution, thermal exposure, feedstock viscosity tolerance, and operational flexibility. By application, demand is anchored in food and dairy, pharmaceutical, chemical, and other end-use categories, where formulation goals, regulatory exposure, and throughput requirements differ materially. By region, activity is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, reflecting varied manufacturing bases, procurement norms, and industry maturity levels.
Spray Dryer Market
These structural divisions matter because they shape not only where demand originates, but how equipment should be specified. A formulation team working with heat-sensitive actives will evaluate drying architecture differently from a producer focused on high-volume dairy powder or starch derivatives. A laboratory or pilot-scale program will prioritize reproducibility and rapid changeover, while an industrial line will emphasize uptime, utility efficiency, and integration with upstream and downstream modules. The strategic question for 2026 is not which segment is largest in isolation, but which combination of type, application, and operating context aligns with a company’s product roadmap, compliance posture, and scale-up cadence.
Why the 2026 Market Research Is Differentiated for Decision-Making
The Spray Dryer Market research is designed to convert these dynamics into actionable intelligence. Rather than presenting a static snapshot, the report maps the path from historical performance through the 2026 to 2032 forecast window, allowing leadership teams to stress-test capacity plans, product entry timing, and supplier selection against a structured forward view. The analysis integrates process technology considerations, application-driven demand patterns, and competitive positioning into a single decision framework, helping stakeholders connect equipment selection to broader commercial objectives.
Food Dryer Market
Practically, the report supports multiple use cases. For capital planning and plant expansion, it provides a structured basis for evaluating whether in-house drying capability, modular pilot assets, or outsourced conversion offers the better risk-adjusted path. For product development teams, it contextualizes how atomization choices influence formulation feasibility, scale-up risk, and process validation burden. For procurement and engineering leaders, it frames supplier evaluation around integration, automation, service readiness, and alignment with evolving regulatory expectations. For corporate strategy and M&A functions, it identifies where consolidation dynamics and technology differentiation are likely to shape vendor resilience and partnership value.
The research also addresses the practical realities that often determine project outcomes. It examines how energy intensity, labor requirements, maintenance discipline, and sanitation protocols interact with equipment architecture and total cost of ownership. It situates recent equipment installations and product introductions within the broader demand environment, helping readers distinguish one-off announcements from durable shifts in capability expectations. And it places regulatory developments, including quality management system alignment and process validation standards, in the context of supplier qualification and long-term operating risk.
Organizations that use this intelligence effectively will not simply track market size. They will use it to prioritize where to invest, which operating parameters to optimize, and how to structure supplier relationships so that drying capability becomes a source of competitive advantage rather than a constraint. The most consequential decisions in 2026 will be made by teams that can connect particle engineering, compliance readiness, and commercial strategy into a coherent plan.
Connect to the Full Intelligence Package
The Spray Dryer Market research translates a complex intersection of technology, regulation, and demand into a focused decision tool for 2026 and the forecast period ahead. It is built to support capacity strategy, supplier evaluation, application planning, and investment prioritization with a clear view of where the market is headed and why. To access the complete segmentation analysis, full forecast pathway, competitive profiling, and operational-risk assessment that support these conclusions, please visit the PW Consulting market research page for the complete report and detailed executive summaries.
For detailed analysis of this topic, please visit the official page: Spray Dryer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com