

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Lithium Ion Battery Market Hits $325.77M in 2025, Forecasts 17.52% CAGR Through 2032

Strategic Intelligence for the Decisive Decade: Inside the 2026 Global Lithium-Ion Battery Market Research
The lithium-ion battery industry has transitioned from a phase of rapid, speculative expansion into a mature, capital-intensive arena where competitive advantage is dictated by supply chain resilience, technological precision, and strategic foresight. For executive teams navigating capital allocation, product roadmaps, and geographic positioning, the margin for strategic missteps has narrowed considerably. PW Consulting is proud to introduce our latest comprehensive analysis of the global Lithium-Ion Battery Market, a diagnostic framework engineered specifically to equip leadership teams with the operational clarity required to make high-conviction decisions throughout 2026 and beyond.
Lithium-ion Battery Recycling Market
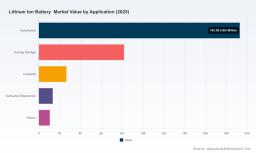
Over the past half-decade, the sector has consistently demonstrated a compound annual growth trajectory of 17.52 percent, with market valuation crossing the 325.77 million USD threshold in 2025 and continuing its upward march toward a projected 663.71 million USD by 2032. These figures, however, represent only the surface architecture of a profoundly intricate ecosystem. Behind the headline metrics lies a competitive matrix defined by intensifying vertical integration, divergent cathode CHEMISTRY adoption curves, shifting regulatory guardrails, and raw material supply chains that remain both critical and structurally fragile. Our research moves decisively past superficial valuation models to deliver an actionable, execution-ready intelligence architecture that maps market velocity against real-world operational complexity.
Decoding Market Architecture for Executive Decision-Making
At the strategic core of this study lies a granular examination of the competitive and operational forces that will determine enterprise profitability over the forecast horizon. We have systematically mapped the primary commercial pathways across multiple critical dimensions, tracing how chemistry selection, end-use case prioritization, and regional deployment patterns are actively reshaping competitive positioning. Rather than offering static snapshots, the analysis treats these variables as dynamic levers, providing a contextual framework that executives can stress-test against internal capacity rollouts, procurement strategies, and partnership pipelines. This structure is deliberately designed to answer the strategic questions that typically surface during quarterly planning cycles: where will demand actually concentrate, which manufacturing pathways offer sustainable margin defense, and how should organizations hedge against supply-side volatility without compromising long-term growth targets.
Our methodological framework also integrates forward-looking scenario modeling, allowing leadership to evaluate multiple deployment trajectories under varying macroeconomic and policy conditions. By synthesizing historical performance data with emerging market signals, the report delivers a structured lens for capital allocation, R&D prioritization, and market-entry timing. The objective is not simply to forecast where the industry is heading, but to equip decision-makers with the analytical rigor required to navigate ambiguity, reallocate resources efficiently, and secure first-mover advantage in high-growth corridors before competitive saturation sets in.
What the Full Report Delivers: Operational Depth and Strategic Clarity
Leaders evaluating this intelligence should expect an end-to-end operational blueprint rather than a conventional market summary. The complete publication dissects the competitive hierarchy, technology transition vectors, manufacturing footprint evolution, and demand-side procurement behaviors across every major value chain node. The report is structured to support cross-functional alignment, enabling strategy teams, engineering leadership, procurement directors, and investor relations stakeholders to operate from a shared factual baseline.
Key analytical pillars embedded in the full study include:
- Segmentation Deep Dives: A structured evaluation of chemistry pathways, application-driven demand clusters, and regional deployment sequences, revealing where pricing power, capacity utilization, and supply chain leverage are being actively consolidated.
- Detailed profiling of the market's most influential manufacturers, with emphasis on vertical integration strategies, cell-format specialization, and regional manufacturing investments that are actively reshaping the industry's center of gravity.
- Forward-looking assessments of material availability, cell-design evolution, and commercialization timelines, providing the strategic context needed to anticipate bottlenecks, secure procurement windows, and align product roadmaps with credible development trajectories.
- An integrated review of emerging compliance frameworks and transport constraints that directly affect global distribution, inventory planning, and cross-border partnership design.
- A multi-horizon projection architecture that enables leadership to model capacity expansion, demand elasticity, and competitive response under baseline and stress-case assumptions.
Each analytical layer is designed to translate complex industry signals into explicit, boardroom-ready implications. Readers will leave with a defined understanding of which strategic moves will compound value over the forecast window and which legacy assumptions are increasingly misaligned with the evolving market structure.
Competitive Dynamics: The Strategic Moats Being Forged Today
The competitive architecture of the lithium-ion battery sector is no longer defined solely by cell performance metrics. Today's winning organizations are those executing multi-vector strategies that combine manufacturing scale, chemistry agility, geographic positioning, and ecosystem partnerships. The full report profiles the industry's most influential incumbents, examining how each is engineering defensible advantages in an increasingly polarized environment.
Several strategic archetypes have emerged clearly. Leading cell manufacturers with full vertical integration from raw materials through system-level deployment are leveraging control over the upstream value chain to stabilize margins and accelerate development cycles. At the same time, specialized producers focused on distinct form factors, such as high-performance prismatic or cylindrical cells, are deepening their alignment with premium automotive programs and specialized storage applications. Other organizations are differentiating through chemistry emphasis, whether advancing high-nickel formulations for energy-dense mobility use cases or scaling LFP-based platforms that prioritize safety, cycle life, and cost predictability. The competitive tension between these approaches is intensifying, and understanding where each player is investing, partnering, and defending is essential for any enterprise seeking to position itself intelligently within the value chain.
The pace of recent activity underscores how rapidly the landscape is being reconfigured. Strategic contract awards, product platform unveilings, cross-industry partnerships, and major capacity expansions are actively reshaping regional supply balances and customer relationships. These developments are not isolated headlines; they signal durable shifts in manufacturing geography, program partnerships, and technology commercialization priorities. Our research contextualizes these moves within broader competitive dynamics, helping leaders distinguish between tactical positioning and structural advantage, and enabling them to anticipate which partnerships, capacity corridors, or technology bets will define the next cycle of consolidation and growth.
Lithium Ion Battery Market
Macro Forces and Operational Realities Shaping the 2026–2032 Window
No strategic assessment of this market is complete without a realistic engagement with the external forces that constrain and enable growth. The full study integrates several macro-level dynamics that executives must factor into scenario planning and operational design. On the materials side, lithium availability and pricing remain central variables. Worldwide production expanded meaningfully during the most recent reporting cycle, reflecting the sector's relentless demand pull, while domestic pricing patterns for battery-grade inputs have experienced measurable fluctuation across the year. These movements carry direct implications for procurement strategy, contract structuring, and manufacturing cost models. Organizations that treat raw material exposure as a static risk item rather than a dynamic variable risk mispricing their product pipelines and underinvesting in supply diversification.
Regulatory and logistics frameworks are equally consequential. From the outset of 2026, stricter transport constraints have governed the shipment of lithium-ion batteries and battery-powered equipment, imposing new limits on state of charge for air transport and prompting necessary adjustments in global distribution logic, inventory positioning, and fulfillment design. Simultaneously, policy-driven standards are accelerating technology commercialization roadmaps in key development centers, establishing formal benchmarks for next-generation battery architectures and influencing R&D prioritization across the industry. These regulatory signals are not peripheral; they actively shape where and how manufacturers scale, which form factors gain commercial traction, and how quickly advanced chemistry pathways can move from prototype to production.
Compounding these forces is the broader reality of a market that remains highly concentrated at the top. A relatively small group of leading enterprises continues to command a substantial share of global revenue, reinforcing the strategic importance of partnership selection, supplier diversification, and differentiated value propositions for organizations operating outside the dominant tier. For entrants, joint venture participants, and downstream integrators, understanding the barriers to scale and the leverage points available within an asymmetric competitive structure is critical to designing realistic growth strategies.
Why This Research Is a Strategic Imperative for 2026 Decision-Makers
The global lithium-ion battery market will not reward passive observation. As capacity expansions proceed, chemistry portfolios diverge, supply chains recalibrate, and policy regimes tighten, the organizations that thrive will be those capable of converting market intelligence into timely operational action. This publication has been designed to serve as that conversion mechanism. It provides the evidentiary foundation needed to validate capital deployment assumptions, prioritize technology partnerships, anticipate procurement exposure, and refine market-entry or expansion strategies with greater confidence.
More importantly, the study is structured to be actively used rather than passively read. Cross-functional teams can leverage its frameworks to align on strategic priorities, risk officers can map exposure against documented market trajectories, and commercial leaders can identify where demand momentum is genuinely forming versus where narrative outruns fundamentals. In an environment where competitive windows are narrowing and capital efficiency is increasingly scrutinized, the difference between a reactive posture and a proactive one often comes down to the quality and immediacy of the intelligence at hand.
To access the complete segmentation analysis, full competitive profiles, scenario projections, and operational recommendations that will inform your 2026 strategy, we invite you to explore the full report suite on our platform. The macro trajectory is clear; the actionable detail that separates informed execution from speculation is available in the complete publication.
For detailed analysis of this topic, please visit the official page: Lithium Ion Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com