

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Drive Shaft Market Hits $9.03B in 2025, Projected to Reach $12.86B by 2032 at 5.2% CAGR

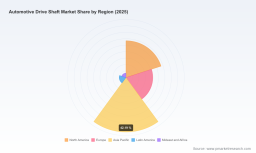
Strategic Imperatives in the Automotive Drive Shaft Market: A 2026 Perspective
The automotive drivetrain landscape is undergoing a structural transformation. As propulsion architectures diversify across internal combustion, hybrid, and fully electric platforms, the drive shaft has evolved from a standardized mechanical component into a differentiated engineering asset. For executives navigating procurement, capacity allocation, and portfolio strategy in 2026, understanding the trajectory of this segment requires more than headline figures. It demands a disciplined examination of material substitution, regional demand migration, OEM validation cycles, and the competitive consolidation reshaping the global supply base.
PW Consulting’s latest Automotive Drive Shaft Market research delivers precisely that operational clarity. Built on a six-year historical baseline and extended through a seven-year forecast horizon, the study translates macroeconomic momentum into actionable deployment frameworks. Below is a structured preview of the analytical architecture, the competitive forces at play, and the strategic questions this intelligence is designed to resolve for 2026 decision-makers.
Executive Trajectory: Market Scale, Growth Cadence, and Structural Inflection
The global automotive drive shaft market has demonstrated consistent expansion over the past half-decade, advancing from approximately 6.9 billion USD in 2020 to a projected 9.03 billion USD in 2025. The forward trajectory indicates a moderate but dependable growth cadence, underpinned by a forecast compound annual growth rate of 5.2 percent through 2032. By the close of the outlook period, market revenue is expected to approach the 13 billion USD threshold.
These aggregate movements, however, mask divergent underlying dynamics. Growth is not distributed uniformly across propulsion types, vehicle classes, or geographic corridors. The shift toward high-angle constant velocity assemblies, lightweight tubular geometries, and integrated e-propulsion coupling mechanisms is redefining volume-to-value ratios across the segment. At the same time, material procurement cycles, regional localization mandates, and OEM platform consolidation are introducing volatility that conventional top-down forecasting struggles to isolate. Our analysis disentangles these forces, mapping where incremental revenue will materialize and where margin compression will test incumbent operating models.
What the Study Covers: Operational Architecture and Decision Frameworks
The research is structured to support cross-functional deployment rather than passive reading. Each section translates market signals into executable levers across product planning, supplier qualification, regional capacity allocation, and risk hedging. The core deliverables include:
- Propulsion-Agnostic Demand Mapping: A systematic evaluation of how drive shaft specifications diverge across ICE, hybrid, and electric architectures, with attention to joint integration, torsional load profiles, and NVH tolerance thresholds that influence validation timelines and bill-of-materials complexity.
- Material and Processing Architecture: A detailed assessment of steel, aluminum, and carbon fiber composite adoption pathways, including the cost implications of lightweighting mandates, supply chain readiness, and the price volatility dynamics that can shift component economics by double-digit annual ranges.
- Application and Platform Prioritization: A comparative review of volume concentration in passenger car programs versus commercial vehicle applications, highlighting where platform commonality, fleet turnover cycles, and service interval expectations drive distinct procurement behaviors.
- Regional Momentum and Localization Logic: A ground-up analysis of demand clustering across major automotive corridors, incorporating OEM sourcing shifts, logistics footprint constraints, and policy-driven content requirements without resorting to superficial regional aggregates.
- Competitive Position Assessment: A structured benchmarking of core suppliers across engineering capability, program win rates, vertical integration depth, and propulsion-agnostic portfolio readiness, enabling readers to evaluate partnership options, displacement risk, and pricing leverage.
- Scenario and Sensitivity Frameworks: Forecast bands tied to adoption velocity, raw material escalation, and regulatory efficiency targets, allowing strategy and finance teams to pressure-test capacity plans, inventory policy, and supplier diversification decisions.
Competitive Landscape: Consolidation, Portfolio Realignment, and Propulsion-Agnostic Positioning
The market’s competitive architecture is characterized by moderate concentration, with the top tier holding a combined share just under twenty-five percent and the extended leadership group approaching twenty-six percent. This fragmented-but-consolidating structure means that scale advantages are real but not absolute, and engineering differentiation remains a decisive credential for program retention and new business acquisition.
GKN Automotive, headquartered in Coventry, has reinforced its position through propulsion-agnostic drive systems that span sideshafts, CV joints, and propeller shafts for ICE, hybrid, and electric platforms. Its engineering emphasis on modular joint architecture and integrated propulsion coupling aligns with OEM demands for platform flexibility and reduced validation fragmentation. Nexteer Automotive, based in Auburn Hills, has pursued a complementary trajectory centered on premium telescopic drive shafts, high-angle CV joints, and driveline systems tailored for OEM applications. In April 2026, the company debuted three driveline technologies aimed at EVs and premium driving experiences across propulsion types, underscoring a strategy that links ride refinement and packaging efficiency with electrification requirements.
Dana Incorporated, operating from Maumee, continues to expand its integrated drivetrain portfolio encompassing axles, driveshafts, and e-propulsion systems for passenger vehicles. Its February 2026 reporting of strong first-quarter results accompanied by a new business win in drivetrain solutions reflects an execution model that pairs component supply with systems-level integration. American Axle & Manufacturing, under the Dauch Corporation banner in Detroit, manufactures driveline and metal-forming components including front and rear axles and driveshafts for global OEMs, leveraging high-volume forming capability and broad program coverage.
Hyundai WIA Corporation, based in Seoul, produces driveline systems and components including drive shafts for passenger vehicles and commercial applications, combining regional manufacturing depth with expanding export-oriented program participation. Neapco Holdings, headquartered in Quakertown, supplies driveline components such as driveshafts and CV joints across OEM and aftermarket channels, maintaining a dual-stream revenue structure that buffers pure OEM cycle exposure.
Cardan Shaft Market
The consolidation trajectory remains a defining feature of the competitive outlook. In January 2026, Dauch Corporation announced a combination with Dowlais Group to integrate GKN Automotive driveline technologies, a move that signals the industry’s push toward broader propulsion-agnostic portfolios and consolidated engineering assets. The strategic implication is clear: suppliers that can span multiple propulsion architectures, sustain validation credibility, and offer packaging-efficient joint and shaft solutions are gaining disproportionate relevance in OEM sourcing decisions.
Automotive Drive Shaft Market
Market Dynamics: Material Substitution, Volatility, and Efficiency Mandates
Three structural forces are reshaping specification decisions and cost planning across the drive shaft segment. First, lightweight aluminum and carbon fiber composites are increasingly specified as standard by EV manufacturers to meet efficiency and emissions requirements. This shift is not a wholesale displacement of incumbent materials; rather, it is a selective migration into programs where packaging constraints, range targets, and NVH performance justify higher unit economics. Steel remains the dominant material for drive shafts due to its strength, toughness, and established supply chain, and its prevalence in high-volume and commercial applications continues to anchor baseline procurement logic.
Second, raw material price volatility for steel, aluminum, and composites can increase component costs by up to fifteen percent annually. This volatility transforms material procurement from a tactical purchasing function into a strategic exposure management discipline. Suppliers and OEM buying organizations alike are responding with hedging structures, dual-source qualification, localized processing footprints, and design-to-cost initiatives that decouple performance requirements from raw input swings. Our study quantifies these exposure pathways and maps mitigation playbooks that have proven effective across recent procurement cycles.
Third, regulatory and efficiency mandates are accelerating engineering tradeoffs. As manufacturers pursue tighter efficiency envelopes, the drive shaft’s role in packaging, rotational mass, joint articulation, and propulsion integration becomes more visible in program economics. The result is a market where specification value is increasingly tied to system-level performance rather than component-level commodity pricing. This dynamic favors suppliers that can demonstrate holistic integration benefits, predictable lead times, and design flexibility across propulsion variants.
Implications for 2026 Strategic Decision-Making
For executives operating in 2026, the drive shaft market presents a dual mandate: capture growth where propulsion transitions and platform commonality converge, while insulating the operating model from material volatility and competitive displacement risk. The study is built to support that balance through several decision lenses.
Procurement and supply chain leaders can use the analysis to evaluate supplier resilience, regional sourcing tradeoffs, and exposure to raw material escalation across steel, aluminum, and composite pathways. Product planning teams can leverage propulsion-specific specification mapping to prioritize validation investments, align joint and shaft architectures with platform roadmaps, and avoid over-indexing on legacy ICE configurations that face diminishing program longevity. Commercial and business development teams can use the competitive benchmarking and recent development timeline to identify partnership opportunities, assess program win probability, and anticipate consolidation-driven portfolio shifts.
The study also provides a structured view of where volume concentration is likely to persist and where application-specific differentiation will command pricing discretion. In passenger car programs, the emphasis continues to lean toward packaging efficiency, high-angle articulation, and propulsion integration across a broad model mix. Commercial vehicle applications, by contrast, remain shaped by durability expectations, service interval economics, and platform durability thresholds that influence component specifications and replacement cycles. Understanding these distinctions is essential for allocating engineering resources, negotiating volume commitments, and structuring aftermarket support where relevant.
Regional demand patterns further complicate the strategic picture. Growth is not simply a function of total vehicle production; it is mediated by localization mandates, OEM sourcing footprints, logistics constraints, and the pace at which new propulsion platforms reach volume production in each corridor. The research maps these influences without reducing them to static regional aggregates, instead highlighting where program activity, supplier presence, and content requirements are likely to shift over the forecast period.
Why This Study Matters Now
Market intelligence is only valuable if it converts into decisive action. The Automotive Drive Shaft Market research is designed to do exactly that: convert a broad growth narrative into procurement logic, supplier strategy, capacity planning, and risk hedging that can be discussed in the boardroom and executed on the plant floor. With a historical foundation spanning 2020 through 2025 and a forecast window extending to 2032, the study provides the temporal context needed to distinguish cyclical noise from structural change. The 5.2 percent CAGR trajectory signals dependable expansion, but the strategic value lies in identifying which subsegments, material pathways, and supplier relationships will capture disproportionate share of that growth.
The preview above highlights the analytical architecture, competitive dynamics, and market forces that define the segment’s current trajectory. It is intended to establish the foundation for a deeper evaluation of where your organization should invest, sourcing options worth qualifying, and competitive threats worth modeling before they materialize. The full study delivers the segmented sizing, regional and application-level breakdowns, supplier share context, scenario analyses, and implementation playbooks necessary to translate these conclusions into specific 2026 actions.
For a complete view of the data architecture, competitive benchmarks, and deployment frameworks, download the full PW Consulting Automotive Drive Shaft Market research. The detailed intelligence is structured to support immediate strategic planning, supplier negotiations, and portfolio decisions with the rigor required for a segment in active transformation.
For detailed analysis of this topic, please visit the official page: Automotive Drive Shaft Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com