

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Robot Tool Changers to Reach $1,350 Million by 2032 at 13.81% CAGR

Strategic Imperatives in the Robot Tool Changers Market: Navigating Growth and Consolidation Through 2032
Market Trajectory and Strategic Context
The global industrial automation landscape is undergoing a structural shift driven by the need for flexible manufacturing systems and rapid production changeovers. At the heart of this transformation lies the robot tool changer market, a critical enabler for maximizing the utility of robotic assets across diverse operational environments. Our latest research provides a comprehensive evaluation of this sector, offering decision-makers a clear view of the momentum building from 2026 through 2032.
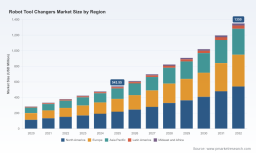
Historical data indicates a robust expansion phase. The market revenue grew from 284.67 million USD in 2020 to 543.55 million USD in 2025. This trajectory underscores a sustained demand for modular automation solutions. As we look toward the forecast period, the market is projected to reach 1,350.0 million USD by 2032. This growth path suggests a compound annual growth rate of 13.81 percent, signaling that investment in tool changing infrastructure is no longer optional but a strategic necessity for maintaining competitive agility.
For enterprise leaders, understanding these macro trends is the first step toward effective capital allocation. The acceleration is not uniform across all sectors, however. The research highlights specific drivers that are shaping the demand curve, requiring stakeholders to differentiate between transient trends and fundamental shifts in production methodology. This insight prepares organizations to anticipate supply chain needs and technology integration requirements before market saturation occurs.
Core Report Content and Operational Insights
Our analysis moves beyond simple top-line numbers to provide actionable intelligence on how technology adoption varies across the value chain. The report dissects the market by type, distinguishing between automatic and manual systems. This distinction is vital for assessing operational efficiency. Automatic systems are increasingly favored in high-volume environments where minimizing downtime is paramount. The data suggests that the automatic segment currently holds a significant share of the revenue, reflecting the industrys push toward lights-out manufacturing and reduced human intervention in repetitive tasks.
Conversely, manual tool changers retain relevance in low-volume, high-mix scenarios where flexibility outweighs the need for full automation. Understanding the balance between these two segments allows manufacturers to right-size their investments. The report details the specific payload capacities and compatibility standards that define these categories, ensuring that procurement teams can align hardware specifications with existing robotic fleets.
Application-wise, the research segments the market to reveal where demand is most concentrated. Automotive and electronics industries remain dominant forces, driving volume through complex assembly and handling tasks. However, significant growth potential is identified in sectors such as chemicals, medical, and food and beverage. Each application presents unique challenges regarding hygiene, precision, and safety. By analyzing these verticals separately, the report helps businesses identify adjacent opportunities and benchmark their performance against industry-specific adoption rates.
Robot Tool Changers Market
Regional dynamics also play a crucial role in market access. While developed regions currently account for a substantial portion of revenue, emerging markets are showing increased interest in automation to offset labor constraints. The report provides a geographic breakdown that helps strategists prioritize market entry or expansion efforts based on localized adoption maturity and infrastructure readiness.
Competitive Landscape and Key Players
The market structure is characterized by a high degree of concentration. Our analysis indicates that the top three companies hold approximately 65.5 percent of the market share, while the top five entities command around 78.2 percent. This consolidation implies that partnerships and vendor selection are critical decisions. Switching costs can be high, and compatibility with existing systems often dictates loyalty.
Several key players define the competitive boundaries. Stäubli, headquartered in Switzerland, offers the MPS series automatic robotic tool changers designed for payloads up to 80 kg. Their focus on ISO-standard flange compatibility and modular configurations makes them a strong contender for heavy-duty industrial applications. Meanwhile, Zimmer Group, based in Germany, provides a broader range of solutions including automatic, manual, pneumatic, and magnetic tool changers. Their emphasis on manufacturing flexibility appeals to facilities requiring diverse end-of-arm tooling options.
In the Americas, ATI Industrial Automation, located in North Carolina, specializes in robotic tool changers alongside multi-axis force/torque sensing. This integration of sensing capabilities adds value for applications requiring precise interaction with workpieces. Destaco, also based in the United States, develops cobot end-of-arm tools and manual tool changers with pass-through air and electric ports, catering specifically to the growing collaborative robot segment.
Worldwide Tool Changers Market
European innovation continues with SCHUNK, based in Lauffen am Neckar. They offer the CPS series pneumatically actuated automatic tool changers, which feature an integrated spring for self-retaining capabilities during air-loss scenarios. This safety feature is critical for machine tending automation. Recently, in May 2025, SCHUNK USA promoted this CPS line as a solution for manual changeovers, highlighting the ongoing push to bridge the gap between manual flexibility and automatic efficiency.
Other notable participants include SMC Corporation from Japan, known for pneumatic tool changers and grippers for collaborative robots. Robot System Products, based in Germany, provides the CoboShift tool changer family with automated exchange capabilities for collaborative robots. SmartShift Robotics, based in the United States, offers a universal tool changer system designed for fast deployment and redeployment. The presence of these specialized players indicates a mature market where differentiation often comes through niche capabilities, ease of integration, or specific regional support networks.
Market Dynamics and Regulatory Influence
External factors are exerting significant pressure on market dynamics. Regulatory standards are evolving to ensure safety as robot integration becomes more pervasive. The update to ISO 10218-2 in 2025 establishes new global safety requirements for industrial robot systems and integration. Compliance with these standards is essential for manufacturers deploying tool changers in multi-robot cells or shared workspaces. In the United States, ANSI/RIA R15.06-2012 Part 2 remains the key standard for integrating robot systems into completed machinery applications. Keeping abreast of these regulatory frameworks is vital for risk management and market access.
Supply chain considerations are also reshaping the landscape. Recent analysis from 2025 suggests that U.S. tariff policies are prompting localized supply chain adjustments among major manufacturers of robotic components. This shift may influence pricing strategies and lead times for hardware procurement. Companies are increasingly evaluating the origin of components and the resilience of their supply networks. This dynamic creates an opportunity for regional manufacturers to capture market share by offering reduced logistics friction and compliance with local content requirements.
Technological evolution continues to drive demand. The integration of sensor technology and smart connectivity into tool changers allows for predictive maintenance and real-time monitoring of tool status. As Industry 4.0 initiatives mature, the data generated by these components becomes part of the broader digital twin ecosystem. Organizations that invest in compatible hardware today are better positioned to leverage data analytics for optimization tomorrow.
Strategic Recommendations for 2026 Decision Makers
Based on the comprehensive data and analysis presented in our full report, we recommend several strategic actions for stakeholders planning their 2026 initiatives.
- Evaluate Total Cost of Ownership: When selecting between automatic and manual solutions, decision-makers should look beyond initial purchase price. Consider the downtime savings, labor reduction, and error minimization offered by automatic systems in high-volume contexts.
- Assess Vendor Concentration Risk: Given the high market concentration among top players, diversifying supplier relationships or ensuring robust support contracts with primary vendors is advisable to mitigate supply chain disruptions.
- Monitor Regulatory Compliance: Ensure that all tool changing hardware and integration plans align with the latest ISO and ANSI standards. Non-compliance can lead to operational delays and safety liabilities.
- Explore Adjacent Markets: While automotive and electronics are core drivers, the growth in medical and food and beverage sectors presents opportunities for specialized tool changer solutions that meet stringent hygiene and precision standards.
- Prepare for Supply Chain Shifts: Factor in potential changes related to localization trends and tariff impacts. Engaging with suppliers who have adapted their logistics networks can provide a competitive advantage in cost and reliability.
The robot tool changers market is poised for significant expansion. The interplay between automation demand, regulatory evolution, and competitive consolidation creates a complex environment. Organizations that leverage deep market intelligence will be better equipped to navigate these dynamics, secure reliable supply chains, and optimize their automation investments for the decade ahead.
For a detailed breakdown of regional forecasts, specific application growth rates, and comprehensive competitor profiling, we invite you to access the full report. The complete intelligence contained within our research provides the granularity required to finalize strategic plans and execute with confidence in the 2026-2032 period.
For detailed analysis of this topic, please visit the official page: Robot Tool Changers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com