

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Diesel Fuel Injection Systems Market Rises 5.5% CAGR to $109.4B by 2032

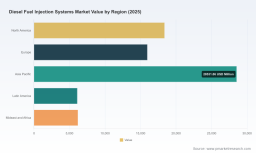
Navigating the Diesel Fuel Injection Systems Market: Strategic Intelligence for 2026 and Beyond
The global automotive and heavy machinery sectors are undergoing a period of profound transformation. As emission regulations tighten and performance expectations rise, the diesel fuel injection systems market remains a critical battleground for original equipment manufacturers (OEMs) and tier-one suppliers. At PW Consulting, we understand that access to precise, forward-looking data is not merely an academic exercise—it is a prerequisite for survival and growth in a volatile landscape. Our latest comprehensive market research report, covering the trajectory from 2026 through 2032, offers an unflinching look at the forces shaping this industry.
This document serves as an introduction to the depth of analysis contained within our full study. While we provide a high-level overview of the market's trajectory and the key players defining the competitive arena, the specific granular data required to build detailed financial models or supply chain strategies is reserved for our clients. The following insights highlight the strategic value of this research, demonstrating why industry leaders rely on PW Consulting to navigate the complexities of diesel fuel injection technologies.
Market Trajectory and Macroeconomic Context
Understanding the broader market currents is essential for strategic planning. Our analysis covers historical performance from 2020 through 2025, establishing a baseline against which future growth is measured, and extends a robust forecast through 2032. This longitudinal view allows stakeholders to distinguish between temporary fluctuations and structural shifts in demand.
The market has experienced a period of contraction in the immediate historical past, reflecting broader economic adjustments and shifts in mobility patterns. However, the forecast period indicates a decisive turnaround. Starting from a base valuation in 2025, the market is projected to regain momentum, driven by renewed investment in heavy-duty transportation and off-highway machinery. The compound annual growth rate (CAGR) anticipated for the forecast period stands at 5.5 percent, signaling a steady recovery and expansion phase.
By 2032, the total market valuation is expected to surpass previous historical highs, reaching new milestones in revenue terms denominated in USD millions. This growth trajectory is not linear; it is shaped by technological adoption rates, regulatory compliance costs, and regional industrial output. For decision-makers, recognizing the timing of this recovery is crucial. Investing too early in capacity without demand validation carries risk, while waiting too long may cede market share to competitors who have anticipated the upturn. Our report details the inflection points where these risks are minimized, providing a timeline for capital allocation and product development.
Technological Segmentation and Application Dynamics
The diesel fuel injection landscape is defined by distinct technological pathways, each serving specific engine requirements and emission standards. The market is primarily segmented by type, with Common Rail systems dominating the landscape due to their precision and efficiency advantages. This segment continues to leverage advancements in high-pressure operation, with systems now operating at pressures exceeding 2,500 bar to meet stringent emission norms. Alongside Common Rail, Unit Injectors and other specialized types maintain significant presence in specific heavy-duty and niche applications where durability and specific torque characteristics are prioritized.
Application-wise, the market is bifurcated between passenger cars, commercial vehicles, and off-highway vehicles. While passenger cars have historically been a major driver, the commercial vehicle sector remains a cornerstone of revenue stability, particularly as logistics networks demand higher efficiency. Off-highway vehicles, including mining and agricultural machinery, represent a critical growth vector, driven by the need for power density and fuel economy in harsh operating environments.
Our research delves deeply into the performance metrics of these segments without exposing the sensitive percentage splits that constitute our proprietary intelligence. We analyze the interplay between injector technology and engine management systems, highlighting how advancements in piezo injectors and solenoid valves are enabling faster actuation times and finer fuel metering. Furthermore, we examine the material science aspects, noting the reliance on high-performance steels and alloys capable of withstanding operating pressures up to 2,700 bar. This technical granularity is vital for suppliers evaluating their manufacturing capabilities against future product requirements.
Competitive Landscape and Key Player Strategies
The competitive environment in the diesel fuel injection systems market is characterized by a mix of established automotive giants and specialized component manufacturers. Market concentration remains moderate, indicating room for strategic maneuvering while acknowledging the dominance of key firms. Our report provides detailed profiles of the leading companies that are setting the pace for innovation and market capture.
Bosch, headquartered in Germany, continues to be a formidable force, manufacturing common-rail diesel fuel injection systems with piezo injectors operating up to 2,700 bar. Their comprehensive approach includes pumps and full fuel supply solutions for passenger cars, light commercial, and heavy-duty vehicles, ensuring a holistic value proposition for OEMs. Similarly, Denso Corporation from Japan supplies i-ART common rail fuel injection systems for medium- and large-sized vehicles. Their technology focuses on pressures up to 2,500 bar and the integration of SCR/DPF controls, demonstrating a commitment to low-emission performance through systemic integration.
In the United States, PHINIA produces DFI1 and DFI2 families of diesel fuel injectors for light- and medium-duty engines up to 250 kW. They also supply high-pressure diesel pumps and rails, supporting emissions standards through 3,000 bar operation. Their recent strategic moves indicate a focus on future-proofing their portfolio. BorgWarner, also based in the United States, provides diesel fuel injection systems including EUI and DFi7 injectors for heavy-duty trucks and passenger cars, plus PLD systems. Their positioning was significantly strengthened following the 2020 acquisition of Delphi Technologies, allowing them to broaden their technological reach.
Cummins Inc. offers Common Rail Fuel Systems and a Modular Common Rail Fuel System (MCRS) with ultra-fast actuated injectors and dual-stage pumps, delivering up to 2,600 bar for heavy-duty and mining engines. Their systems boast verified efficiency gains, a critical metric for commercial fleet operators. These companies represent the vanguard of the industry, and our report analyzes their recent developments to predict future market shifts.
Recent Developments and Strategic Implications
To navigate the market effectively, one must understand the immediate actions taken by these key players. Recent industry activity provides a window into where competitive advantages are being built. In April 2026, PHINIA announced plans to unveil 500bar+ fuel injection and alternative fuel innovations at Auto China 2026. This event underscores a strategic pivot towards supporting OEMs for future emissions standards while exploring diversification beyond traditional diesel platforms. Such announcements signal to the market that the boundaries of injection technology are expanding, and suppliers must adapt their roadmaps accordingly.
Meanwhile, Cummins Inc. demonstrated a focus on upgrading existing infrastructure. In June 2025, Cummins launched Modular Common Rail Fuel System (MCRS) upgrade kits for QSK60 and QSK78 engines. These kits convert legacy HPI systems with ultra-fast injectors and increased accumulator volume. This strategy highlights a significant market opportunity: the retrofitting and modernization of existing engine fleets to meet new efficiency and emission targets without requiring complete engine replacements.
These developments are not isolated incidents; they are indicative of broader industry trends. Our report contextualizes these moves within the larger framework of market evolution, helping clients understand whether to invest in new platform development or leverage upgrade paths to capture value from legacy assets.
Regulatory Pressures and Industry Dynamics
No analysis of the diesel fuel injection market is complete without addressing the regulatory environment. Compliance is no longer optional; it is the primary driver of technology adoption. Heavy-duty engines must meet EPA and Euro emission standards, which require optimized fuel injection timing and quantity alongside aftertreatment systems. The US EPA enforces nonconformance penalties for on-highway heavy-duty engines where fuel injection and EGR systems fail to achieve optimized emissions compliance. These regulatory facts create a hard ceiling for performance and a strict floor for compliance, dictating the minimum technical specifications for any market entry or product update.
Diesel Common Rail Injection System Market
Furthermore, the reliance on specific raw materials introduces supply chain volatility. Diesel fuel injection components such as injectors and rails use high-performance steels and alloys to withstand operating pressures up to 2,700 bar. Fluctuations in the availability or cost of these materials can impact manufacturing margins and lead times. Our research incorporates these dynamics into the forecast, offering scenarios that account for regulatory tightening and material cost variations. By understanding these constraints, companies can build more resilient supply chains and negotiate better terms with material suppliers.
The Strategic Value of Proprietary Intelligence
While the overview provided here outlines the general direction of the diesel fuel injection systems market, the true utility of our research lies in the details that cannot be publicly disclosed. Strategic decision-making requires precise revenue figures, specific regional growth rates, and detailed segmentation splits that reveal hidden opportunities. Publicly available data often lags behind real-time market shifts and lacks the granularity needed for operational planning.
Our full report offers actionable intelligence on the specific share of each region, the exact revenue contribution of each application segment, and the precise market concentration metrics that define competitive intensity. We analyze the interplay between regional industrial policies and local demand-supply gaps, providing a roadmap for market entry or expansion. We also quantify the impact of technological transitions on revenue streams, allowing R&D departments to prioritize projects with the highest return on investment.
For executives and strategy teams, the difference between a good decision and a great one often comes down to the quality of information. Access to our complete dataset eliminates guesswork. It allows you to validate assumptions about market size, verify the feasibility of capacity expansions, and benchmark your performance against the aggregated data of the industry's top players. The 5.5 percent CAGR and the projected market size by 2032 are headline figures, but the path to capturing that growth is nuanced and requires the depth of analysis only our full report provides.
Conclusion: Positioning for Future Growth
The diesel fuel injection systems market is at a pivotal juncture. The convergence of regulatory pressure, technological innovation, and recovering market demand creates a complex environment for stakeholders. Companies that can navigate the technical requirements of high-pressure systems, adapt to regulatory changes, and anticipate competitor moves will secure a dominant position.
PW Consulting's Diesel Fuel Injection Systems Market report is designed to be the cornerstone of that strategy. By synthesizing historical data, forward-looking forecasts, and deep competitive analysis, we provide the clarity needed to act with confidence. We invite industry leaders to leverage this intelligence to refine their strategies, optimize their portfolios, and capture the value available in the forecast period through 2032.
To access the complete dataset, including detailed segmentation values, regional breakdowns, and comprehensive company profiles with strategic recommendations, we encourage you to explore the full report. The competitive advantage lies in the details, and those details are available to partners ready to invest in superior market intelligence.
Diesel Fuel Injection Systems Market
For detailed analysis of this topic, please visit the official page: Diesel Fuel Injection Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com