

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Advanced CO2 Sensors Market Hits $690M in 2025, Projected to Reach $1.12B by 2032

Strategic Imperatives in the Advanced CO2 Sensors Market: Navigating Growth and Regulation Through 2032
The global transition toward smarter, healthier, and more energy-efficient environments has placed advanced carbon dioxide sensing technology at the center of industrial and commercial strategy. For executives, procurement leaders, and innovation managers, the question is no longer whether to invest in CO2 sensing infrastructure, but how to navigate a rapidly evolving landscape defined by tightening regulations, technological miniaturization, and shifting demand patterns. PW Consulting's latest Advanced CO2 Sensors Market research provides a comprehensive blueprint for understanding these forces, offering decision-makers the granular intelligence required to allocate capital, shape product roadmaps, and secure competitive positioning between 2026 and 2032.
Market Trajectory and Macroeconomic Context
The market for advanced CO2 sensors has demonstrated consistent expansion over the past half-decade, driven by the convergence of environmental awareness, building efficiency mandates, and industrial safety requirements. Historical data from 2020 through 2025 reveals a sector that has successfully navigated supply chain disruptions and component shortages to deliver robust revenue growth. The baseline year of 2025 anchors the market at approximately USD 690.0 million, a substantial increase from the USD 475.8 million recorded in 2020. This upward trajectory reflects not merely cyclical recovery but structural demand shifts that are reshaping procurement priorities across multiple verticals.
Looking forward, our forecast period spanning 2026 through 2032 projects sustained momentum for the industry. By 2026, market revenue is anticipated to cross USD 754.4 million, with growth compounding steadily toward the USD 1.1 billion threshold by 2032. The compound annual growth rate of 7.1 percent during this window underscores the durability of underlying demand drivers, even as macroeconomic headwinds and inflationary pressures continue to influence capital expenditure decisions globally. For enterprises evaluating market entry, capacity expansion, or portfolio diversification, this growth curve provides a critical baseline for scenario planning and investment justification.
Several structural factors underpin this expansion. The acceleration of demand-controlled ventilation (DCV) deployments in both new construction and retrofit projects has generated a reliable pipeline of sensor requirements. Simultaneously, the proliferation of Internet of Things (IoT) architectures and the push toward smart building certifications have elevated CO2 monitoring from a compliance checkbox to a foundational component of operational strategy. Industries ranging from healthcare to automotive and petrochemical processing are recalibrating their air quality standards, recognizing that real-time gas detection capabilities directly influence occupant health, regulatory compliance, and energy expenditure optimization.
Regulatory Tailwinds and Industry Dynamics
Regulatory frameworks are emerging as perhaps the most potent catalyst for market growth, transforming CO2 sensing from an optional enhancement into a compliance necessity in key jurisdictions. The ANSI/ASHRAE Standard 62.1-2022 Addendum d has established stringent requirements for demand-controlled ventilation systems, mandating precise CO2 measurement to achieve energy-efficient building codes. This standard has compelled building owners, HVAC integrators, and sensor manufacturers to align their product specifications with rigorous performance thresholds, creating a measurable uplift in demand for high-accuracy sensing solutions.
Beyond North American standards, the European Union's Energy Performance of Buildings Directive has set a trajectory toward zero-emission standards for new buildings by 2030. This directive not only imposes emission targets but also drives demand for advanced CO2 sensors integrated into DCV systems, as building operators seek to demonstrate compliance while minimizing energy consumption. The intersection of these regulatory mandates with certification frameworks such as RESET Grade B and the WELL Building Standard v2 has further broadened the addressable market, requiring sensor technologies that can satisfy overlapping compliance criteria without compromising deployment economics.
Advanced CO2 Sensors Market
These regulatory dynamics interact with technological advancement in ways that reshape competitive battles. Manufacturers are now evaluated not only on measurement accuracy but also on form factor, power consumption, integration compatibility, and certification readiness. The pressure to meet multiple standards simultaneously has accelerated innovation cycles and compressed development timelines, placing a premium on research and development agility. Companies that fail to align their sensor portfolios with evolving regulatory expectations risk marginalization, while those that proactively embed compliance into their product architecture are positioned to capture disproportionate market share.
Survey of the Competitive Landscape
The advanced CO2 sensors market is characterized by a concentrated competitive structure, with the top three players accounting for approximately 55 percent of market revenue and the top five controlling an estimated 68 percent. This concentration reflects the technical barriers to entry, the capital intensity of optical sensing research, and the long qualification cycles associated with building automation and industrial applications. Nevertheless, the market remains dynamic, with established players and emerging innovators competing on dimensions beyond raw market share, including technological differentiation, regional footprint, and ecosystem integration capabilities.
Senseair, headquartered in Sweden, has built its reputation on ultra-compact NDIR CO2 sensors designed for demand-controlled ventilation and indoor air quality monitoring. The S12 series exemplifies the company's focus on size reduction and surface-mount device integration, enabling OEMs to embed sensing capabilities in space-constrained smart building environments. In January 2026, Senseair launched a new iteration of the S12 sensor, achieving a 75 percent size reduction relative to predecessors while maintaining SMD solderability. The product is positioned as compliant with ASHRAE 62.1-2022 Addendum d, RESET Grade B, and WELL Building Standard v2 standards, and mass production is slated for 2026 following sample distribution.
Sensirion AG, based in Switzerland, has differentiated itself through high-accuracy photoacoustic NDIR CO2 sensors, most notably the SCD4x series and the recently announced SCD43. The SCD43, launched in February 2025 as a drop-in upgrade for the SCD4x platform, delivers best-in-class accuracy of ±(30 ppm + 3% m.v.) and targets compliance with ASHRAE 62.1 Draft Addendum d. By offering summer 2025 availability, Sensirion has signaled its intent to capture demand from building standards compliance and compact environmental monitoring applications. The photoacoustic approach allows for competitive performance in form factors that would be challenging for traditional NDIR implementations, broadening the application envelope for precision sensing.
Gas Sensing Solutions, operating from the United Kingdom, has focused on the CozIR series of solid-state NDIR CO2 sensors optimized for ultra-low power consumption. These devices are particularly relevant for IoT deployments and battery-powered applications where energy efficiency dictates operational viability. The integration of environmental sensing capabilities within a single package positions the CozIR series as a versatile solution for remote monitoring scenarios, where maintenance logistics and power constraints are paramount considerations.
Vaisala Oyj, a Finnish manufacturer, leverages advanced optical technology to produce NDIR CO2 sensors tailored for precision building management, industrial environments, and data-center applications. The emphasis on stability and reliability under demanding conditions has made Vaisala a preferred choice for mission-critical deployments where sensor drift or failure carries significant operational consequences. Amphenol Advanced Sensors, based in the United States, complements this landscape by supplying compact and low-power CO2 sensors for HVAC, IoT, and environmental monitoring applications, with a particular focus on miniaturization without sacrificing measurement accuracy.
Air Quality Sensor Market
The competitive field also includes integrators and diversified technology conglomerates. Siemens AG, headquartered in Germany, embeds NDIR CO2 sensor modules directly into building management systems, offering portfolios that address HVAC and air quality control requirements within broader automation architectures. Honeywell International Inc., also US-based, provides both chemical and infrared CO2 sensors targeted at safety, indoor air quality, and industrial applications, with low-power draw options that align with energy-conscious deployment strategies. These diversified players illustrate how CO2 sensing is increasingly being absorbed into larger ecosystem plays, where value is created through system-level integration rather than sensor component sales alone.
Segmentation Insights and Structural Demand Drivers
The market structure reveals distinct demand clusters that inform go-to-market strategies for manufacturers and procurement decisions for end users. In terms of technology type, NDIR CO2 sensors dominate the revenue landscape, reflecting the industry's preference for optical-based measurement techniques that offer long-term stability, minimal drift, and compatibility with continuous monitoring applications. Chemical CO2 sensors occupy a meaningful secondary position, serving applications where cost profile, power constraints, or specific environmental characteristics favor alternative sensing mechanisms. The coexistence of these technology pathways highlights the absence of a one-size-fits-all solution and the importance of matching sensor architecture to application requirements.
Application segmentation further illuminates where value is being created. Building automation represents the largest demand pool, aligning with the regulatory and certification dynamics discussed earlier. The integration of CO2 sensing into HVAC control loops, occupancy-based ventilation strategies, and indoor air quality dashboards has become a standard expectation rather than a premium feature. Healthcare applications constitute the second major pillar, driven by infection control protocols, operating room environmental management, and patient comfort standards that demand reliable gas monitoring. Industrial applications follow closely, encompassing process monitoring, safety systems, and environmental compliance in manufacturing and processing facilities.
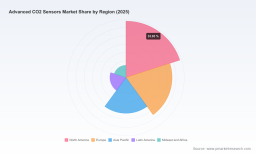
The automotive and petrochemical segments, while smaller in aggregate revenue terms, represent high-growth niches where sensor requirements are shaped by distinct constraints. Automotive applications demand robustness, fast response times, and integration with cabin air quality management systems, while petrochemical deployments prioritize accuracy under challenging atmospheric conditions and compliance with safety regulations. The geographic distribution of demand mirrors these application dynamics, with developed markets in North America and Europe maintaining the largest shares due to regulatory maturity and building stock renovation cycles, while Asia Pacific and other emerging regions are expanding as construction activity intensifies and standards adoption accelerates.
It is critical for stakeholders to recognize that these segmentation patterns are not static. As new building standards take effect, as IoT deployment models mature, and as manufacturing automation deepens, the relative weight of each application segment will shift. Our research provides the framework for anticipating these shifts, identifying leading indicators of demand migration, and recalibrating product and sales strategies before competitors react.
Report Scope and Actionable Intelligence
PW Consulting's Advanced CO2 Sensors Market research is designed to equip decision-makers with more than macro-level trends. The full report delivers a multi-dimensional analysis that bridges strategic vision with operational execution, structured around the following core components:
- Historical and Forecast Revenue Analysis: A detailed chronological breakdown spanning 2020 through 2032, enabling readers to validate growth assumptions, identify inflection points, and benchmark internal performance against market trajectories.
- Technology-Type Deep Dive: Comprehensive profiling of NDIR and chemical sensor categories, including performance characteristics, cost structures, integration considerations, and suitability profiles for specific application environments. This section equips R&D and product management teams with the technical context needed to prioritize development investments.
- Application-Specific Demand Mapping: Granular examination of building automation, healthcare, industrial, automotive, and petrochemical use cases, with attention to deployment drivers, specification requirements, purchase decision workflows, and pricing dynamics. Procurement leaders and sales strategists will find actionable guidance for segment-specific positioning.
- Regional Market Intelligence: Analysis of demand distribution and growth prospects across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The report examines regulatory adoption timelines, construction activity indicators, and competitive intensity in each region, enabling geographic resource allocation decisions.
- Corporate Profiles and Strategic Positioning: Detailed assessments of leading manufacturers, covering headquarters, product portfolios, technological differentiators, recent launches, and strategic implications. Profiles include Senseair, Sensirion AG, Gas Sensing Solutions, Vaisala Oyj, Amphenol Advanced Sensors, Siemens AG, and Honeywell International Inc., with attention to how each competitor is navigating the current landscape.
- Recent Developments Tracker: A chronologically organized record of product launches, regulatory updates, and strategic moves. Notable entries include Senseair's January 2026 S12 sensor launch and Sensirion's February 2025 SCD43 announcement, contextualized within the broader compliance and standards environment.
- Competitive Concentration and Market Structure Analysis: Evaluation of market concentration metrics, barriers to entry, consolidation risks, and partnership opportunities. This section supports M&A screening, competitive benchmarking, and strategic positioning exercises.
- Executive Summary and Strategic Recommendations: A synthesized overview tailored for C-suite audiences, translating analytical findings into prioritized action items for investment, innovation, partnership, and market entry decisions.
Each section is structured to facilitate rapid extraction of relevant insights while providing sufficient depth for thorough strategic analysis. Decision-makers are encouraged to consult the full report for the complete dataset, including segmentation splits, regional breakdowns, and detailed revenue figures that inform precise planning assumptions.
Strategic Recommendations for 2026 and Beyond
The intersection of regulatory momentum, technological innovation, and market growth creates a window of strategic opportunity that demands decisive action. For manufacturers and technology providers, the imperative is to accelerate development cycles while ensuring that sensor architectures are validated against the most demanding current standards, including ASHRAE 62.1-2022 Addendum d and relevant certification frameworks. Product roadmaps that prioritize miniaturization, low power consumption, and integration readiness will resonate with the IoT-driven deployment models that are expanding addressable use cases. Investment in photoacoustic and advanced NDIR technologies should be viewed not as optional enhancement but as foundational capability required to defend market position.
For end-user organizations and integrators, the priority lies in aligning procurement strategies with the trajectory of regulatory tightening and building certification requirements. Specifications should be updated to reflect the accuracy thresholds and compliance attributes demanded by emerging standards, and vendor evaluation criteria should incorporate long-term drift performance, certification documentation, and ecosystem compatibility alongside initial cost considerations. Procurement processes that favor lowest upfront price may inadvertently increase lifecycle costs through calibration frequency, premature replacement, or non-compliance penalties.
For investors and market entrants, the concentration structure of the industry signals both barriers and opportunities. Incumbents benefit from established qualification relationships and technical reputation, but the pace of innovation and the breadth of new application domains create openings for differentiated offerings. Targeting underpenetrated verticals, developing region-specific compliance packages, or pursuing strategic partnerships with building automation platforms can provide pathways to growth even in a concentrated market environment.
Conclusion: Securing Competitive Advantage Through Intelligence
The Advanced CO2 Sensors Market is entering a phase where regulatory discipline, technological capability, and demand expansion converge to reward organizations that invest in structured, data-backed strategic decision-making. The historical growth record, the projected 7.1 percent CAGR through 2032, and the active regulatory landscape collectively affirm that CO2 sensing is a strategic technology rather than a discretionary purchase. Yet the complexity of segmentation, the intensity of competition, and the velocity of standard evolution demand more than high-level awareness. They require detailed intelligence that informs specific investments, product specifications, geographic prioritization, and partnership choices.
PW Consulting's full market research report delivers the depth required to navigate this environment with confidence. By accessing the complete analysis, stakeholders will gain the segmentation data, regional breakdowns, revenue trajectories, and competitive profiles necessary to transform market awareness into actionable strategy. We invite executives, product leaders, and investment professionals to engage with the full report, exploring the comprehensive dataset and analytical frameworks that underpin the insights presented here. The path from regulatory pressure to commercial advantage runs through informed decision-making, and the intelligence contained in this research is structured to empower that journey.
For detailed analysis of this topic, please visit the official page: Advanced CO2 Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com