

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: IPM Market Hits $3.8B in 2025, Projects 7.1% CAGR to $6.15B by 2032

Navigating the Intelligent Power Module Landscape: Strategic Intelligence for the 2026 Market Cycle
The global market for Intelligent Power Modules (IPM) is entering a defining phase of expansion and technological renewal. As enterprises navigate shifting semiconductor supply chains, evolving application architectures, and intensifying regional competition, accessing precise, forward-looking intelligence is no longer a luxury—it is a strategic imperative. Our latest market research on the Intelligent Power Modules sector delivers exactly that: a rigorously modeled, commercially actionable view of where revenue is flowing, which architectures are gaining traction, and how the competitive field is reorganizing around the next generation of power integration. Drawing on historical tracking from 2020 through 2025 and a forecast horizon extending to 2032, this study translates volumetric growth into decision-grade frameworks designed specifically for corporate strategy, product planning, procurement, and investment teams operating in 2026.
Market Trajectory and the Macro Signals Shaping 2026 Decision-Making
The IPM sector has demonstrated consistent structural growth over the past half-decade, with global revenue tracking from approximately 2.7 billion USD in 2020 to an estimated 3.8 billion USD in 2025. That trajectory reflects more than cyclical recovery; it captures the deepening integration of intelligent power control into electrified transportation, industrial automation, renewable energy inverters, and compact consumer systems. The forecast period projects continued expansion, with market value expected to reach 4.02 billion USD in 2026 and advance toward 6.15 billion USD by 2032, corresponding to a compound annual growth rate of 7.1 percent across the forecast window.
Intelligent Power Modules (IPM) Market
These headline figures function as a strategic baseline rather than a final destination. For executive teams evaluating capacity commitments, product roadmaps, or supply-chain design, the real value lies in understanding the inflection mechanics that drive the curve: the pace at which alternative semiconductor architectures displace legacy configurations, the timing of adoption thresholds across end-use sectors, and the way regional deployment patterns reshape component sourcing strategies. Our analysis isolates these drivers so that leaders can anticipate demand shifts rather than react to them, aligning investment horizons with the growth vectors that will define the late 2020s.
Competitive Architecture and the Reconfiguration of Market Leadership
IPM market leadership is no longer determined solely by scale. It is increasingly defined by the ability to combine power semiconductor performance, driver integration, protection logic, and packaging efficiency into application-specific solutions. The competitive field is concentrated among a cohort of specialized and diversified semiconductor manufacturers, each pursuing distinct technology pathways and vertical strategies. STMicroelectronics continues to anchor its IPM portfolio in integrated power modules with IGBT and MOSFET drivers alongside built-in protection, targeting industrial and automotive motor control where reliability and functional integration carry premium value. Infineon Technologies AG has expanded its CIPOS portfolio into high-integration modules designed for motor drives, electric vehicle traction architectures, and renewable energy systems, emphasizing system-level efficiency and broad platform coverage.
Japanese manufacturers command a substantial share of innovation activity tied to packaging, material advances, and application-specific form factors. Mitsubishi Electric Corporation has pushed toward compact DIPIPM series and silicon-carbide-based IPMs for packaged air conditioners, heat pumps, and industrial inverters, a direction reinforced by recent sample shipments of a compact series leveraging RC-IGBTs and achieving a markedly smaller footprint for climate-control applications. Renesas Electronics Corporation maintains a focused position in embedded-control IPMs with integrated drivers for industrial and automotive use, aligning power integration with microcontroller architectures. Fuji Electric’s seventh-generation X Series IGBT IPMs target high-efficiency production equipment and energy-saving inverters, while ROHM Semiconductor is advancing gallium-nitride and silicon-carbide IPMs for high-efficiency compact inverters and motor drives. Toshiba Electronic Devices and Storage Corporation contributes to the landscape through SiC and IGBT IPMs designed for high-voltage industrial and automotive drives.
Europe remains a strategically important center for high-reliability and system-oriented IPM innovation. Semikron Danfoss GmbH and Co. KG provides high-reliability power modules for industrial automation, EV applications, and renewable energy drives, while NXP Semiconductors serves industrial and consumer motor control with power-management-oriented IPM solutions. In North America, Texas Instruments has emphasized isolated power modules and integrated solutions for data centers, electric vehicles, and industrial systems. ON Semiconductor Corporation has moved aggressively into wide-bandgap integration, introducing EliteSiC SPM series and GaN IPMs for HVAC systems, data-center drives, and e-mobility platforms, including a recently introduced 1200 V SiC MOSFET-based series intended to reduce system cost for HVAC and data-center drives. Wolfspeed continues to concentrate on SiC-based IPMs for e-mobility propulsion and high-efficiency inverters. Alpha and Omega Semiconductor Limited has pursued a highly practical, value-driven product cadence, launching the Mega IPM-7 series for brushless DC motor drives and commencing high-volume production of its IPM5 series, which integrates a substantial die count, at an outsourced packaging facility. Additional specialists such as Sensitron Semiconductor extend the competitive map into radiation-tolerant and high-reliability applications for space and industrial environments.
Together, these players illustrate a market in which differentiation is emerging from three intersecting axes: material technology transitions across IGBT, MOSFET, and wide-bandgap platforms; mechanical and electrical integration for size and efficiency targets; and vertical alignment with end-market reliability, thermal, and cost requirements. The intelligence embedded in our report unpacks these competitive vectors in detail, mapping how each design philosophy maps to revenue opportunity and risk exposure.
Technology Transitions, Supply Dynamics, and the Real Cost of Forecasting Errors
No IPM strategy for 2026 can be built on product roadmaps alone. Material availability, substrate constraints, and geopolitical frictions are actively reshaping lead times and platform timing. Throughout 2025, silicon-carbide wafer supply constraints drove lead times for 1200 V dies toward 26 weeks, causing some OEMs to postpone platform launches by as much as six months. At the same time, shortages of advanced substrates used in IPM manufacturing extended component lead times beyond 16 weeks, introducing design delays for EV and grid-related OEMs. Volatility in silicon wafers and aluminum-nitride substrates has similarly pushed module lead times past the 16-week threshold, compounding scheduling risk across multiple application segments.
These supply-side pressures intersect with an increasingly complex regulatory environment. Export controls on gallium and related critical minerals introduced in mid-2025 have created new exposure for GaN and SiC substrates used in IPM production, while broader trade restrictions and geopolitical tensions have added uncertainty to logistics and customs clearance within IPM supply chains. The practical implication for corporate planners is clear: model assumptions that ignore material bottlenecks and regional trade friction will systematically underestimate time-to-market risk and overstate near-term flexibility.
Our research integrates these dynamics into a structured view of market behavior, enabling decision-makers to test portfolio resilience under realistic supply scenarios. Rather than treating lead-time volatility as a peripheral procurement concern, the analysis positions it as a primary variable in revenue timing, model selection, and supplier negotiation strategy.
Scope, Structure, and the Operational Breadth of the Report
The study is built to support cross-functional execution rather than to remain an abstract market narrative. It opens with a rigorous quantification of market size and growth across the historical and forecast periods, establishing a shared baseline for commercial planning. From there, the analysis decomposes demand across technology families, application domains, and geographic regions, while deliberately preserving the granularity that product managers, sourcing leaders, and strategy teams need to make specific commitments.
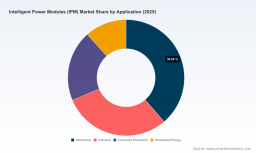
Readers will find detailed assessments of technology transition dynamics, including the economic and performance trade-offs that determine when IGBT, MOSFET, and silicon-carbide or gallium-nitride alternatives become strategically preferable in specific use cases. The report also examines application-side adoption patterns, tracking how motor control requirements, efficiency targets, thermal constraints, and packaging trends are accelerating or delaying IPM integration across transportation, industrial equipment, consumer electronics, and renewable energy systems. Regional deployment characteristics are analyzed to inform sourcing diversification, capacity planning, and market-entry sequencing without reducing the picture to simplistic regional rankings.
In parallel, the report delivers a company-level competitive assessment that goes beyond public positioning statements. It evaluates how each major participant’s product families map to application needs, where integration depth creates defensibility, and how recent product launches and shipment milestones alter near-term competitive pressure. Recent developments—such as compact DIPIPM sampling for climate-control applications, wide-bandgap IPM introductions targeting cost-sensitive HVAC and data-center drives, high-volume production ramp-ups for integrated IPM platforms, and new compact BLDC-oriented product lines—are contextualized within broader technology adoption cycles so that teams can distinguish transient news from structural momentum.
Additional sections address market concentration dynamics, pricing behavior, packaging and integration trends, and the procurement implications of substrate and wafer availability. The objective is to convert market intelligence into an operational reference that procurement can use for negotiation timing, engineering can use for architecture selection, and strategy teams can use for portfolio prioritization.
Where to Place Strategic Attention in 2026
For organizations operating in or adjacent to the IPM ecosystem, 2026 is a year in which tactical assumptions can quickly become outdated. The convergence of technology transitions, supply fragility, and regional regulatory variability means that advantage will accrue to teams who can distinguish durable demand from short-term noise. Several actionable priorities emerge from the broader landscape:
-
Prioritize technology roadmapping that aligns power semiconductor selection with application-specific efficiency, thermal, and cost targets rather than defaulting to legacy architectures simply because they are established.
-
Stress-test sourcing plans against substrate and wafer lead-time scenarios, especially for wide-bandgap devices where availability constraints can cascade into platform timing.
-
Treat competitive intelligence as a moving target: monitor product cadence, packaging innovation, and integration depth as leading indicators of where market share will migrate.
-
Incorporate regulatory and materials-export risk into regional planning, particularly where GaN and SiC supply chains intersect with critical-mineral controls and trade friction.
The study is designed to support exactly this kind of integrated decision-making. It gives leadership a defensible view of market size, growth velocity, competitive positioning, and risk exposure, while preserving the segment-level clarity necessary for execution teams to act with confidence.
Why the Complete Report Matters for Enterprise Decision-Makers
Market summaries can indicate direction, but they rarely provide the precision required to commit capital, redesign architectures, or renegotiate supply agreements. The full report supplies the missing layer: segment-level quantification, technology-specific adoption trajectories, regional deployment patterns, company positioning with product-level context, and scenario-aware guidance derived from current supply-chain stress points. It is structured so that strategy, R&D, procurement, and investor teams can extract the same underlying intelligence through different lenses without compromising analytical consistency.
Intelligent Power Module Board Market
Most importantly, the report is built to remain relevant beyond a single planning cycle. By combining historical validation, a clearly defined forecast window, and a disciplined focus on the operational drivers of growth, it offers an enduring reference for tracking how the IPM market evolves as electrification, automation, and efficiency mandates continue to spread across industrial and consumer systems.
For executives and analysts who require complete segment-level intelligence—rather than directional headlines—the full report delivers the detail, structure, and strategic framing needed to make informed decisions throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Intelligent Power Modules (IPM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com