

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Data Center Construction Market to Hit $442.64B by 2032, Growing at 6.4% CAGR

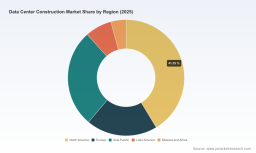
Navigating the Data Center Construction Surge: A Strategic Imperative for 2026
The global infrastructure landscape is undergoing a structural transformation that cannot be ignored. Driven by exponential data growth and the rapid deployment of artificial intelligence workloads, the construction of data centers has evolved from a specialized niche into a macroeconomic force. For enterprise leaders, investors, and real estate strategists, the question is no longer whether to engage with this sector, but how to navigate its accelerating complexity with precision. PW Consulting presents our latest comprehensive analysis, the Data Center Construction Market study, designed to equip decision-makers with the actionable intelligence required to thrive in 2026 and the subsequent forecasting window through 2032.
The Scale of Transformation: From Recovery to Accelerating Growth
The market trajectory over the past half-decade tells a story of resilience followed by rapid acceleration. Following a measured expansion through the early twenty-twenties, the sector experienced a notable inflection point that pushed overall market size toward 288.34 Billion in the base year of 2025. This surge reflects a broader realignment of capital toward digital infrastructure, as organizations recognize that compute capacity is now a primary driver of competitive advantage and operational continuity.
Looking ahead, our forecasts indicate sustained momentum. The market is projected to reach 307.46 Billion in 2026, with a clear upward trajectory continuing through the end of the decade and into the early twenty-thirties. By 2032, total market valuation is expected to approach 442.64 Billion. This expansion path is underpinned by a compound annual growth rate of 6.4 percent across the forecast period from 2026 to 2032. Such figures are not merely statistical markers; they represent the compounding effect of hyperscale campus expansions, enterprise digitalization mandates, and colocation demand reshaping commercial real estate priorities. Understanding how this growth distributes across project types, geographic footprints, and deployment models is essential for allocating capital efficiently, and this is precisely where deep-dive segmentation analysis becomes indispensable.
Beyond Headline Figures: The Operational Complexity of Modern Build-Outs
Constructing a modern data center is fundamentally different from traditional commercial development. The integration of high-density power distribution, advanced thermal management systems, and redundant mechanical infrastructure demands a level of engineering coordination that leaves little room for conventional procurement delays. Project timelines are increasingly compressed by competitive pressure and utility interconnection queues, while simultaneously being stretched by supply chain volatility and evolving regulatory expectations.
Our research dissects these operational realities by examining the interplay across electrical infrastructure, mechanical infrastructure, and general construction disciplines. Each segment carries its own procurement constraints, labor skill requirements, and technology adoption curves. The report evaluates how these components converge in practice, highlighting where bottlenecks form, where value engineering can yield meaningful savings, and where accelerated permitting strategies can protect critical path schedules. Rather than treating these elements as isolated line items, our analysis maps them against real-world project delivery models, offering practitioners a framework to anticipate friction before it impacts budget or timeline.
Data Center Consulting Services Market
Competitive Positioning and the Consolidation of Specialized Expertise
The competitive landscape in this sector is characterized by a concentrated group of established players who have invested heavily in mission-critical delivery capabilities. The market exhibits meaningful concentration, with leading firms commanding a dominant share of large-scale deployments. This structure rewards organizations that can demonstrate proven execution across multiple continents, maintain rigorous quality controls under aggressive timelines, and navigate the intersection of utility coordination, environmental compliance, and advanced construction methodologies.
Firms such as Fluor Corporation and AECOM have long anchored the market through full-scale engineering, design, and construction delivery spanning hyperscale campuses and enterprise facilities worldwide. Turner Construction Company brings deep experience in executing large-scale build-outs for hyperscale operators and colocation providers, while DPR Construction has carved a distinct position by specializing in mission-critical environments and preconstruction services tailored to AI-ready facilities. These capabilities reflect a broader industry shift: prime contractors are increasingly expected to function as integrated solution providers rather than traditional general contractors.
Other organizations are advancing complementary strengths. Holder Construction emphasizes efficiency-driven execution and advanced mechanical and electrical systems integration. HITT Contracting delivers general contracting and build services aligned with high-density AI infrastructure demands. Clayco differentiates itself through modular construction approaches and sustainable design methodologies, while Mortenson focuses on hyperscale campus delivery with embedded sustainability and power solutions. Brasfield & Gorrie supports enterprise and cloud providers with construction and commissioning expertise, and Equans extends its footprint through international construction and facility management capabilities. Together, these players illustrate a market where specialization, regional presence, and technical versatility determine competitive advantage.
Regulatory and Cost Dynamics Defining the 2026 Environment
Decision-makers entering 2026 must operate within a rapidly shifting policy and cost environment. Federal and state-level actions are reshaping how and where projects move forward, while material economics continue to pressure project budgets.
At the federal level, an executive order issued in mid-2025 accelerated the permitting pathway for data center infrastructure by streamlining environmental reviews and introducing financial incentives for qualifying projects. A subsequent agreement in early 2026 saw major developers commit to a Ratepayer Protection Pledge, agreeing to fully cover the costs of new electric generation resources supporting their facilities. These developments signal a growing expectation that large-scale infrastructure providers will internalize external costs, a principle that is also reflected in legislative activity across more than twenty-seven states requiring developers to shoulder the full cost of new energy infrastructure.
Meanwhile, cost pressures are intensifying on multiple fronts. A prominent industry cost index released in late 2025 documented elevated material and labor expenses driven by sustained AI-related demand. Upstream commodity dynamics have compounded this challenge, with producer price indices for industrial chemicals rising sharply in early 2026, directly affecting materials used in construction and systems integration. Compounding these supply-side headwinds, trade exposures on steel, aluminum, and copper have increased construction material cost sensitivity for data center projects by roughly ten to fifteen percent. Navigating these pressures requires procurement strategies that are forward-looking rather than reactive.
Data Center Construction Market
Regional Dynamics and the Energy Infrastructure Equation
Regional considerations now play an outsized role in project viability. Market participants must evaluate interconnection capacity, local regulatory frameworks, and utility pricing structures with greater rigor than ever before. In key power markets, transmission and capacity pricing have experienced dramatic adjustments, with some regional capacity markets seeing pricing shifts driven by hyperscale demand intensity. These changes directly influence total cost of ownership, site selection logic, and the timeline required to secure power commitments.
Concurrent regulatory evolution adds another layer of operational complexity. For instance, updated building energy efficiency standards in certain major states, effective from early 2026, impose stricter compliance requirements on cooling and electrical systems. Simultaneously, accelerated federal environmental review timelines for larger load facilities are creating new opportunities to compress permitting cycles for qualifying projects. These competing forces, faster approvals on one hand and stricter technical compliance on the other, demand a nuanced strategy that balances speed with compliance risk management. Our report examines how these regional and regulatory dynamics interact across key markets without reducing the analysis to simplistic geographic rankings, instead focusing on the structural factors that determine where and how projects can be delivered profitably.
How This Research Supports Executive Decision-Making
This study is structured to support real-world decisions rather than theoretical exploration. The report integrates historical performance data with forward-looking modeling to help organizations stress-test assumptions around budget allocation, procurement timing, and market entry strategies. It examines the relationship between infrastructure segment choices and project-level execution risk, providing a basis for more accurate forecasting and more resilient contracting strategies.
Readers will find detailed coverage of how different application models, hyperscale, colocation, and enterprise deployments, shape demand patterns, investment priorities, and delivery expectations. The analysis also explores how leading contractors structure their service offerings, where differentiation has become most valuable, and how market concentration influences bid dynamics and partnership opportunities. By aligning these insights with cost trends, regulatory milestones, and regional power market developments, the report provides a cohesive framework for evaluating risk and identifying actionable opportunities.
Strategic Takeaways for the Months Ahead
As organizations prepare their capital plans and long-term infrastructure roadmaps, several priorities come into focus. First, procurement and contracting strategies must account for sustained material cost volatility and the compounding effects of trade-related exposures. Second, engagement with energy infrastructure, from generation cost commitments to interconnection lead times, must be integrated into site selection and feasibility assessments rather than treated as a downstream utility issue. Third, firms should evaluate partnership and contracting options against a market where top-tier delivery capabilities remain concentrated, making selective collaboration and vendor qualification increasingly important. Fourth, regulatory compliance, spanning energy efficiency standards and evolving state-level cost responsibility mandates, must be embedded into project design and scheduling from the outset.
Accessing the Full Strategic Outlook
The data points highlighted here reflect only a portion of the intelligence embedded in the complete study. The full report provides granular segmentation analysis, detailed regional evaluations, and comprehensive assessments of competitive positioning that cannot be summarized in a single overview. For executives, development teams, and investment strategists seeking to align their decisions with the realities of a 442.64 Billion market trajectory by 2032, the complete research offers the depth required to move from awareness to execution. We invite you to explore the full dataset and analysis to secure the complete strategic picture for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Data Center Construction Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com