

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Oral Mucositis Drug Market Hits $159.4 Million in 2025, Poised for 7.38% CAGR Through 2032

Beyond Symptom Management: Strategic Intelligence for the Oral Mucositis Drugs Market (2026-2032)
The Shifting Landscape of Supportive Oncology Care
Oral mucositis remains one of the most debilitating and dose-limiting side effects of cancer therapy. As oncology increasingly adopts aggressive multi-modal regimens and expands into earlier disease stages, the demand for effective mucositis management has never been more critical. For pharmaceutical executives, investors, and healthcare strategists, the oral mucositis drugs market represents far more than a niche supportive care segment; it is a rapidly evolving commercial space shaped by regulatory shifts, unmet clinical needs, and a growing array of localized treatment modalities. Our latest comprehensive market intelligence study provides decision-makers with the analytical scaffolding required to navigate this space through 2032.
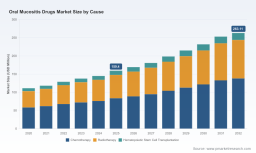
Drawing on historical performance from 2020 through 2025 and projecting forward across the 2026-2023 forecast horizon, the analysis reveals a market that has consistently compounded its value as clinicians and drug developers respond to persistent gaps in standard care. The total market revenue climbed from approximately USD 111.3 billion in 2020 to roughly USD 159.4 billion by 2025, reflecting sustained investment in both pharmaceutical and device-based interventions. Looking ahead, the market is forecasted to expand further, reaching more than USD 169 billion in 2026 and projected to cross USD 263 billion by 2032, underpinned by a steady annualized growth trajectory of 7.38%. These figures are not abstract milestones; they signal structural demand that will directly influence formulary positioning, R&D prioritization, and commercial partnerships in the years ahead.
Why These Projections Matter for 2026 Strategic Planning
The narrative behind the numbers is where executive strategy truly converges. Every percentage point of growth reflects clinical realities: the expanding use of myeloablative conditioning, the iterative refinement of targeted radiotherapy protocols, and the persistent search for better-tolerated alternatives to systemic analgesics. As payers tighten coverage around opioid-sparing protocols and regulatory agencies accelerate breakthrough and fast-track pathways, companies that understand the underlying revenue architecture of this market will be better positioned to time product launches, negotiate pricing, and secure reimbursement pathways.
Our research is designed to translate macro growth trajectories into actionable intelligence. By dissecting the commercial value tied to distinct clinical drivers and intervention categories, the report enables strategists to evaluate which therapeutic angles hold the most commercial momentum and where competitive intensity is likely to concentrate. Rather than offering static snapshots, the analysis maps how revenue streams are distributed across chemotherapy-induced, radiotherapy-induced, and hematopoietic stem cell transplantation-related contexts, as well as how they align with pain control pharmacotherapies, mucosal rinses and wash therapies, and emerging adjunctive approaches. This structure allows clients to stress-test product pipelines against real-world utilization patterns and forecast which segments will absorb incremental investment with the highest risk-adjusted returns.
Inside the Research: Executive Frameworks for Commercial Decision-Making
The report is engineered for cross-functional application. Clinical strategy teams, market access professionals, and corporate development units will find layered breakdowns that connect scientific rationale to commercial viability. Each section moves beyond descriptive commentary to deliver structured analytical outputs, including:
Oral Mucositis Drugs Market
- Demand attribution by clinical trigger , mapping how the revenue base segments across chemotherapy, radiation therapy, and stem cell transplantation pathways, with contextual insight into how regimen intensity and patient population dynamics drive utilization patterns.
- Therapeutic modality valuation , examining how revenue splits across conventional pain control pharmacologies, topical rinse and wash formulations, and alternative supportive interventions, helping stakeholders assess competitive positioning and white-space opportunities within the current treatment algorithm.
- Competitive footprint and concentration metrics , quantifying market share dispersion among leading players to reveal consolidation dynamics, barriers to entry, and the strategic implications of a partially concentrated landscape where a handful of firms command disproportionate influence over prescribing behaviors and distribution channels.
- Pipeline and regulatory intelligence , integrating recent clinical trial milestones, regulatory designations, and partnership developments that are reshaping the innovation curve and signaling which entrants may disrupt incumbent positioning over the forecast period.
- Supply chain and access constraints , capturing structural bottlenecks, raw material availability, and reimbursement realities that can alter commercialization timelines and affect the speed-to-market for both branded and generic entrants.
Together, these components form a decision-grade reference architecture rather than a single-point forecast. Clients can use the report to benchmark internal market assumptions, calibrate investment scenarios, and prepare for regulatory or reimbursement events that may compress or expand profitable windows of opportunity.
Competitive Architecture: Leaders, Entrants, and Strategic Wedges
The current commercial ecosystem is defined by a blend of established specialty brands, device-oriented innovators, and regional players pursuing differentiated mechanisms of action. At the center of the branded pharmaceutical space sits Amgen Inc., whose commercialization of Kepivance (palifermin) has long anchored the standard of care for severe oral mucositis in patients undergoing autologous hematopoietic stem cell transplantation. The FDA approval of palifermin in December 2004 established a rare example of a drug specifically indicated to reduce both the incidence and duration of severe mucosal injury, giving Amgen a durable regulatory anchor in a niche where therapeutic specificity commands premium positioning. The company's profile underscores a fundamental strategic question for the market: how long can a single-indication biologic preserve its leadership as alternative mechanisms and localized therapies continue to mature?
Parallel to pharmacologic approaches, device-based and mechanical-action solutions are carving out meaningful commercial territory. Jaguar Health, Inc., operating through its subsidiary Napo Pharmaceuticals, commercializes Gelclair, a mechanical-action gel that adheres to the mucosal surface to manage pain and provide temporary relief. The value proposition here is mechanistic: rather than relying solely on systemic or topical pharmacological activity, the product modulates the local environment to protect ulcerated tissue. ChemoMouthpiece, LLC extends this device-driven logic into preventive care with an FDA-cleared oral cryotherapy device designed to reduce the incidence and severity of chemotherapy-induced mucositis. In August 2025, the company published peer-reviewed results from a multi-center randomized controlled trial demonstrating a significant reduction in oral pain and decreased reliance on opioids and analgesics during chemotherapy. That clinical signal, combined with InfuSystem Holdings Inc.'s nationwide distribution and service infrastructure for the device, illustrates how complementary commercial ecosystems can accelerate adoption in cancer centers even when the underlying technology remains relatively straightforward.
Meanwhile, a newer cohort of innovators is targeting the pain-relief gap with localized, non-opioid formulations. OncoZenge AB has positioned BupiZenge, a bupivacaine-containing lozenge for local pain management, as its lead candidate. The strategic significance of this program was reinforced throughout 2025: the company secured approval to initiate the pivotal Phase III 'BEAM-Pain' trial in January, filed a PCT patent application for the lozenge formulation that same month, and signed a non-binding agreement with Molteni Farmaceutici in September to secure exclusive commercialization rights for BupiZenge in Europe. This three-part sequence—clinical advancement, intellectual property protection, and regional partnership architecture—is a textbook example of how development-stage companies are structuring go-to-market readiness in a space where regulatory differentiation and access to established distribution networks can be decisive.
Regional and value-oriented players are also reshaping commercial dynamics. Shilpa Medicare Limited has launched ORAAL, a naturally derived oral spray marketed for rapid pain relief and wound healing in oral mucositis patients. The emergence of naturally derived formulations reflects a broader trend toward patient-preferred delivery formats and adjunctive comfort solutions, even as payers and clinicians increasingly demand robust comparative evidence. Collectively, these companies span the full commercialization spectrum: from late-stage branded assets and cleared devices to early-phase pipeline candidates and regionally scaled specialty products, each pursuing a distinct route to share in the growing revenue base.
Market Dynamics as Strategic Inflection Points
The commercial opportunity cannot be fully interpreted without accounting for the structural dynamics that shape availability, reimbursement, and clinical adoption. Regulatory history provides one important anchor: the FDA's long-standing approval of Kepivance for bone marrow transplant-associated severe mucositis gave clinicians an early mechanistic option, yet the broader therapeutic landscape still reflects meaningful unmet need. Notably, there remains no FDA-approved systemic drug specifically indicated for severe oral mucositis associated with chemotherapy or radiation in head and neck cancer patients. That gap has incentivized a wave of investigational efforts, including the FDA's fast-track designation granted to RRx-001 for the prevention and attenuation of severe oral mucositis in head and neck cancer patients undergoing chemotherapy and radiation.
Supply-side realities add another layer of complexity. Regulatory and public health authorities have reported ongoing global shortages of Beriglobin, a blood product used in the treatment of radiation-induced oral mucositis. Shortages of supportive care inputs can create localized access volatility, influence off-label substitution patterns, and shift clinician preference toward alternative modalities that are less exposed to supply disruption. For commercial teams, these dynamics are not peripheral; they directly affect planning assumptions for launch sequencing, inventory strategy, and the timing of evidence generation.
The distribution of market influence also matters. A moderately concentrated competitive base indicates that while large specialty assets and established device programs exert significant pull on clinical practice, fragmentation in adjacent segments leaves room for targeted entrants with defensible mechanisms. High concentration at the top of the ranking often correlates with formulary entrenchment and reliance on clinical familiarity, whereas lower concentration among secondary participants suggests multiple opportunities to differentiate on pain management efficacy, ease of administration, or regional access advantages. The interaction between these concentration tiers will shape pricing power, partnership leverage, and the pace at which next-generation innovations can displace entrenched approaches.
Drugs for Herpes Labialis (Oral Herpes) Market
Using This Intelligence to De-Risk 2026 Decisions
Strategic planning for the oral mucositis market must balance optimism about growth with realism about clinical and regulatory complexity. The market's expansion from roughly USD 159.4 billion in 2025 toward a projected USD 263.1 billion by 2032 is strong enough to justify serious portfolio attention, but the distribution of that growth across causes, modalities, and geographies is what ultimately determines commercial success. Companies that treat the segment as a single homogeneous opportunity risk misallocating resources; those that can operationalize segment-level intelligence will be better equipped to choose where to compete, how to differentiate, and which partnerships will accelerate uptake.
This research report is built to support precisely that level of decision-making. It translates historical performance and forward forecasts into a structured reference for scenario modeling, competitive positioning, and commercialization roadmapping. By integrating pipeline developments, regulatory signals, access constraints, and concentration dynamics, the analysis equips executive teams with a common language for evaluating risk and opportunity across the full spectrum of oral mucositis interventions. The macro trajectory may be compelling, but the real value lies in understanding how that trajectory breaks down into actionable commercial logic.
For leaders preparing for critical 2026 decisions—whether related to pipeline prioritization, market entry timing, partnership structuring, or reimbursement strategy—the complete study provides the segmented segmentation detail, competitive scenarios, and analytical depth required to move from general market awareness to precise strategic execution. Access the full research for the granular breakdowns, regional momentum patterns, modality-level revenue shares, and competitor-specific positioning that will allow your team to convert broad market growth into a targeted competitive plan.
For detailed analysis of this topic, please visit the official page: Oral Mucositis Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com