

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Form in Place Gaskets Market to Reach US$3.25B by 2032 with 6.98% CAGR

Navigating the Form in Place Gaskets Market: Strategic Intelligence for 2026 Decision-Making
Market Trajectory and Macro Overview
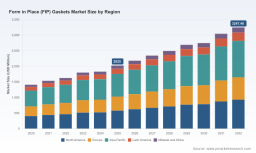
The Form in Place (FIP) Gaskets Market is entering a critical inflection point as it moves through the 2026-2032 forecast window. Analysis of historical performance from 2020 through 2025 reveals a consistent upward trajectory, with the global market expanding from approximately $1.41 billion to $2.025 billion over that five-year span. This growth reflects a compound annual growth rate that underscores sustained demand across industrial, electronics, and specialized engineering sectors.
Projecting forward, the market is expected to reach $2.18 billion in 2026 and climb steadily to $3.25 billion by 2032, maintaining a CAGR of 6.98% throughout the forecast period. This expansion is not merely a function of volume increase but signals deeper structural shifts in how manufacturers approach sealing, environmental protection, and electromagnetic interference (EMI) shielding. The market's evolution is being shaped by concurrent forces: supply chain restructuring, raw material cost volatility, accelerating adoption of automated dispensing technologies, and tightening performance requirements in semiconductor and automotive applications.
Strategic planners and procurement leaders must recognize that this market no longer operates as a commodity-driven segment. The convergence of material science innovation, precision manufacturing, and application-specific engineering has elevated FIP gaskets into a value-added solution space where performance differentiation, regulatory compliance, and supply reliability carry disproportionate weight. For organizations navigating 2026 investments, understanding these dynamics is not optional—it is foundational to capital allocation, vendor selection, and product roadmap planning.
Report Scope and Operational Intelligence
Our latest market research delivers a comprehensive, decision-ready analysis of the FIP gaskets market, structured to support cross-functional strategy teams. The report moves beyond headline figures to unpack the operational, competitive, and regulatory layers that define market behavior. Readers will find detailed breakdowns of market segmentation by type, application, and region, alongside deep dives into production methodologies, dispensing technologies, and cure-time optimization strategies that are reshaping manufacturing economics.
The study includes granular analysis of raw material cost structures, particularly silicone-based formulations and their derivatives, with tracking of price movements, supply constraints, and lead-time fluctuations that directly impact landed costs and production scheduling. We also examine the regulatory environment, including environmental compliance requirements, export control frameworks, and quality certification standards that influence sourcing decisions across different geographies.
Beyond market sizing, the report provides actionable intelligence on product innovation pipelines, including light-curable formulations, conductive elastomer advancements, and eco-friendly high-temperature material series. Each technology pathway is evaluated against adoption barriers, performance trade-offs, and integration requirements for assembly-line environments. This ensures that engineering, procurement, and product management teams can align their 2026 investment decisions with realistic assessments of technology readiness and supply availability.
Competitive Landscape and Strategic Positioning
The FIP gaskets market features a concentrated yet diverse competitive ecosystem. With a CR3 of 42% and CR5 of 51%, the market exhibits moderate concentration, indicating that while leading players hold meaningful share, there remains substantial room for specialized manufacturers, custom fabricators, and regional applicators to capture niche demand. This structure creates both opportunities and risks for organizations evaluating supply chain partnerships.
Parker Hannifin Corporation, headquartered in Cleveland, Ohio, continues to anchor its portfolio around conductive and non-conductive FIP gasket material series such as CHO-FORM and ParPHorm, targeting EMI shielding and environmental sealing applications. Their recent product launch in March 2025 introduced an eco-friendly high-temperature elastomer line tailored for offshore oil and gas environments, reflecting a strategic push into durability-focused, compliance-driven segments.
Laird Technologies, based in St. Louis, Missouri, emphasizes automated dispensing of conductive elastomer FIP gaskets for enclosure-level EMI shielding across electronics, automotive, and datacom applications. Their focus on process automation aligns with broader industry trends toward high-throughput, repeatable sealing solutions that reduce labor dependency and improve consistency in high-volume production.
Nolato Group, operating from Markaryd, Sweden, has built its reputation on the TriShield series of conductive silicone rubber FIP gaskets and associated dispensing technology for EMC shielding. Their approach integrates material formulation with application expertise, positioning them as a solutions provider rather than a commodity supplier.
Dymax Corporation, located in Torrington, Connecticut, differentiates through UV and LED light-curable FIP gasket formulations that cure in under 15 seconds, directly replacing slower traditional curing methods. This speed-to-cure advantage carries significant implications for cycle time reduction, throughput optimization, and floor-space efficiency in manufacturing environments.
Henkel AG & Co. KGaA, headquartered in Düsseldorf, Germany, focuses on 1K RTV silicone and related FIP gasket solutions designed for assembly-line dispensing and in-line curing. Their scale and formulation breadth support integration into automated production lines where consistency, shelf-life management, and curing predictability are critical.
Beyond these larger players, the market includes a network of specialized and custom-focused manufacturers. Sealing Devices Inc., based in Lancaster, New York, emphasizes custom fabrication for high-precision sealing applications and complex geometries. H&S Manufacturing Co. provides custom form-in-place liquid dispensing of high-performance silicone-based polymers for EMI shielding and complex gasket designs. Central Coating Technologies operates as a Nolato-approved applicator, delivering conductive and non-conductive FIP gaskets across a wide material range. KraFAB specializes in custom FIP gaskets using liquid dispensing for metal, glass, and substrate sealing, while Vactec Inc. combines precision dispensing technology with ISO 9001 and ITAR-compliant custom solutions. This ecosystem of specialized firms creates a tiered supply structure where organizations can match vendor capabilities to project complexity, compliance requirements, and volume profiles.
Form in Place (FIP) Gaskets Market
Market Dynamics: Supply Chain, Pricing, and Regulatory Pressures
The 2026 operating environment is being shaped by material cost movements and supply constraints that demand proactive procurement planning. Silicone pricing has shown regional divergence, with North American prices reaching approximately $6.18 per kilogram in May 2026, up 1.8% from the prior month, while European prices climbed to $7.98 per kilogram, reflecting a 1% monthly increase. These movements, while modest in isolation, compound when viewed alongside broader input-cost pressures and logistics variability.
More structurally significant is the 28% year-over-year increase in dimethyldichlorosilane prices during Q1 2026, driven by outages at Chinese chlor-alkali units. This upstream disruption has extended lead times for dimethyldichlorosilane and fumed silica from four weeks to twelve weeks in late 2025, creating scheduling uncertainty for manufacturers dependent on these inputs. Organizations that have not diversified sourcing, adjusted safety-stock parameters, or renegotiated delivery terms face heightened exposure to production delays and cost overruns.
Compounding these supply-side pressures, Wacker Chemie AG announced a mid-single-digit price increase for silicone-based products effective April 1, 2026, citing supply disruptions in the Middle East and higher energy tariffs in Europe. This development signals that raw material pricing is not only reacting to spot-market fluctuations but is also being reshaped by geopolitical supply routing and regional energy cost differentials. Procurement strategies that assume stable input pricing or rely on single-source supply chains will face increasing strain.
Regulatory and compliance considerations further complicate sourcing and product selection. Export control frameworks, quality management certifications, and environmental mandates influence which vendors can serve specific end markets and under what terms. For sectors such as defense, aerospace, and semiconductor manufacturing, compliance requirements are not peripheral—they are gatekeeping conditions that restrict vendor pools and elevate the importance of documented quality systems, traceability, and audit readiness.
Gasket and Seal Market
Strategic Implications for 2026 Decision-Making
The convergence of market growth, competitive differentiation, and supply-side volatility creates a clear imperative for structured market intelligence. Organizations operating in or dependent on FIP gaskets must evaluate their strategies across several interconnected dimensions.
- Supplier diversification and risk mitigation: With CR3/CR5 concentration and ongoing raw material constraints, over-reliance on a narrow vendor base increases vulnerability to price shocks, lead-time extensions, and capacity constraints. Strategic sourcing should map alternative suppliers, assess regional availability, and evaluate contractual flexibility.
- Technology and process alignment: Light-curable formulations, automated dispensing, and conductive elastomer innovations are not merely product upgrades—they are process enablers that affect cycle time, labor intensity, and quality consistency. Decision-makers should assess whether existing production lines can absorb these technologies and whether vendor support extends beyond material supply to process integration.
- Cost structure transparency: Regional silicone pricing divergence, upstream chemical price movements, and energy-related cost pressures require a more granular understanding of landed-cost drivers. Procurement teams should model sensitivity scenarios around key inputs and incorporate lead-time variability into inventory and scheduling plans.
- Compliance and qualification readiness: In regulated or export-controlled environments, vendor qualification is a strategic filter. Organizations should evaluate whether their supply base maintains the necessary certifications, documentation systems, and audit responsiveness to sustain uninterrupted sourcing.
- End-market demand signaling: Growth in semiconductor wafer manufacturing, IC packaging, automotive electronics, and specialized industrial applications is reshaping demand profiles. Understanding which applications are expanding, which are stabilizing, and which are facing substitution pressure helps prioritize internal resource allocation and vendor engagement.
These considerations are not isolated; they interact. A supplier selection decision that ignores lead-time risk may undermine production scheduling. A technology adoption choice that neglects compliance readiness may create bottlenecks in regulated markets. A procurement strategy that treats raw material pricing as static will misprice contracts and erode margin protection. The market's current dynamics reward organizations that integrate these dimensions into a coherent decision framework.
Why This Research Matters for 2026 Planning
Market intelligence in this space must be actionable, not descriptive. The report is structured to support strategic planning, procurement optimization, competitive benchmarking, and investment prioritization. It provides the context needed to interpret headline growth figures, the segmentation detail required to align with specific application or regional priorities, and the competitive analysis necessary to evaluate vendor capabilities against project requirements.
Readers will find analysis that connects market size evolution to underlying demand drivers, maps competitive positioning to technology and application focus areas, and translates raw material and regulatory developments into practical sourcing implications. The objective is to equip decision-makers with a clear view of where value is being created, where risk is accumulating, and where strategic options exist for 2026 and beyond.
For organizations that need to move from high-level awareness to detailed, segment-specific intelligence—including precise regional and application breakdowns, competitive financial and operational profiles, and scenario-based forecasting—the full report provides the depth required for execution-ready planning.
Next Steps for Decision-Makers
The FIP gaskets market is expanding in scale and complexity. Growth is real, but so are the pressures on supply reliability, input cost stability, and performance differentiation. Organizations that approach 2026 planning with a structured understanding of these forces will be better positioned to secure supply, optimize cost structures, and align technology adoption with operational realities.
To access the complete segmentation data, detailed competitive profiles, raw material tracking, and forecast scenarios that underpin this analysis, readers are encouraged to explore the full report. The complete research delivers the granularity and decision-grade detail necessary to translate market insight into concrete 2026 actions.
For detailed analysis of this topic, please visit the official page: Form in Place (FIP) Gaskets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com