

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Leather Goods Market Hits $363.2M in 2025, 7.2% CAGR to 2032

Strategic Outlook for the Global Leather Goods Market 2026-2032: Navigating Growth, Regulation, and Competitive Shifts
Introduction: The 2026 Inflection Point for Leather Goods Executives
The leather goods industry is entering a decisive phase of commercial expansion, operational restructuring, and regulatory recalibration. Executive teams across manufacturing, brand management, and distribution channels now face a landscape defined by resilient demand, evolving material preferences, and a tightening competitive perimeter. Our newly released Leather Goods Market research study offers a structured intelligence framework designed to support precise strategic planning, risk mitigation, and growth allocation for the 2026-2032 forecast horizon.
This report is not a static overview of historical performance. It is an operational reference tool for leadership teams that must decide where to commit capital, how to position product portfolios, and which partnership models will withstand shifting policy environments and material cost pressures. By integrating long-term market trajectory with granular analyses of segmentation dynamics, competitive positioning, and industry events, the study enables decision-makers to move beyond surface-level market narratives and into actionable strategic execution.
Macro Trajectory: A Market Built on Sustained Momentum
Over the 2020-2025 historical period, the global leather goods market demonstrated consistent expansion, with revenue reaching approximately 363.2 million USD in the base year. The growth path into 2026 and beyond reflects a market that is not merely recovering but compounding its structural advantages. Forecast modeling projects the market advancing toward 378.69 million USD in 2026, followed by a continued upward trajectory that carries revenue levels progressively higher across the remainder of the forecast window. By 2032, the market is positioned to reach an estimated 593.8 million USD.
Underlying this outlook is a compound annual growth rate of 7.2 percent across the forecast period, a figure that signals durable demand rather than temporary cyclical uplift. For executives, this kind of sustained CAGR has direct implications for capacity planning, inventory strategy, channel investment, and long-term brand positioning. It also reinforces the importance of forward-looking scenario modeling, particularly when regulatory and trade variables can alter the pace and geography of execution.
Importantly, the strategic relevance of this growth extends beyond the top-line trajectory. The market's expansion creates divergent opportunities across material types, product applications, and regional demand pockets, each with distinct margin profiles, sourcing requirements, and consumer resonance. Understanding where the highest-value opportunities concentrate, and how they interact with cost structures and compliance obligations, is central to capturing the market's upside without exposing the business to unnecessary operational risk.
Segmentation Architecture and Strategic Implications
One of the core strengths of this research is its disciplined segmentation design, which allows leadership teams to evaluate demand signals across the structural dimensions that shape procurement, product development, and market entry decisions. The analysis examines value distribution across material categories, application segments, and regional markets, providing a comparative lens for assessing where volume, premium positioning, and category expansion are evolving.
On the material side, the study evaluates the continuing relevance of genuine leather alongside the growing commercial footprint of synthetic and alternative material solutions. This comparison is critical for brands and manufacturers navigating consumer expectations around durability, aesthetics, sustainability, and price sensitivity. The report does not treat material choice as a static preference; instead, it frames material strategy as a dynamic component of portfolio architecture, influenced by sourcing availability, regulatory disclosure expectations, and shifting buyer perceptions.
Leather Market
Application-level analysis further sharpens strategic clarity by isolating demand patterns across major end-use categories. These include footwear, bags, and accessories, each of which presents distinct growth behavior, competitive intensity, and design-driven consumer demand. For product leaders, this breakdown supports more precise decisions about where to expand SKUs, how to prioritize design investment, and which categories may offer stronger resilience under changing macroeconomic conditions.
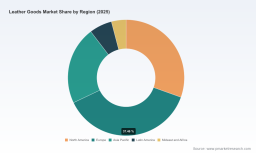
Geographically, the research maps regional market contributions to help executives assess where demand is most concentrated and where expansion may carry the greatest strategic payoff. Rather than describing the market as a uniform global entity, the study highlights how regional purchasing behavior, manufacturing ecosystems, and trade dynamics shape commercial opportunity. This regional perspective is especially valuable for companies evaluating sourcing reconfiguration, export exposure, and localized brand strategy in an environment where trade policy and logistics costs remain highly consequential.
Competitive Landscape: Differentiated Models in a Concentrated Market
The leather goods market is characterized by meaningful concentration among established players, alongside a broad field of specialized manufacturers and luxury-oriented houses competing on craftsmanship, vertical integration, and brand equity. The report examines this competitive architecture in depth, focusing on how leading firms differentiate themselves through product specialization, client relationships, material expertise, and geographic positioning.
A central theme in the competitive analysis is the coexistence of scale-oriented manufacturing and high-touch luxury production. Some companies compete by operating dedicated divisions that serve global fashion and lifestyle brands with handbags, wallets, and accessories, building long-term partnerships around consistency, volume capability, and design support. Others compete through OEM and ODM expertise, targeting premium handbags, backpacks, briefcases, belts, and related products with an emphasis on customization and technical execution.
At the premium end of the spectrum, the study evaluates firms whose commercial identity is anchored in craftsmanship, material provenance, and long durability commitments. These players often compete on vegetable-tanned materials, handmade construction, lifetime guarantees, and ultra-luxury travel or executive gear. Their strategic relevance lies not only in brand prestige, but in what they reveal about consumer willingness to pay for perceived authenticity, longevity, and material integrity.
The research also considers manufacturers that bridge B2B wholesale and private-label models, supplying fashion handbags and small leather goods to European and American brands. This segment underscores the importance of flexible production relationships and strong supply-chain credibility in markets where brand owners increasingly rely on specialized partners to manage design translation, production quality, and time-to-market.
Industry Events as Strategic Intelligence, Not Just Calendar Items
Trade fairs and product launches are often treated as industry noise, but in a market this dynamic, they function as leading indicators of sentiment, sourcing direction, and category innovation. The report integrates recent and upcoming events into its strategic context so that readers can interpret what major exhibitions and brand releases signal about the direction of demand and competition.
Recent activity shows continued emphasis on leather goods and fashion accessories at major international gatherings, with exhibitions bringing together suppliers, manufacturers, and buyers across material components, finished goods, and accessories. The upcoming 2026 event calendar reinforces this momentum, with multiple high-profile fairs scheduled across Europe, Asia, and the Middle East, each attracting hundreds of exhibitors and serving as focal points for sourcing relationships and product trends.
Equally telling are recent product launches from established retail and fashion names, including limited-edition leather jackets and handbags, as well as new timeless bag collections designed in one market and crafted in another using premium leather. These launches illustrate how brand strategy increasingly depends on material narrative, design authenticity, and cross-border craftsmanship. For competitive analysis, they also indicate where consumer-facing brands are placing their creative and commercial bets.
Regulatory and Cost Headwinds: The New Strategic Variables
Any realistic 2026 strategy must account for the fact that leather goods now operate within a more complex regulatory and cost environment than in previous growth cycles. The report devotes detailed attention to policy developments and input cost pressures that are reshaping sourcing decisions, product labeling practices, and market access.
One critical area is tariff exposure. Trade policy dynamics have added meaningful cost considerations for leather and allied product manufacturing, with average tariff impacts in key markets reaching levels that can influence export competitiveness and sourcing geography. For manufacturers and brand owners with cross-border supply chains, this is not simply a compliance issue; it is a strategic variable affecting product pricing, margin preservation, and the relative attractiveness of different production hubs.
Regulatory disclosure expectations are also tightening. Updated guidance in major consumer markets increasingly requires transparency around non-leather content in products that appear to be leather. This has direct implications for product claiming, packaging, and marketing language, especially for companies balancing genuine and alternative materials within the same portfolio. Failure to align product presentation with disclosure requirements can create both reputational and commercial risk.
In parallel, environmental policy developments are introducing new responsibilities for producers and brand operators. A proposed national extended producer responsibility framework in one of the major leather-producing economies signals a possible shift toward broader accountability for product lifecycles and end-of-life management. For industry participants, such developments point to a future where sustainability is not only a consumer-facing narrative but an operational and compliance consideration with potential cost and process implications.
Material cost pressure adds another layer of strategic urgency. Rising raw material costs have been identified as a headwind affecting profitability and planning, especially when combined with shifting consumer spending patterns. For executives, this reinforces the need to evaluate supplier diversification, product mix optimization, and price architecture with a greater degree of precision than in smoother cost environments.
Why This Research Is Built for Executive Decision-Making
The strategic value of this study lies in how it connects market structure to operational choice. It is designed to help leadership teams answer several questions that directly affect 2026 planning:
- Where is demand most likely to expand, and which product categories or material strategies align best with that expansion?
- How should companies interpret competitive concentration when deciding whether to compete on scale, craftsmanship, or specialization?
- Which sourcing and trade-policy risks are most material to margin and market access, and how should they be factored into sourcing strategy?
- What do recent trade fairs, brand launches, and industry developments reveal about near-term shifts in buyer expectations and supplier positioning?
- How should organizations prepare for regulatory disclosure and environmental accountability requirements without undermining product appeal or commercial agility?
To support these decisions, the report integrates market sizing and forecast data with segmentation analysis, competitive profiling, and contextual intelligence on events and regulatory developments. The result is a usable framework for portfolio strategy, market entry evaluation, supply-chain planning, and competitive positioning. It is built to reduce ambiguity in executive discussions and to give teams a shared basis for prioritizing investment and operational focus.
What the Full Report Unlocks
This article provides a strategic preview of the market environment and the decision context facing leather goods leaders in 2026. However, the complete research study goes further by offering the structured data, segmentation breakdowns, competitive profiles, and scenario-relevant analysis needed to turn strategic direction into execution. The full edition details market sizing across the historical and forecast timeline, segmentation dynamics across product type, application, and region, and a competitive assessment of the firms shaping today's supply and brand landscape. It also incorporates the latest trade fair signals, product-launch movements, and regulatory developments that are redefining operational risk and opportunity.
For decision-makers who need to translate market momentum into concrete strategy, the complete report delivers the depth required to act with confidence. It is designed to serve as a strategic reference for planning cycles, investment reviews, and competitive assessments throughout the 2026-2032 period.
Recommendation for Leadership Teams
If 2026 is treated as a tactical transition year, the leather goods market's growth trajectory and competitive intensity will likely outpace unprepared organizations. The companies that gain advantage will be those that use rigorous market intelligence to align product strategy, sourcing structure, compliance readiness, and brand positioning with the realities of a 7.2 percent growth environment and a more demanding regulatory landscape. This research study is built to support that decision-making process with professional depth, commercial relevance, and an executive-ready structure. For teams that require the full segmentation detail, competitive intelligence, and forward-looking context to guide their next strategic move, the complete market research report offers the comprehensive foundation needed to act decisively.
Leather Goods Market
For detailed analysis of this topic, please visit the official page: Leather Goods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com