

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Treadmill Market Hits $101M in 2025, Projects 6.8% CAGR Through 2032

Strategic Outlook: The Treadmill Machines Market in 2026 and Beyond
The fitness equipment industry is currently navigating a complex landscape defined by post-pandemic habit stabilization, technological integration, and shifting supply chain dynamics. For stakeholders looking to capitalize on the upcoming fiscal years, understanding the trajectory of the treadmill segment is not merely about tracking sales figures—it is about recognizing where capital efficiency meets consumer behavior. This introduction outlines the strategic value of our latest comprehensive market research on the Treadmill Machines Market, designed to equip decision-makers with the intelligence needed to thrive between 2026 and 2032.
Macro-Economic Trajectory and Growth Signals
Our analysis begins with a clear view of the historical context and future potential. The market has demonstrated resilience and steady expansion over the last half-decade. In 2020, the global revenue base stood at approximately 80.0 million USD, a figure that has since catalyzed growth through 2025, reaching an estimated 101.0 million USD. This historical progression sets the stage for the forecast period, where the market is projected to ascend to 105.39 million USD in 2026 and continue its upward march toward 159.0 million USD by 2032.
Driving this expansion is a Compound Annual Growth Rate (CAGR) of 6.8 percent. For strategic planners, this rate indicates a mature yet vigorous sector where organic growth is sustained by consistent demand rather than speculative bubbles. However, the aggregate numbers only tell part of the story. The real value for corporate strategy lies in understanding the velocity of this growth across different vectors and the external pressures that might accelerate or decelerate these figures. Our report dissects these macro trends to reveal where the opportunities for margin expansion and market share acquisition truly reside.
Segmentation Dynamics: Residential Dominance and Functional Shifts
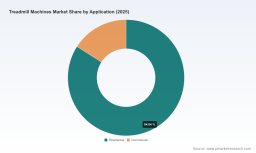
A critical component of our research involves the segmentation of the market by application and product type. The data indicates a pronounced preference for residential usage, which continues to command the lion's share of the market revenue. This dominance underscores the enduring shift toward home-based fitness solutions that began gaining momentum in previous years and has now settled into a stable equilibrium. For manufacturers and retailers, this suggests that product development strategies focused on home usability, noise reduction, and aesthetic integration remain high-priority investment areas.
Conversely, the commercial sector, while smaller in relative revenue contribution, represents a high-value niche with distinct operational requirements. The type segmentation further reveals a market heavily weighted toward single-function treadmills, though multifunctional units maintain a significant presence. The strategic implication here is nuanced. While single-function units drive volume, the multifunctional segment offers opportunities for premium pricing and deeper customer engagement through versatility. Our report delves into the specific drivers behind these splits without exposing the sensitive percentage breakdowns available in the full dataset, ensuring that clients who access the complete study gain a distinct informational advantage over competitors relying on surface-level industry summaries.
Regional Performance and Market Concentration
Geography plays a pivotal role in revenue distribution. North America remains a cornerstone of the industry, reflecting high disposable income levels and a deeply entrenched fitness culture. Europe and Asia Pacific also contribute substantial portions of the global revenue, each facing unique regulatory and economic environments that influence purchasing power and product specifications. The report provides a granular look at how these regional dynamics interact with supply chain logistics and local competition.
Market concentration is another vital metric for assessing risk and opportunity. The industry exhibits a moderate level of consolidation, with the top three players holding a significant portion of the market share and the top five commanding an even larger footprint. This concentration suggests that while there is room for agile newcomers, the incumbents possess substantial moats in terms of brand loyalty, distribution networks, and manufacturing scale. Understanding the exact concentration ratios and the specific revenue contributions of key regions is essential for entry strategy planning, details of which are preserved within the proprietary sections of our full study.
Competitive Landscape: Key Players and Strategic Moves
The competitive arena is populated by established entities with strong operational bases, primarily in the United States, alongside global innovators pushing the boundaries of connected fitness. Our report profiles several key companies that define the current standards of quality and innovation.
-
Life Fitness , based in Chicago, continues to set the benchmark for commercial and home equipment with its Club Series+ and Atmos models, catering to both high-traffic gyms and private residences.
-
TRUE Fitness , headquartered in St. Louis, stands as the largest privately-held U.S. producer. Their commercial-grade Launch and Stryker series are integral to many fitness facilities, emphasizing durability and performance.
-
SOLE Fitness , operating out of Salt Lake City, focuses on durability and value for home and light commercial users. Their F80, F85, and TT8 series are noted for lifetime warranties on key components, a strong differentiator in the residential segment.
-
Precor , from Bothell, specializes in the premium commercial tier. Their Breakaway slat-belt design is a hallmark feature for fitness facilities and health clubs seeking to reduce maintenance costs and enhance user experience.
-
NordicTrack , also based in Utah, dominates the high-performance home sector. Known for incline technology and interactive training, their X16 and Commercial 1750/2450 series appeal to users seeking gym-quality workouts at home.
-
Johnson Fitness & Wellness , located in Cottage Grove, serves as a retailer and provider leveraging its parent company Johnson Health Tech. Their Horizon Fitness subsidiary models cover both home and commercial applications, utilizing a broad distribution network.
Beyond the incumbents, the landscape is evolving through targeted product launches and strategic pivots. A notable recent development occurred in October 2025, when Peloton launched the Peloton Pro Series commercial equipment line, including the Tread+ Pro treadmill. This move targets hotels, residential gyms, and corporate wellness centers, signaling a convergence between high-end home tech and commercial durability. Such developments indicate that the boundaries between residential and commercial specifications are blurring, creating new cross-market opportunities that our report analyzes in depth.
Industry Dynamics: Regulatory, Supply Chain, and Spatial Constraints
External factors are increasingly dictating market behavior. In May 2025, the European Union approved new regulations on the energy efficiency of fitness equipment. The goal is to reduce energy consumption by 20 percent by 2030. This regulatory shift forces manufacturers to reconsider motor efficiency and standby power usage, potentially altering cost structures and product design priorities for any entity targeting the European market.
Supply chain volatility remains a persistent challenge. In June 2025, tariff increases on imported steel and aluminum spiked shipping costs for household appliances. This situation resulted in significant financial impacts, including a reported 250,000 USD overcharge fee paid by a U.S.-based fitness equipment maker for 1,000 treadmills and stationary bikes manufactured in China. Such incidents highlight the sensitivity of the market to raw material costs and trade policies, underscoring the need for diversified sourcing strategies or localized manufacturing considerations.
Furthermore, the physical reality of the product presents a barrier to entry for some consumers. High-quality treadmills require substantial dedicated floor space, a significant constraint for potential home users in smaller living spaces. This spatial requirement influences product design trends toward foldability and compact engineering, as well as marketing strategies that address urban housing limitations.
Technology and compliance are also intersecting. Connected fitness equipment manufacturers face increasing regulatory demands relating to cybersecurity and personal data protection for EU market access. This was demonstrated in February 2026 when Centr obtained the SGS RED Cybersecurity Certification. For market participants, compliance is no longer just a legal checkbox but a competitive differentiator that builds trust with privacy-conscious consumers and institutional buyers.
Operational Intelligence Within the Full Report
This overview serves as a primer to the comprehensive intelligence contained in our full market research publication. The complete document goes beyond these high-level trends to provide actionable frameworks for strategic planning. Readers who access the source material will find detailed breakdowns of market sizing across all forecast years, allowing for precise financial modeling and capacity planning.
The full study includes deep dives into the segmentation splits, offering clarity on how regional preferences and application needs diverge. It provides an exhaustive competitive profiling section that evaluates market positioning, product portfolios, and recent strategic maneuvers of key players. Additionally, the report contextualizes the industry dynamics within specific regional regulatory environments, helping compliance officers and product managers anticipate future constraints.
By securing access to the complete dataset, enterprises can benchmark their performance against market averages, identify white spaces for product innovation, and refine their go-to-market strategies in light of the 6.8 percent CAGR trajectory. The report is designed to function as a living document for strategy teams, supporting decisions ranging from capital expenditure on manufacturing lines to marketing spend allocation across digital and physical channels.
Treadmill Machines Market
Conclusion: Positioning for the 2026-2032 Cycle
The treadmill machines market is entering a phase where growth is predictable yet complex. The projected revenue climb to 159.0 million USD by 2032 offers a compelling value proposition for investors and operators, but realizing this potential requires navigating regulatory hurdles, supply chain instabilities, and shifting consumer spatial constraints. The insights provided in this introduction highlight the necessity of a data-backed approach to strategy.
Worldwide Low Speed Rehabilitation Treadmill Market
To leverage these insights fully and gain the competitive edge required for the 2026 fiscal year and beyond, stakeholders are encouraged to consult the complete market research report. The full version unlocks the specific regional percentages, detailed segmentation values, and granular competitive analysis necessary to transform broad market awareness into precise corporate action. In a market defined by concentration and consolidation, information remains the ultimate asset.
For detailed analysis of this topic, please visit the official page: Treadmill Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com