

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PEG Market Hits $5.78B in 2025, Projects 6% CAGR Through 2032

Strategic Navigation in the Polyethylene Glycol (PEG) Market: A 2026 Decision-Maker's Guide
The global chemical landscape is undergoing a period of recalibration, and few intermediates illustrate this complexity better than polyethylene glycol. As a versatile polymer used across pharmaceuticals, personal care, and industrial processing, PEG sits at the intersection of supply chain dynamics, regulatory scrutiny, and evolving end-use demand. For executives and strategic planners operating in 2026, understanding the trajectory of this market is not merely an academic exercise; it is a prerequisite for resilient supply chain design, product portfolio optimization, and competitive positioning. PW Consulting's latest market research on the Polyethylene Glycol (PEG) Market delivers the granular intelligence required to navigate these shifting currents. This article outlines the strategic horizon, contextualizes the macroeconomic environment, and demonstrates how the full report translates data into actionable foresight.
Macro Trajectory and the 2026 Inflection Point
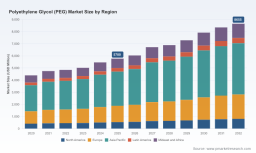
The PEG market has demonstrated consistent organic expansion, with revenue climbing from 4.4 thousand million USD in 2020 to approximately 5.78 thousand million USD by 2025. This historical progression establishes a clear baseline of demand resilience, but the true strategic signal lies in the forward-looking forecast. From 2026 through 2032, the market is projected to advance at a compound annual growth rate of 6.0 percent, reaching an estimated valuation of 8.66 thousand million USD by the close of the forecast window. This trajectory reflects more than incremental growth; it signals structural demand shifts that will reward operators who can align capacity, formulation capabilities, and regional logistics ahead of the curve.
For 2026 decision-makers, the immediate takeaway is that the market is entering a phase where volume growth competes with margin preservation. The historical record shows that between 2020 and 2025, the market compounded at a rate that outpaced many adjacent specialty chemical segments, driven by persistent pharmaceutical excipient requirements and expanding personal care formulations. Looking forward, the forecast period embeds assumptions about capacity additions, trade flow adjustments, and the gradual integration of emerging applications. Executives who rely on headline figures alone risk missing the underlying volatility of input costs, regional supply tightness, and the strategic implications of concentration among top-tier producers.
Concentration, Competitive Density, and the Barrier to Entry
Market structure matters as much as market size. The PEG sector is moderately concentrated, with the top three producers collectively accounting for approximately 45 percent of global revenue and the top five commanding roughly 58 percent. This concentration pattern creates a dual reality for market participants. On one hand, established incumbents benefit from scale advantages, formulation know-how, and regulatory compliance track records that raise the barrier to entry. On the other hand, the remaining market share leaves meaningful room for specialized players, regional entrants, and niche application providers to capture value through differentiated molecular weight offerings, GMP-compliant production, or application-specific service models.
Polypropylene Glycol Market
Strategic planners should recognize that concentration metrics are not static. They reflect historical investment decisions, technology licensing, and geographic footprint choices that continue to shape competitive dynamics. The full report dissects how these concentration patterns interact with regional capacity deployment, pricing power, and the strategic behavior of both integrated majors and focused specialty producers. Understanding where scale confers advantage and where agility creates opportunity is essential for assessing partnership opportunities, vertical integration scenarios, and potential displacement risks.
Competitive Landscape: Strategic Profiles of Key Players
The PEG market is contested by a diverse set of global and regional operators, each pursuing distinct value propositions across molecular weight ranges, application verticals, and compliance standards. The following profiles illustrate how leading companies are positioning themselves for the 2026 environment. The complete report extends this analysis with detailed strategic assessments, capacity footprints, and competitive response scenarios.
BASF SE
Headquartered in Ludwigshafen, Germany, BASF maintains a focused offering around its Kollisolv portfolio of ethoxylated polymer-solubilizers designed for oral and topical pharmaceutical formulations. Beyond solubilizers, the company provides reactive PEGs such as Pluriol alongside USP-compliant grades for excipient use. This combination allows BASF to serve formulators who require both functional performance and regulatory-grade consistency. In May 2025, the company expanded its European specialty PEG portfolio with the introduction of reactive polyethylene glycol Pluriol A 2400 I, reinforcing its emphasis on industrial formulators seeking tailored reactivity and solubility profiles. This move underscores a broader strategy of deepening application relevance rather than competing solely on commodity volume.
Dow Inc.
Based in Midland, United States, Dow competes through the CARBOWAX series of PEGs, spanning industrial and pharmaceutical grades. The product line is positioned around solvency, lubricity, and formulation support, making it relevant across personal care, pharma, and industrial applications. Dow's approach leverages a broad brand presence and an application-oriented narrative that connects performance characteristics to end-customer outcomes. For buyers evaluating suppliers, Dow's portfolio breadth offers a reference point for multi-application sourcing strategies, even as regional sourcing preferences and regulatory requirements continue to influence procurement decisions.
Clariant
Headquartered in Muttenz, Switzerland, Clariant offers Polyglykol excipient grades manufactured under IPEC GMP standards, serving pharmaceutical and personal care markets with an emphasis on compliance and quality assurance. A significant strategic development occurred in March 2026, when Clariant expanded its Clear Lake site in Texas to add GMP-compliant manufacturing of pharmaceutical-grade PEG excipients. This expansion created the first U.S. facility dedicated to pharma-grade PEG and extends the company's reach toward Latin American customers. For 2026 planners, this milestone illustrates the growing importance of geographic proximity to regulated end markets and the strategic value of localized GMP capacity in reducing lead times, mitigating supply risk, and supporting regional procurement mandates.
INEOS
London-based INEOS produces PEG 3350 PH and related grades via ethylene oxide polymerization, targeting industrial and personal care applications. The company's positioning reflects the broader relevance of polymer-grade PEG in formulations where cost-performance balance and supply reliability are central. INEOS's participation in the market highlights the enduring role of ethylene oxide-based production routes and the importance of upstream integration for operators seeking to manage feedstock exposure and throughput efficiency.
Lotte Chemical and Sanyo Chemical Industries
Lotte Chemical, based in Seoul, South Korea, supplies PEG products across industrial, personal care, and pharmaceutical applications, reflecting the diversified demand profile of the Asian market. Sanyo Chemical Industries, headquartered in Kyoto, Japan, offers PEG products for a range of industrial and specialty uses. Both companies exemplify how regional manufacturers can compete by aligning product portfolios with local formulation preferences, customer service expectations, and application-specific technical support. Their presence reinforces the reality that the PEG market is not only global in scale but also regionally nuanced in execution.
India Glycols
Noida-based India Glycols focuses on PEG for industrial and personal care markets, representing the growing significance of South Asian production in cost-sensitive application segments. As demand expands in personal care formulations and industrial processing, suppliers positioned in this region can capture share through competitive cost structures and proximity to emerging formulation clusters. The strategic implication for global buyers is the need to balance cost optimization with qualification timelines, regulatory documentation, and supply assurance.
Croda International
Croda International, headquartered in Watford, United Kingdom, provides PEG excipients and additives relevant to personal care and pharmaceutical applications. The company's emphasis on specialty additives and excipient-grade materials aligns with the market's ongoing shift toward formulation performance, regulatory compliance, and ingredient transparency. In an environment where downstream formulators increasingly demand documented quality and application support, Croda's positioning illustrates the value of combining material science with customer-facing technical expertise.
Chinese Producers: Jiangsu Haian Petrochemical Plant and Liaoning Oxiranchem
Jiangsu Haian Petrochemical Plant, located in Jiangsu, China, operates large-scale PEG production oriented toward industrial applications. Liaoning Oxiranchem, based in Liaoning, China, supplies PEG and derivatives for industrial and personal care uses. Together, these companies reflect the scale and cost discipline of Chinese manufacturing in segments where industrial throughput and derivative diversity are competitive differentiators. At the same time, regulatory visibility, sustainability expectations, and qualification requirements continue to shape how international buyers engage with Chinese-sourced PEG, making supply chain due diligence an integral part of procurement strategy in 2026.
Market Dynamics: Feedstock Volatility, Regulation, and Structural Shifts
Strategic planning for PEG in 2026 must account for forces that extend beyond demand forecasting. Feedstock conditions, regulatory evolution, and environmental considerations are reshaping the operating environment and influencing both cost structures and product roadmaps.
Feedstock and Input Cost Environment
Ethylene glycol prices in Asia moved in a mostly downward direction during the second half of 2025 due to strong supply pressure. This development matters for PEG economics because ethylene oxide-derived production remains the foundational route for much of global supply. Input cost movements of this nature can compress margins for producers who lack pricing flexibility, while simultaneously creating negotiation windows for downstream buyers with disciplined procurement strategies. The strategic challenge is not simply to react to price direction, but to build sourcing architectures that can accommodate volatility without compromising supply assurance or qualification status.
Regulatory Pressure and Environmental Considerations
Simultaneously, the European Chemicals Agency has tightened restrictions on polymers that demonstrate persistence in aquatic ecosystems, including PEG derivatives. This regulatory direction reflects broader scrutiny of petroleum-based ethylene oxide derivatives, which are not biodegradable and may contribute to pollution, prompting stricter requirements in some countries. Although PEG remains essential across multiple applications, the regulatory environment is pushing industry participants to evaluate formulation alternatives, lifecycle considerations, and compliance readiness more carefully than before.
For market participants, the implication is twofold. First, regulatory dynamics can influence demand patterns in sensitive application areas, particularly where downstream brands face consumer expectations and sustainability commitments. Second, they elevate the importance of documentation, traceability, and proactive engagement with evolving chemical policy. Companies that treat regulatory change as a static compliance task risk being caught off guard; those that integrate it into product strategy, supplier selection, and regional market planning will be better positioned to sustain access and reputation.
Application Pull and Cross-Segment Interdependencies
Beyond feedstock and regulation, the PEG market is shaped by the varying intensity of demand across medical, personal care, and industrial uses. The medical segment continues to anchor a significant portion of value, driven by the need for well-qualified excipients and formulation consistency. Personal care applications contribute strong volume and formulation innovation, while industrial uses remain essential for solvency, lubricity, and process performance. These segments do not evolve in isolation. A shift in pharmaceutical manufacturing geography, a change in personal care ingredient preferences, or an industrial capacity adjustment can create ripple effects across the entire value chain.
The full report analyzes how these application segments interact with molecular weight preferences and regional demand patterns, providing decision-makers with a framework for scenario planning. For example, formulators targeting pharmaceutical-grade performance must evaluate not only material specifications but also supplier compliance records, audit readiness, and geographic supply continuity. Similarly, industrial users focused on cost efficiency must weigh the trade-offs between large-scale sourcing and the risk of regional tightness or regulatory disruption.
Polyethylene Glycol (PEG) Market
What the Full Report Delivers for 2026 Decision-Making
PW Consulting's Polyethylene Glycol (PEG) Market research is designed to move beyond descriptive market sizing and into the operational and strategic territory where executives make trade-offs. The report combines macro-level trajectory with segment-level context, competitive analysis, and dynamic market forces, all structured to support practical decision-making in a complex environment.
Segment and Application Context Without Operational Blind Spots
The research examines the market through multiple segmentation lenses, including molecular weight ranges, application categories, and regional demand patterns. Rather than presenting these splits as isolated statistics, the report interprets them as indicators of formulation preferences, qualification requirements, and purchasing behavior. This approach helps planners understand where demand is concentrated, which molecular weight ranges carry disproportionate strategic importance, and how application categories influence supplier selection.
Because the market is not uniform, executives need to know not only where growth is occurring, but also which segments are exposed to input volatility, regulatory pressure, or regional capacity constraints. The report maps these sensitivities so that strategy teams can prioritize the most consequential variables instead of treating the market as a single homogeneous opportunity.
Competitive Positioning and Strategic Response Scenarios
A core strength of the research is its treatment of the competitive landscape as a strategic system rather than a list of players. By profiling leading companies and recent developments, the report clarifies how incumbents are expanding compliant capacity, introducing reactive or specialty grades, and aligning production footprints with regional demand and regulation. It also provides the analytical foundation for evaluating potential competitive responses to feedstock shifts, regulatory changes, and new capacity entry.
For strategy teams, this means the report supports use cases such as supplier qualification prioritization, partnership evaluation, capacity planning assumptions, and risk assessment around concentration and regional sourcing. Instead of forcing teams to reconstruct the competitive environment from fragmented sources, the research consolidates the relevant context into a decision-ready structure.
Dynamic Market Forces: Feedstock, Regulation, and Environmental Risk
The report integrates the operational realities that shape margin and access in the PEG market. It addresses the impact of feedstock pricing direction, especially the downward pressure observed in Asia during late 2025, and frames how this environment affects procurement timing, contract strategy, and cost planning. It also examines the trajectory of regulatory tightening around polymer persistence and petroleum-derived derivatives, translating these developments into practical considerations for product roadmap decisions, compliance readiness, and market access planning.
By placing these dynamics in the same analytical frame as demand and competition, the research helps leaders weigh trade-offs more effectively. A procurement decision that appears favorable on price may have hidden exposure to regulatory or supply continuity risk. A capacity investment that seems justified by demand growth may require a stronger compliance and sustainability narrative to withstand scrutiny in regulated end markets. The report provides the context needed to evaluate such choices with greater confidence.
Forecast Discipline for Long-Range Planning
The forecast period from 2026 through 2032 is not presented as a single deterministic path. Instead, the research uses the 6.0 percent compound annual growth rate and the related revenue trajectory as a baseline for stress-testing assumptions about capacity, regional expansion, and application adoption. This discipline is particularly important for capital-intensive decisions and multi-year sourcing commitments, where the difference between a base-case forecast and an overconfident extrapolation can be material.
Executives can use the forecast structure to align internal planning horizons, assess the timing of strategic initiatives, and identify the range of outcomes that would change a decision. In that sense, the research functions as both an intelligence resource and a planning scaffold, helping teams connect market signals to concrete actions.
Conclusion: Turning Market Intelligence into Strategic Advantage
The Polyethylene Glycol (PEG) Market in 2026 is defined by steady medium-term growth, a moderately concentrated competitive field, and an operating environment shaped by feedstock conditions, regulatory scrutiny, and application-specific demand dynamics. The headline trajectory suggests continued expansion, but the strategic value lies in understanding how that expansion is distributed, how competitors are positioning, and where risk and opportunity concentrate across segments and regions.
PW Consulting's full market research translates this complexity into a structured intelligence platform for executives who must make sourcing, partnership, capacity, and portfolio decisions under uncertainty. It connects historical performance to forward-looking scenarios, profiles the strategic behavior of key producers, and embeds the regulatory and feedstock forces that will influence margins and market access. For decision-makers seeking more than macro-level estimates, the report offers the depth required to act with precision.
To access the complete segmentation analysis, competitive assessments, regional demand context, and scenario-ready forecast detail, readers are invited to explore the full PW Consulting Polyethylene Glycol (PEG) Market research. The source report provides the operational granularity necessary to convert industry insight into confident, evidence-based strategy.
For detailed analysis of this topic, please visit the official page: Polyethylene Glycol (PEG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com