

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electronics Components Market to Hit $717.6B by 2032, Growing at 7.36% CAGR

Navigating the Next Phase: Strategic Intelligence for the Electronic Components Market 2026–2032
The global electronic components industry stands at a decisive inflection point. After five years of steady expansion, the market has transitioned from post-pandemic normalization to a new cycle defined by technological specialization, supply chain recalibration, and accelerating demand from high-growth end-use sectors. For executives, procurement leaders, and R&D strategists, the window to align product roadmaps, capacity planning, and partnership ecosystems with this shift is narrow. This introduction outlines how our newly released Electronic Components Market study translates raw market signals into actionable intelligence, equipping your organization with the foresight required to navigate 2026 and beyond.
Market Trajectory: From Recovery to Structural Growth
The historical trajectory of the electronic components sector reveals a market that has consistently outpaced broader industrial benchmarks. Between 2020 and 2025, global revenue climbed from approximately 300 billion USD to 438.5 billion USD, reflecting a compounding pattern of demand recovery, design cycle maturation, and geographic diversification. Our research projects this momentum to accelerate through the 2026–2032 forecast period, with the total addressable market expected to surpass 717 billion USD by 2032. This equates to a compound annual growth rate of 7.36 percent, a figure that underscores not only cyclical recovery but also the structural embedding of advanced electronics into previously underserved sectors.
The speed and scale of this expansion, however, mask underlying volatility. Demand is no longer distributed uniformly across product categories or geographies. Instead, it concentrates in applications demanding higher performance tolerances, longer lifecycle reliability, and tighter integration with software-defined architectures. Organizations that rely on legacy supply arrangements or single-source procurement models will find themselves exposed as lead times fluctuate, material constraints emerge, and regional manufacturing footprints shift. Understanding these dynamics requires more than top-line forecasts; it demands granular visibility into how value flows through the component ecosystem.
Competitive Architecture: Consolidation, Differentiation, and Ecosystem Control
The competitive landscape of the electronic components sector is characterized by a tiered structure of integrated manufacturers, specialized technology leaders, and global distribution networks. At the upper end of the value chain, a concentrated group of firms controls a measurable share of total industry revenue, with the top five players collectively accounting for over half of market output. This concentration reflects deliberate strategies around portfolio breadth, process technology leadership, and long-term customer lock-in through reference designs and firmware ecosystem integration.
Among the most influential manufacturers are firms anchored in analog and mixed-signal innovation, precision sensing, and power conversion. Companies such as Texas Instruments and Analog Devices have built formidable positions by aligning their product roadmaps with industrial automation, medical instrumentation, and automotive electrification. Their competitive advantage stems not merely from volume, but from the ability to deliver silicon solutions that reduce system-level complexity while maintaining stringent reliability standards.
Parallel to this analog-centric tier, European and Japanese power semiconductor leaders have carved out dominant positions in wide-bandgap technologies and automotive-grade discretes. Infineon Technologies, STMicroelectronics, and NXP Semiconductors continue to expand their footprints through targeted capacity investments and application-specific architectures, particularly in electric vehicle powertrains, battery management, and secure connectivity. Renesas Electronics and ON Semiconductor reinforce this momentum with deep portfolios in microcontrollers, intelligent sensing, and high-efficiency power management designed for harsh operating environments.
In the passive and electromechanical domain, Japanese manufacturers remain foundational to global supply. Murata Manufacturing and TDK Corporation drive volume leadership in capacitors, inductors, RF modules, and sensor-integrated components, serving consumer electronics, industrial controls, and infrastructure systems. Amphenol Corporation and TE Connectivity extend the value chain into interconnect systems, where miniaturization, high-speed signal integrity, and durable power transmission increasingly dictate end-product performance. Littelfuse, Vishay Intertechnology, and Panasonic round out the component landscape with specialized contributions in circuit protection, discrete devices, and electronic materials that support system resilience.
Complementing manufacturing concentration is a robust distribution layer that shapes how components reach design engineering teams and production lines. Mouser Electronics, Arrow Electronics, Digi-Key Electronics, Future Electronics, and Avnet operate as critical nodes in the innovation pipeline, frequently serving as the first point of contact for new product introductions and hard-to-source revisions. Regional distributors such as Smith, TTI, RS Components, WPG Holdings, and WT Microelectronics provide localized inventory depth, technical support, and supply chain risk mitigation. The strategic relevance of this distribution tier has intensified as semiconductor lead times fluctuate and engineering teams demand rapid prototyping access without compromising qualification standards.
Recent Developments Shaping the Competitive Landscape
Recent activity among leading players illustrates how quickly strategic priorities can shift in response to capacity, technology, and market signals. In May 2026, Nexperia announced a strategic partnership with Polar Semiconductor to strengthen global production stability for power MOSFETs, a move that directly addresses supply continuity in discrete semiconductor segments. The same month, Infineon Technologies showcased advances in physical AI security solutions tailored for NVIDIA Jetson Thor platforms at PCIM Europe, signaling a deeper convergence between component-level security architecture and edge artificial intelligence deployments. Infineon also reinforced its manufacturing expansion strategy through the operational launch of a new semiconductor plant in Thailand dedicated to power modules, adding geographic diversity to its production base.
On the distribution and service side, Mouser Electronics added more than 9,000 new parts to its catalog in the first quarter of 2026, including over 1,200 semiconductors and electronic components, expanding access to next-generation design options. Future Electronics launched a quarterly digital campaign centered on industrial automation innovation, reinforcing its positioning in automation-heavy verticals. These actions, taken together, highlight a market where speed-to-market, regional capacity balancing, and ecosystem engagement increasingly determine competitive advantage.
Demand Architecture: Where Growth Is Concentrated
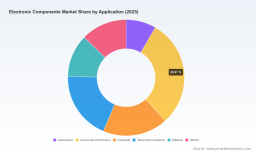
The composition of market demand reveals a landscape far more nuanced than aggregate revenue figures suggest. Consumer electronics continue to represent the largest single application block, driven by iterative upgrades in smart devices, connectivity infrastructure, and high-integration subsystems. Telecommunications maintain a substantial footprint, supported by network modernization, edge processing requirements, and the relentless push toward higher bandwidth and lower latency. Industrial applications contribute a robust and increasingly resilient demand base, as automation, robotics, electrification of plant equipment, and condition monitoring systems integrate more sophisticated control and sensing architectures.
Electronics Market
Automotive remains a critical growth engine, though its component demand profile differs markedly from consumer volumes. Vehicles now function as distributed computing platforms, requiring microcontrollers, power semiconductors, security-enabled connectivity ICs, and reliable passive networks that can withstand extended lifecycle conditions. Medical electronics represent another structurally attractive segment, where precision analog performance, sensor integration, and regulatory-grade reliability command premium positioning. Other application areas contribute additional demand layers, each with distinct qualification requirements, volume patterns, and supplier relationship dynamics.
By component category, active devices dominate total market value, reflecting the centrality of analog ICs, microcontrollers, power management, and precision components across modern systems. Passive and electromechanical components form an essential complementary layer, underpinning signal conditioning, power distribution, noise suppression, and mechanical-electrical interconnection. The interplay between these categories determines system cost, thermal performance, and board-level layout efficiency, making broad classification an insufficient lens for strategic planning.
Operational Forces Redefining Supply and Planning Assumptions
Behind the top-line growth narrative lies a set of operational realities that will shape procurement and engineering decisions in 2026. Memory chip production has struggled to keep pace with rapidly expanding demand, a supply-demand imbalance reflected in trade flows from major producing economies across South Korea, mainland China, Japan, and Taiwan. This constraint influences not only memory pricing but also the availability of integrated modules and systems that depend on tight component coordination.
Lead time variability remains a persistent concern for design and production planning. Extended availability windows for certain high-demand series, including automotive-grade microcontrollers, have been reported at multi-month ranges, forcing manufacturers to hold deeper safety stock, qualify alternate sources earlier, and adjust bill-of-materials strategies. At the same time, regional manufacturing developments continue to reshape the supply base. New production capacity coming online in Southeast Asia, alongside continued concentration of advanced semiconductor fabrication in Taiwan, introduces both diversification benefits and geopolitical dependencies that procurement teams must monitor continuously.
Regulatory pressure is also entering the cost and sourcing calculus. The European Union's Carbon Border Adjustment Mechanism has begun publishing quarterly certificate pricing data, adding a new dimension to cross-border component flows and encouraging suppliers and buyers alike to account for embedded emissions in sourcing decisions. In parallel, localized chip production initiatives in China and evolving manufacturing strategies among discrete device producers are creating ripple effects across commoditized and mid-tier component segments. These developments are not isolated events; they are structural inputs that influence lead time predictability, total cost of ownership, and supplier selection criteria.
What the Full Study Delivers: Turning Intelligence into Execution
Our comprehensive Electronic Components Market study is designed to move beyond headline forecasts and provide decision-makers with a structured, execution-ready intelligence framework. The report examines market size evolution across the historical baseline and the 2026–2032 forecast horizon, linking growth trajectories to demand intensity, component type dynamics, and application-specific adoption patterns. It maps the strategic positioning of leading manufacturers and distribution partners, highlighting portfolio focus, technology emphasis, and the competitive logic that shapes pricing power and customer retention.
Beyond competitive profiling, the study dissects the macro and micro forces currently driving the market: raw material and memory capacity conditions, lead time volatility, regulatory mechanisms such as carbon-related border measures, and the persistent importance of geographic manufacturing concentration. These dynamics are evaluated in the context of procurement risk, engineering design windows, and long-term supply continuity. The report also provides scenario-aware guidance for capacity planning, alternate sourcing strategies, and innovation timing, enabling teams to translate market signals into operational controls rather than reactive adjustments.
Importantly, the study deliberately avoids one-size-fits-all conclusions. Instead, it isolates where strategic leverage exists for different organizational roles: product strategy, supply chain resilience, regional sourcing, and technology investment. By connecting market size pathways with competitive behavior and operational constraints, the report gives leadership a coherent view of where margin protection, growth capture, and risk mitigation intersect.
Why This Research Matters Now
Market intelligence in the electronic components sector only creates value when it is precise enough to reshape decisions. The trajectory toward a 717 billion USD market by 2032 is not simply a validation of growth; it is a signal that competition for differentiated components, qualified supply relationships, and engineering bandwidth will intensify. Organizations that wait for quarterly updates to interpret structural shifts will find themselves reacting to conditions already priced into the market. Those that combine application-level foresight with disciplined sourcing and design strategy will be positioned to capture disproportionate value from the same environment.
The full research report expands on every dimension outlined here, delivering the detailed segmentation analysis, competitive benchmarking, dynamics assessment, and actionable strategic guidance necessary to support 2026 planning cycles and multi-year investment decisions. The complete dataset, scenario-based interpretation, and executive frameworks are available through the full market report. To access the complete intelligence suite and integrate it directly into your strategic planning, explore the full study at the source page.
Electronic Components Market
For detailed analysis of this topic, please visit the official page: Electronic Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com