

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Global Omni-channel Warehouse Management Systems Hit $4.99B in 2025, 13.98% CAGR to 2032
By pmarketresearch, 2026-09-16
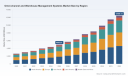
Strategic Intelligence for the Omni-Channel Warehouse Era: Insights from the 2026 Global Market Study
The global supply chain has entered a period of irreversible transformation. As customer expectations for speed, transparency, and seamless fulfillment continue to rise, warehouse management systems (WMS) and omni-channel orchestration platforms have evolved from back-office utilities into core strategic assets. Our newly released Worldwide Omni-channel and Warehouse Management Systems Market research study provides decision-makers with a comprehensive, data-driven roadmap for navigating this shift through 2032. Built on rigorous primary and secondary research, the report translates macro-market momentum into actionable intelligence tailored for enterprise strategists, procurement leaders, and technology architects operating in 2026 and beyond.
Retail Omni Channel Commerce Platform Market
At the foundation of this analysis lies a clear macroeconomic signal: the market has demonstrated sustained, double-digit expansion over the past half-decade, with historical valuations climbing steadily from 2020 through 2025. This trajectory reflects not only incremental digital adoption but a structural reorientation of how organizations design, operate, and scale distribution networks. Looking forward, the study projects continued aggressive growth across the forecast horizon, underpinned by a compound annual growth rate that underscores the strategic urgency of modernizing warehouse execution capabilities. Rather than presenting isolated figures, our methodology contextualizes this momentum within operational realities, investment cycles, and competitive pressures that will define enterprise technology roadmaps in the coming years. Readers seeking the full numerical architecture, scenario modeling, and granular segmentation will find a direct pathway to the complete dataset within the published study.
Why 2026 Demands a New WMS Investment Thesis
Entering 2026, the operational imperative has shifted from incremental efficiency gains to architectural resilience. Several converging forces are redefining how enterprises evaluate warehouse technology investments, and each carries distinct implications for budget allocation, platform selection, and vendor partnerships. First, cloud-native deployment has fundamentally altered the capital expenditure profile of warehouse modernization. By eliminating heavy upfront infrastructure burdens and enabling elastic scaling, cloud-based architectures have captured a dominant share of new implementations. Organizations are no longer choosing between cloud and on-premise as theoretical alternatives; they are weighing total cost of ownership, update cadence, and integration velocity against legacy technical debt. The study dissects this transition across deployment models, highlighting how procurement teams are recalibrating ROI frameworks to prioritize continuous innovation over static license agreements.
Second, labor economics continue to pressure distribution networks worldwide. Chronic workforce constraints, coupled with rising wage expectations and training overhead, have made productivity amplification a non-negotiable requirement. Advanced WMS platforms now deliver measurable throughput improvements and meaningful reductions in operational downtime by orchestrating labor allocation, routing optimization, and real-time task interleaving. These capabilities are no longer treated as optional enhancements; they are embedded into the core value proposition of leading solutions. Our analysis quantifies the operational leverage that modern execution engines provide, enabling leadership teams to model labor risk mitigation against technology investment timelines.
Third, regulatory and compliance expectations are tightening across regulated sectors. Traceability mandates, serialization requirements, and data protection standards are reshaping warehouse compliance from a reactive audit function into a proactive system design principle. Industries handling pharmaceuticals, food, and sensitive consumer goods now require automated batch tracking, audit-ready documentation, and continuous risk management baked into daily operations. The study explores how modern platforms are absorbing these requirements through built-in compliance workflows, reducing manual oversight while maintaining readiness for evolving global standards. For enterprises operating across multiple jurisdictions, this dynamic introduces both complexity and competitive differentiation opportunities that the report examines in detail.
Inside the Study: What Decision-Makers Will Find
This market research is structured to serve both strategic planning and operational evaluation. Rather than offering a superficial survey of vendor offerings, the report delivers a layered analytical framework designed to support purchasing committees, CIO offices, and supply chain transformation teams. The study opens with a comprehensive market overview that maps historical performance against forward-looking projections, establishing a reliable baseline for scenario planning. From there, it progresses into segmentation analysis that disaggregates demand drivers across deployment preferences, end-user industries, and regional adoption patterns. Each segment is evaluated not merely by size, but by structural growth catalysts, adoption barriers, and technology readiness levels that influence procurement timing.
A dedicated competitive landscape module examines the positioning, capability maturity, and strategic maneuvering of the market's most influential players. The analysis moves beyond feature checklists to assess how leading vendors are orchestrating cloud migration, automation integration, and ecosystem expansion. Readers will find executive profiling that connects corporate strategy with product evolution, revealing where consolidation, partnership, and platform bundling are reshaping buyer options. This section is particularly valuable for organizations conducting vendor shortlisting, as it highlights divergent approaches to omni-channel orchestration, labor management, returns handling, and cross-functional integration with transportation and enterprise resource planning environments.
The operational dynamics portion of the study connects technology capability with real-world execution outcomes. It addresses how modern WMS environments are converging with warehouse control systems, execution software, and distributed order management to eliminate planning silos and improve end-to-end visibility. The report also evaluates integration complexity, data governance requirements, and the growing importance of security architecture in multi-tenant cloud deployments. By framing these considerations within procurement and implementation contexts, the study equips leaders with the language and structure needed to translate technical specifications into business-case justification.
To support practical decision-making, the research includes actionable frameworks for evaluating total cost of ownership, assessing cloud migration readiness, and aligning platform selection with industry-specific compliance demands. Case-driven observations illustrate how organizations across retail, manufacturing, food and beverage, healthcare, and third-party logistics are deploying execution technology to resolve fulfillment friction, improve inventory accuracy, and scale without proportional headcount growth. These insights are presented with enough depth to inform internal benchmarking while preserving the strategic objectivity required for unbiased vendor evaluation.
Competitive Landscape: Signals from the Market's Core Players
The vendor ecosystem surrounding omni-channel and warehouse management systems is characterized by both intense competition and rapid structural evolution. A small group of established enterprise platforms continues to anchor significant market share, while a broader field of specialized and regional players competes on implementation agility, industry-specific workflows, and Total cost of ownership. The study maps this landscape through a careful examination of strategic positioning, product architecture, and recent market activity that signals where the industry is heading.
Among the most influential enterprise vendors, Manhattan Associates has maintained a prolonged record of recognition for its cloud-native Active Warehouse Management approach, which emphasizes simultaneous order streaming across wholesale, retail, and direct channels alongside real-time visibility and labor optimization. Its continued leadership positioning, reinforced by high-profile deployments and recurring analyst acknowledgments, reflects a strategy centered on unified omni-channel execution and deep integration with transportation and distribution operations. Blue Yonder has pursued a complementary trajectory, pairing mature warehouse management functionality with workforce performance tools, returns management, and AI-driven orchestration designed for complex distribution environments. Together, these two platforms illustrate how leading vendors are expanding beyond task-level execution into predictive, network-aware fulfillment orchestration.
Large enterprise software ecosystems also remain pivotal. SAP SE continues to leverage its Extended Warehouse Management capability as an integral component of broader supply chain and ERP architectures, appealing to organizations that prioritize tightly coupled inventory control, resource optimization, and cross-docking within a unified enterprise environment. Oracle Corporation pursues a similar integration advantage through its cloud-based warehouse management offerings, embedding mobile capabilities, labor management, and omni-channel support into wider ERP and supply chain platforms. For enterprises already committed to these ecosystems, the strategic question is rarely whether the platform can manage warehouse operations, but how seamlessly it orchestrates them alongside finance, planning, and customer-facing systems.
Infor maintains a strong presence as a cloud-based tier-1 solution provider with particular resonance in manufacturing, distribution, retail, and food and beverage contexts. Its emphasis on inventory optimization, labor management, and third-party logistics capability positions it as a versatile execution platform for organizations seeking industry-tailored functionality without sacrificing cloud scalability. Körber Supply Chain, now operating under its Infios brand following a 2025 rebranding, has simultaneously consolidated its WMS portfolio with warehouse control systems and broadened its execution suite through the acquisition of a transportation management provider. This move reflects a wider industry pattern: vendors are actively reducing planning silos by merging warehouse execution with transportation visibility, enabling more coherent end-to-end supply chain control.
Beyond the entrenched enterprise leaders, a diverse set of specialist and mid-market vendors continues to shape buyer options. Made4net focuses on web-based, cost-effective implementations built on widely understood technology stacks, targeting small-to-mid-sized manufacturers and distributors that value inventory accuracy and labor productivity without enterprise-level complexity. Softeon emphasizes advanced distribution and omni-channel execution with strong integration flexibility for complex warehouse environments. Tecsys brings enterprise-grade execution capabilities with notable relevance in distribution and healthcare, where traceability and controlled handling are especially critical. Deposco has carved a cloud-native niche tailored to third-party logistics providers, bundling distributed order management, planning, and billing on a multi-tenant platform designed for omni-channel scale.
Worldwide Omni-channel and Warehouse Management Systems Market
International participants further diversify the competitive field. Mecalux offers multichannel fulfillment and space utilization optimization through its Easy WMS platform, while Generix Group and Logistics Reply serve manufacturing, wholesale, retail, and 3PL contexts with execution software oriented toward omni-channel process maturity. Hardis Supply Chain has expanded its footprint through SaaS-based warehouse control, omni-channel order orchestration, and in-store logistics capabilities, including recent North American expansion supported by automation partnerships and a strategic transformation agreement with a global retailer. These movements illustrate how regional strength, automation alignment, and channel-specific logistics are becoming decisive differentiators in a market where feature parity alone no longer guarantees competitive advantage.
Recent industry activity reinforces the sense of accelerating consolidation and platform expansion. The completion of a major transportation management acquisition by Körber Supply Chain Software signals a deliberate push toward integrated planning across warehouse and transport domains. Meanwhile, product launches in cloud-based warehouse execution software and sustained recognition of market leaders reflect a broader shift toward real-time orchestration of picking, routing, and order management. For procurement and strategy teams, these developments matter because they reshape integration expectations, expand platform scope, and alter the cost and complexity of multi-vendor architectures. The study synthesizes these signals into a coherent competitive map, enabling readers to anticipate vendor roadmaps rather than merely react to them.
Watching the Structural Shifts Reshaping the Market
Beyond vendor activity and segment sizing, the study pays close attention to the structural dynamics that will determine which organizations capture value from warehouse technology investments and which merely incur cost. Cloud adoption continues to dominate implementation discussions, not simply because of lower upfront capital demands, but because elastic scalability, continuous updates, and reduced maintenance overhead change how IT and supply chain teams plan for growth. At the same time, compliance pressure is intensifying across regulated industries. Detailed batch and serial tracking, automated audit readiness, and stringent data protection controls are becoming baseline expectations rather than premium add-ons. The report examines how these requirements influence platform selection, especially in pharmaceutical, food, and healthcare environments where operational failures carry both financial and reputational risk.
Labor dynamics further complicate the investment calculus. With distribution networks facing persistent workforce challenges, the ability of a WMS to improve throughput and reduce downtime has become a direct contributor to operational resilience. The study frames advanced execution capabilities as a strategic lever for mitigating labor volatility, emphasizing that technology evaluation must now account for productivity outcomes alongside functional coverage. Data security and information governance also occupy a more prominent place in procurement criteria, as cloud and SaaS deployments require controlled access, robust audit trails, and continuous risk management. These factors are no longer peripheral concerns; they are integral to the credibility of any warehouse technology investment.
Positioning Your Organization for the 2032 Outlook
The most valuable insight in this study is not any single statistic, but the structured understanding it provides of how market forces will interact over the next several years. The forecast period extends well beyond the immediate procurement cycle, allowing leadership teams to model technology roadmaps against evolving fulfillment expectations, regulatory milestones, and competitive pressure. Organizations that treat WMS and omni-channel orchestration as static tooling risk being outpaced by those that align platform strategy with continuous orchestration, automation readiness, and compliance-by-design architecture. The research offers the analytical backing needed to make that alignment deliberate rather than reactive.
For enterprises evaluating platform migration, vendor consolidation, or greenfield implementation in 2026, the complete study delivers the depth required to move from high-level direction to confident execution. It combines market sizing, segment intelligence, competitive profiling, and operational context into a single decision-support resource calibrated for strategic planning. Readers who require the full breakdown of market projections, deployment trends, end-user dynamics, regional patterns, and vendor comparisons will find the complete dataset and analytic framework available through the published research. In a market expanding at this pace, the advantage belongs to those who replace assumption with evidence, and the study is built to make that transition possible.
For detailed analysis of this topic, please visit the official page: Worldwide Omni-channel and Warehouse Management Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High-Speed Spectroscopy Camera Market Hits $564M in 2025, Projects 7.82% CAGR Through 2032
By pmarketresearch, 2026-09-16
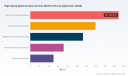
Strategic Intelligence for the High-Speed Spectroscopy Cameras Market: Navigating the 2026–2032 Growth Horizon
The global market for high-speed spectroscopy cameras is entering a decisive phase of acceleration. As industries from biomedical research to industrial inspection demand faster, more sensitive spectral imaging, the equipment landscape is shifting from niche laboratory instruments to integrated, high-throughput analytical systems. This article previews the strategic findings of our latest Worldwide High Speed Spectroscopy Cameras Market research, designed to equip enterprise leaders, investors, and technology strategists with the contextual intelligence required for decisive action in 2026 and beyond.
Our analysis tracks a market that has consistently expanded through a period of technological maturation and application diversification. From 2020 through 2025, the sector moved from a base of approximately 395 million USD to an estimated 564 million USD, reflecting a compound annual growth trajectory that continues into the forecast window. By 2026, total market revenue is projected to reach roughly 590 million USD, with sustained momentum carrying the market toward nearly 956 million USD by 2032. The forecast period CAGR stands at 7.82%, signaling a healthy, structural expansion rather than a short-lived cyclical spike. For decision-makers, this trajectory underscores the importance of positioning now: the window to influence product roadmaps, supply partnerships, and commercial entry strategies is open, but it will not remain wide indefinitely.
Why 2026 Is a Strategic Inflection Point
Several concurrent forces are compressing the timeline for strategic action. First, the integration of high-speed sCMOS and hyperspectral cameras into multimodal systems is reshaping procurement behavior across hospitals and research institutions. Capital expenditure trends increasingly favor instruments that deliver real-time spectral analysis within broader diagnostic or material-characterization workflows, rather than standalone spectroscopic devices. Second, the regulatory and quality-assurance environment is crystallizing. Cameras deployed in medical imaging applications, including near-infrared spectroscopy for wound and flap management, operate within established coverage frameworks, while medical-device implementations must align with ISO 13485 quality management expectations and standard FDA 510(k) pathways for Class II imaging systems where applicable. Third, the optics and photonics ecosystem is evolving at the component level, with line-rate performance, low-noise behavior, and spectral-range extensibility becoming baseline expectations in competitive bids for both research and industrial deployments.
Taken together, these dynamics create a market that rewards speed, integration, and compliance readiness. Companies that treat high-speed spectroscopy cameras as isolated sensors risk being outpaced by competitors who embed them into complete analytical solutions. The 2026 outlook is therefore not merely about market size; it is about where value is created along the chain—from detector architecture and cooling performance to software integration, application-specific calibration, and service support.
Worldwide High Speed Spectroscopy Cameras Market
Report Scope and Decision-Ready Coverage
Our Worldwide High Speed Spectroscopy Cameras Market study is structured around actionable clarity. Rather than offering a high-level narrative alone, the report delivers a fully integrated analytical framework that connects market sizing, segmentation logic, competitive positioning, and operational dynamics. The core content is designed to support concrete decisions in product planning, market entry, partnership evaluation, and investment allocation.
The report architecture includes the following components:
- Historical and forecast market sizing spanning 2020 through 2032, with a 2025 base year and a 2026–2032 forecast horizon, presented in millions of USD to support financial modeling and revenue planning.
- Segment-level market views across sensor technology categories and end-use applications, enabling teams to identify where growth is concentrated and which segments warrant differentiated positioning.
- Regional market distribution that contextualizes demand intensity and operational priorities across major geographies, supporting go-to-market and supply-chain planning without over-indexing on any single territory.
- Competitive landscape analysis covering the principal participants shaping the market, with profile summaries that highlight technological emphasis, application focus, and deployment models.
- Recent developments and technology signals drawn from product launches, catalog updates, and industry events, helping leaders track near-term shifts in capability and commercial intent.
- Market dynamics and structural themes that examine concentration patterns, procurement behavior, and the interplay between regulation, clinical adoption, and industrial integration.
The report is built for practical use. Executive summaries connect high-level trends to operational implications, while detailed tables and analytical sections allow specialists to validate assumptions for pricing strategy, segment targeting, and capability investment. Importantly, the study is designed to answer not just how large the market is, but how the market works: which technology families dominate volume and value, which applications are expanding fastest in research versus commercial settings, and how leading companies are positioning their portfolios to capture share in a consolidating environment.
Competitive Landscape: A Consolidated Field With Differentiated Strengths
The market is characterized by a meaningful degree of concentration, with the top three players accounting for a substantial share of total revenue and the top five representing an even larger portion of industry activity. This structure matters for strategy. It suggests that incumbents hold strong positions in application credibility, installed-base relationships, and technology maturity, while also indicating that differentiated innovations—particularly in speed, sensitivity, spectral range, and integration—can still create footholds for specialized challengers.
Several companies define the current competitive fabric. Andor Technology, part of Oxford Instruments, offers high-sensitivity sCMOS, EMCCD, and CCD spectroscopy cameras, including the Newton and iDus series, optimized for high-speed spectroscopy in scientific and medical research. Teledyne Princeton Instruments provides BLAZE and other high-speed, low-noise CCD and sCMOS spectroscopy cameras tailored for Raman, hyperspectral, and transient spectroscopy in life sciences and medical imaging. Hamamatsu Photonics supplies high-performance photonic detectors and cameras with high-speed options relevant to near-infrared spectroscopy and medical imaging. HORIBA Scientific develops deep-cooled high-speed scientific CMOS cameras, such as the Sylent series, alongside spectrometers for high-speed spectroscopy in biomedical and clinical diagnostics.
The field also includes specialists that compete on spectral imaging architecture and deployment flexibility. Specim, part of Konica Minolta, specializes in high-speed push-broom hyperspectral cameras, including the FX series with recent NIR-SWIR models, used in spectral imaging for industrial and medical material analysis. Headwall Photonics manufactures high-performance hyperspectral imaging systems and cameras for medical, remote sensing, and high-speed spectral applications. XIMEA GmbH offers miniaturized, high-speed hyperspectral cameras designed for OEM integration in scientific, medical, and high-throughput spectroscopy systems. Photon etc. provides hyperspectral imaging systems and high-speed cameras through distribution partnerships, serving medical and scientific spectroscopy needs. HySpex, under Norsk Elektro Optikk, delivers high-performance hyperspectral cameras across VIS-NIR-SWIR for research, industrial, and medical spectral imaging. BaySpec develops compact, high-speed spectral imaging and spectroscopy cameras oriented toward biomedical diagnostics and medical device integration.
Strategic interpretation of this landscape goes beyond brand recognition. The competition is increasingly defined by how well a company can match detector performance to workflow requirements, support multimodal integration, and sustain reliable supply and service across demanding applications. In practice, this means that product differentiation is narrowing at the sensor level while widening at the system and solution level. Companies that can reduce time-to-result, improve repeatability, and simplify integration are more likely to secure long-term contracts in research, clinical, and industrial environments.
Market Dynamics and Emerging Technology Signals
The market’s growth is being reinforced by several operational and technological currents. Demand for high-speed spectral imaging is rising in ophthalmology and in-vitro diagnostics, where high line rates and low-noise performance are essential to real-time analysis. At the same time, procurement patterns in hospitals and research organizations increasingly favor integrated platforms that combine spectroscopy with complementary imaging modalities. This creates a landscape in which camera specifications are evaluated not only on their own merits but also on their ability to interface cleanly with broader analytical and diagnostic workflows.
On the technology side, recent product activity highlights where the industry is placing its bets. In February 2026, Specim unveiled the Specim FX19, a high-speed push-broom NIR-SWIR hyperspectral camera covering 1130–1920 nm and optimized for high-accuracy material inspection in industrial settings, with potential relevance to medical spectral applications. In January 2026, New Imaging Technologies announced the upcoming LiSa SWIR 2048R M-STE2 rectangular-pixel SWIR camera for high-speed imaging, introduced at SPIE Photonics West 2026 with relevance to spectroscopy systems. Earlier, in July 2025, Photon etc., via Pembroke Instruments, released updated datasheets for the Zephir 2.5e hyperspectral camera and related high-speed SWIR hyperspectral systems suitable for scientific and medical spectroscopy.
These developments are not isolated announcements; they illustrate a broader shift toward extended spectral coverage, faster acquisition, and more application-tuned system designs. For market participants, the strategic implication is clear. Roadmap decisions should prioritize not just incremental sensitivity gains but the ability to serve demanding use cases in real time, across broader wavelength ranges, and within environments that require robust calibration, thermal management, and integration support.
Regulatory and quality considerations add another layer of strategic importance. In medical-imaging contexts, high-speed spectroscopy cameras used in near-infrared applications for wound and flap management fall under existing Medicare Local Coverage Determinations, without specific new CPT code updates identified for 2025–2026. Meanwhile, spectroscopy cameras incorporated into medical devices must comply with ISO 13485 quality management systems and, where used in diagnostic applications, follow general FDA 510(k) pathways for Class II imaging systems. These requirements do not slow the market; rather, they shape the competitive filter. Organizations that can demonstrate disciplined quality processes and predictable regulatory alignment are better positioned to convert technical capability into commercial traction.
Strategic Takeaways for 2026 Decision-Making
As leaders plan for the remainder of 2026 and the forecast period ahead, several priorities emerge from the market structure:
Raman Spectroscopy Market
- Position for integration, not just detection. The market is rewarding systems that deliver real-time spectral analysis within multimodal workflows. Roadmaps should consider software interfaces, calibration support, and compatibility with broader analytical platforms.
- Align sensor strategy with application demand. sCMOS and related high-speed, low-noise technologies continue to anchor significant value, while specialized technologies address distinct spectral-range and sensitivity requirements. Segment selection should follow application economics, not technology novelty alone.
- Treat regional demand as a planning variable, not a blanket assumption. Different geographies exhibit distinct procurement patterns and application mixes. Market-entry and capacity decisions should reflect local demand intensity and the relative importance of research, industrial, and clinical deployments.
- Build competitive resilience through speed and service. With a concentrated competitive field, differentiation increasingly comes from delivery reliability, integration support, and the ability to reduce deployment friction for end users.
- Prepare for regulatory and quality expectations early. In medical and diagnostic-adjacent applications, alignment with ISO 13485 and relevant device-classification pathways can be a decisive factor in procurement confidence and time-to-market.
The numbers tell a compelling story of expansion, but the real strategic value lies in the market’s structure: where value is created, how incumbents defend share, and where new entrants or expanding players can differentiate meaningfully. The overall revenue path from roughly 590 million USD in 2026 to nearly 956 million USD by 2032, at a 7.82% forecast CAGR, indicates that high-speed spectroscopy cameras are becoming a foundational component of advanced analysis across multiple industries. Yet the details—how segments balance against each other, which applications drive the fastest growth, and how competitive concentration evolves—determine whether a company captures only the tailwind or converts it into durable advantage.
Access the Full Intelligence Suite
This article provides a strategic preview of the market environment and the decision context it creates. To move from directional confidence to precise planning, enterprise teams need the complete dataset, segment logic, regional breakdowns, and competitive profiles that underpin our conclusions. The full Worldwide High Speed Spectroscopy Cameras Market report delivers the granular analysis required to translate market trajectory into product strategy, commercial execution, and investment prioritization.
Readers seeking the complete market sizing tables, detailed segmentation views, company profiles, and tracked recent developments are encouraged to access the full study through our official report page. There, the full intelligence suite provides the depth needed to support board-level discussions, R&D planning, partnership screening, and market-entry decisions with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide High Speed Spectroscopy Cameras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Ibrutinib Market Hits $954.91M in 2025, 3.88% CAGR to 2032
By pmarketresearch, 2026-09-16
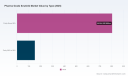
Strategic Intelligence for 2026: Navigating the Pharma Grade Ibrutinib Market
The global pharmaceutical landscape is entering a definitive period of transformation, characterized by the complex interplay of patent cliffs, biosimilar competition, and evolving reimbursement architectures. At the center of this shift lies the Pharma Grade Ibrutinib Market, a critical segment within the oncology supply chain that demands precise strategic positioning. As enterprise leaders formulate their roadmaps for 2026 and beyond, understanding the nuanced trajectory of this market is not merely an academic exercise but a commercial imperative. This insight serves as a precursor to our comprehensive Worldwide Pharma Grade Ibrutinib Market research, designed to equip stakeholders with the actionable intelligence required to mitigate risk and capture growth in a maturing therapeutic category.
Our analysis indicates that the sector is moving past the early adoption phase of novel BTK inhibitors into a period of stabilized demand and intensified supply chain scrutiny. For manufacturers, procurement officers, and investment strategists, the ability to distinguish between short-term volatility and long-term structural trends will define competitive advantage. The following overview outlines the macro-economic context, the competitive architecture, and the regulatory headwinds that our full report dissect in granular detail.
Market Magnitude and Growth Trajectory
To anchor strategic planning, one must first establish the baseline of market performance. Historical data from 2020 through 2025 reveals a consistent upward trajectory in revenue generation for pharma grade ibrutinib. The market has demonstrated resilience even amidst broader pharmaceutical supply chain disruptions. Our baseline year analysis places the 2025 revenue at approximately 954.91 Million USD, reflecting a mature yet expanding ecosystem. This growth is not accidental; it is driven by entrenched usage in key oncology indications and the gradual expansion of formulations to improve patient compliance.
Worldwide Pharma Grade Ibrutinib Market
Looking forward, the forecast period spanning 2026 to 2032 suggests a continued, albeit moderated, expansion. The projected Compound Annual Growth Rate (CAGR) stands at 3.88 percent. This figure is critical for financial modeling, as it implies a market that is growing organically without the explosive entry seen in novel first-in-class drugs. By 2032, the market revenue is projected to reach 1246.34 Million USD. This steady climb underscores the enduring relevance of ibrutinib in treatment protocols, even as next-generation inhibitors enter the pipeline. However, the path to 2032 is not linear. Stakeholders must account for regulatory milestones and pricing pressures that could alter the slope of this growth curve.
Understanding the aggregate size is only the first step. The distribution of this value across regions and applications tells the real story of where value is created and captured. Our full report delineates these segments without exposing the primary intelligence to the open market, ensuring that subscribers gain an edge over competitors who rely on public estimates.
Key Report Content and Operational Utility
The value of a market study lies in its applicability to daily decision-making. Our research is constructed to serve as a functional toolkit rather than a static document. It encompasses a deep dive into the supply chain mechanics, from active pharmaceutical ingredient (API) sourcing to finished dosage form distribution. We analyze the purity standards that dominate the market, distinguishing between high-purity grades required for branded formulations and the specifications acceptable for generic entrants. This distinction is vital for procurement teams negotiating contracts with API manufacturers in regions such as India and China, where production capabilities vary significantly.
Furthermore, the report details the regulatory landscape governing production and distribution. Quality compliance, Good Manufacturing Practice (GMP) certifications, and regional approval statuses are mapped out to identify potential bottlenecks. For companies looking to enter the market or expand their footprint, understanding the licensing environment is as important as understanding the demand volume. The study also covers logistics and distribution channels, highlighting how temperature-sensitive formulations and oral suspensions are managed across different geographies. This operational granularity allows supply chain managers to stress-test their networks against potential disruptions.
Another critical component is the analysis of pricing dynamics at the raw material level. Transaction-based pricing for ibrutinib API fluctuates based on quantity and destination, creating opportunities for arbitrage or cost optimization depending on the buyer's location and volume commitments. Our report synthesizes this data to provide a benchmark for cost modeling, enabling manufacturers to set competitive pricing strategies without eroding margins.
Competitive Landscape and Strategic Positioning
The market structure is defined by a mix of originator companies and a robust cohort of generic manufacturers. The concentration of market power is significant, with the top three companies holding a substantial share of the revenue. This concentration suggests that barriers to entry remain high, particularly in regulated markets like North America and Europe. However, the presence of multiple active players from India indicates a competitive pressure that will intensify as patent protections evolve.
Leading the branded segment are Janssen Pharmaceuticals (Johnson & Johnson) and Pharmacyclics LLC (AbbVie). These entities remain the dominant commercializers of the branded Imbruvica formulation. Their strategy involves not just maintaining market share but expanding the utility of the drug through new formulations and clinical data. For instance, recent clinical data presentation from November 2025 regarding the Phase 3 CLL17 trial results comparing fixed-duration IMBRUVICA plus venetoclax versus continuous IMBRUVICA in previously untreated CLL at the ASH 2025 plenary session signals a shift in treatment paradigms. Such data can influence prescribing habits and volume demand, making it essential for competitors to monitor these developments closely.
On the generic side, the landscape is dense with activity. Indian pharmaceutical companies are particularly prominent. Natco Pharma Ltd, MSN Labs, Dr. Reddy's Laboratories, Hetero Labs Limited, and Zydus Lifesciences Limited are all active producers or developers of ibrutinib API and formulations. Zydus Lifesciences Limited notably received tentative FDA approval for generic ibrutinib tablets in multiple strengths for CLL/SLL and WM indications in July 2025. This regulatory milestone is a harbinger of future competition once full exclusivity periods lapse. Other key players such as Cipla Limited, Sun Pharmaceutical Industries Ltd, Aurobindo Pharma Limited, Lupin Limited, and Glenmark Pharmaceuticals are listed as active in the generic space, signaling a crowded field ready to capture volume upon patent expiry.
Beyond India, manufacturers like Polpharma in Poland and Senova Technology Co., Ltd. and Sinoway Industrial Co., Ltd. in China represent the globalized nature of API production. The diversity of these players means that supply chain resilience is possible, but quality consistency becomes a paramount concern. Our report profiles these companies to assess their capacity, compliance history, and potential threat level to existing market incumbents.
Regulatory and Reimbursement Dynamics
No strategic assessment of the ibrutinib market is complete without addressing the regulatory and reimbursement environment, which acts as both a gatekeeper and a price setter. One of the most significant developments for the US market is the impact of the Inflation Reduction Act. Under this legislation, the negotiated Medicare Part D maximum fair price for a 30-day supply of ibrutinib is set to be 9,319 USD starting January 2026. This represents a substantial reduction from the 2023 list price of 14,934 USD, marking a 38 percent decrease. This policy shift will inevitably compress margins for branded manufacturers and alter the economic calculus for generic entrants aiming to undercut the negotiated price.
Worldwide Imbruvica Market
Patent cliffs and exclusivity periods further complicate the timeline for market entry. In the U.S., the composition of matter patent covering ibrutinib is expected to expire in 2027, with pediatric regulatory exclusivity extending until May 2028. However, additional patents suggest no generic entry is expected prior to March 30, 2032. This long exclusivity window provides a buffer for branded owners but creates a waiting game for generic manufacturers. In contrast, the situation in China differs markedly. The compound patent for ibrutinib expires at the end of 2026, with multiple local generics already approved by companies such as Simcere, Qilu, and Huadong Medicine. This regional divergence requires multinational strategies to be highly localized, as the competitive intensity in China will likely outpace that in the US during the 2026-2027 period.
Regulatory withdrawals also shape the indication landscape. In April 2023, there was a voluntary withdrawal of U.S. accelerated approvals for IMBRUVICA in mantle cell lymphoma (after prior therapy) and marginal zone lymphoma indications following confirmatory trial results. Such shifts reduce the addressable market size for specific indications and require companies to recalibrate their sales forecasts. Additionally, label expansions, such as the U.S. FDA approval in February 2024 for the IMBRUVICA oral suspension formulation for adult patients, open new avenues for patient access and adherence, potentially offsetting volume losses in other areas.
Strategic Implications for 2026 Decision Makers
For enterprise leaders, the convergence of these factors demands a proactive rather than reactive posture. The 3.88 percent CAGR suggests stability, but the regulatory pressures indicate margin compression. Companies must decide whether to compete on volume, differentiation, or supply chain efficiency. For API manufacturers, the variance in pricing across regions like India and Russia offers opportunities for export optimization, but reliance on single-source regions introduces risk. For branded companies, the focus must remain on clinical differentiation and formulation innovation to justify pricing in the face of reimbursement cuts.
The competitive landscape is bifurcated. While the top players consolidate their position through clinical data and formulation updates, a large cohort of generic manufacturers in India and China is positioning for the eventual expiry of key protections. The tentative approval by Zydus and the early generic approvals in China suggest that the pressure will build incrementally rather than all at once. Monitoring these regulatory filings is essential for predicting market share erosion before it happens.
Our full report provides the segmented data necessary to quantify these risks. It breaks down the revenue contribution by region, allowing strategists to identify which markets are over-indexed on growth or decline. It details the split by purity and application, revealing which specific indications are driving demand and which purity grades are commanding premium pricing. This level of detail is crucial for product planning and resource allocation.
Decision makers should use this intelligence to stress-test their 2026 budgets. The reduction in Medicare pricing will impact overall market revenue realization in the US, the largest region by value. Meanwhile, the early patent expiry in China will create a price war environment that could affect global pricing benchmarks. Supply chain managers must verify the compliance status of their API suppliers, particularly those in regions with varying regulatory oversight, to prevent Quality Assurance disruptions that could halt production.
In conclusion, the Pharma Grade Ibrutinib Market is at a inflection point where historical growth meets future constraint. The data indicates a market that will continue to expand in absolute terms but faces significant headwinds in pricing and exclusivity. Success in this environment requires a granular understanding of the competitive moves, regulatory timelines, and supply chain realities. This article serves as an introduction to the depth of analysis available in our Worldwide Pharma Grade Ibrutinib Market study. We invite stakeholders to access the full repository for the specific segmentation data, company profiling, and forecast models that will underpin robust strategic planning for the coming years.
For detailed analysis of this topic, please visit the official page: Worldwide Pharma Grade Ibrutinib Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Environmentally Friendly Gas Insulated Switchgear Market Hits $2.85B in 2025, Poised for 8.15% CAGR Through 2032
By pmarketresearch, 2026-09-16
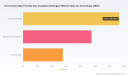
Navigating the Green Transition: Strategic Insights into the Worldwide Environmentally Friendly Gas Insulated Switchgear Market
The global power transmission and distribution sector is undergoing a structural transformation driven by environmental mandates, technological innovation, and the urgent need for grid resilience. At the heart of this shift lies the Environmentally Friendly Gas Insulated Switchgear (GIS) market, a critical segment where engineering precision meets regulatory compliance. As utilities and transmission operators worldwide face mounting pressure to decarbonize their infrastructure, the choice of insulation technology has evolved from a technical specification to a strategic imperative.
PW Consulting's latest comprehensive study, the Worldwide Environmentally Friendly Gas Insulated Switchgear Market report, offers a definitive roadmap for stakeholders navigating this complex landscape. This article serves as an executive preview of the research, highlighting the macro-economic trajectories, competitive dynamics, and regulatory forces shaping the industry through 2032. For decision-makers planning capital allocation in 2026 and beyond, this intelligence is not merely informational—it is foundational to risk mitigation and growth strategy.
Market Trajectory: From Recovery to Sustained Expansion
The market for environmentally friendly GIS has demonstrated remarkable resilience and growth momentum over the past five years. Following a baseline valuation in 2020, the sector accelerated through 2025, reflecting the compounding effects of grid modernization projects and early adoption of SF6-free technologies. Our analysis indicates that the total market revenue reached approximately 2,850 Million USD in the base year of 2025.
Looking forward, the growth curve steepens. The forecast period from 2026 to 2032 projects a Compound Annual Growth Rate (CAGR) of 8.15%. By 2032, the market is expected to approach a valuation near 4,931.68 Million USD. This trajectory underscores a critical inflection point: environmentally friendly GIS is moving from niche pilot projects to mainstream deployment. For utilities, this means the window for transitional pricing is closing; for equipment manufacturers, it signals the need to scale production capabilities and secure supply chains for alternative insulating gases.
The growth is not uniform across all voltage levels or technologies. Medium voltage applications continue to drive significant volume, particularly in distribution networks where regulatory bans on SF6 are tightening first. High voltage segments, while historically slower to adopt due to technical challenges, are seeing breakthroughs driven by major transmission upgrades in Europe and Asia. The technology mix is equally diverse, with vacuum technology, gas mixtures, and solid insulation all competing for market share depending on regional preferences and voltage requirements.
Regulatory Pressures as Market Catalysts
No analysis of this market is complete without addressing the regulatory environment, which has become the primary driver of demand. The European Union's F-Gas Regulation (EU) 2024/573 stands as a landmark policy, banning SF6 in new medium voltage switchgear below 52.5 kV from 2026. Furthermore, it limits SF6 concentration to 500 ppm in existing installations, effectively forcing a maintenance and replacement cycle for older assets.
Worldwide Environmentally Friendly Gas Insulated Switchgear Market
Across the Atlantic, the United States EPA finalized the HFC phasedown under the AIM Act, targeting an 85% reduction by 2036. While this primarily targets HFCs, the ripple effects influence the availability and cost of alternative gases used in GIS, such as fluoronitriles. For instance, 3M Novec 4710, a key component for g3 GIS technology, has seen bulk industrial pricing fluctuate between 150 and 200 USD per kg. This cost structure creates a premium for eco-friendly units, estimated at 15-25% higher than traditional SF6 equivalents, according to CIGRE Technical Brochure 802.
However, cost barriers are being offset by incentives. EU Horizon Europe has allocated 50 Million EUR for SF6-free grid technology pilots, including GIS projects, through 2027. These subsidies are crucial for de-risking early adoption and encouraging utilities to integrate new technologies into national grid connection projects. For strategic planners, understanding the interplay between these regulations and subsidy mechanisms is essential for project economics modeling.
Competitive Landscape: Leaders Defining the Standard
The competitive environment is characterized by high concentration, with the top three players holding approximately 48.5% of the market share, and the top five controlling 68.2%. This consolidation indicates a mature market where scale, R&D capability, and established utility relationships are significant moats.
GE Vernova has positioned itself as a leader in high-voltage applications, leveraging its g3 gas insulated switchgear which uses a 3M Novec 4710 and CO2 mixture as an SF6-free alternative for ratings up to 550 kV. A pivotal moment occurred in March 2025 when SP Energy Networks commissioned the UK's largest 420 kV g3 GIS at Eccles substation, marking a significant validation of the technology for transmission networks.
Siemens Energy continues to expand its Blue GIS portfolio, utilizing Clean Air insulation (fluorine-free synthetic air) for voltages up to 170 kV. In February 2025, TenneT awarded Siemens a major order for Blue GIS installation in a Dutch grid connection project, reinforcing the technology's credibility in European transmission upgrades.
Hitachi Energy provides a robust EconiQ SF6-free GIS lineup, including the ELK-04 with AirPlus technology (a fluoroketone mixture) for 72.5-420 kV ratings. In January 2025, their SF6-free EconiQ GIS was connected to the Italian Terna grid for a 132 kV substation upgrade, demonstrating successful commercial deployment in complex grid environments.
ABB maintains its presence through the EconiQ brand, developing eco-efficient GIS under AirPlus gas mixture for medium and high-voltage switchgear up to 170 kV. In December 2024, ABB released an updated EconiQ GIS catalog with certified AirPlus modules for 145 kV applications, signaling ongoing product refinement.
Regional players are also making strategic moves. Schneider Electric supplies SF6-free RM6 and GMA gas-insulated switchgear using vacuum and solid insulation for MV distribution up to 24 kV. Mitsubishi Electric produces GIS with natural origin gas (CO2-based) alternatives for high-voltage transmission, while Toshiba Energy Systems & Solutions offers SF6-free GIS using vacuum circuit breakers and eco-friendly gases for substation applications up to 72.5 kV.
Strategic Implications for 2026 Decision-Making
For enterprises operating in this space, the data points to several urgent strategic considerations. First, supply chain security for alternative insulating gases is paramount. With reliance on specific fluoronitriles and synthetic air technologies, any disruption in raw material supply can impact project timelines and cost structures. Second, the premium pricing of eco-friendly units means that value engineering and total cost of ownership (TCO) analysis must account for regulatory compliance costs and potential carbon pricing mechanisms.
Third, the regional divergence in adoption rates requires tailored go-to-market strategies. While Europe leads in regulatory push, Asia Pacific and North America show strong growth driven by grid reliability and modernization mandates. Understanding the specific segmentation splits by region and voltage is critical for optimizing manufacturing footprints and sales territories. Our full report provides detailed breakdowns of these regional valuations without revealing sensitive proportionate data here that could compromise competitive advantage.
Finally, the high market concentration suggests that partnerships or acquisitions may be necessary for smaller players to remain viable. The top five firms are not just selling equipment; they are selling compliance assurance and long-term service agreements that include gas management and recycling.
Metal-Clad Switchgear Market
Report Overview: Content and Operational Depth
The PW Consulting Worldwide Environmentally Friendly Gas Insulated Switchgear Market report is designed to be an operational tool, not just a high-level summary. It contains detailed segmentation analysis across By Region, By Voltage, and By Technology. Readers will find granular data on market size trajectories for each segment, allowing for precise demand forecasting.
The report includes a comprehensive competitive profiling section, examining the strategic positioning, product portfolios, and recent developments of key companies. It analyzes the historical data from 2020 to 2025 to establish growth baselines and uses this to validate the 2026-2032 forecast models. Additionally, the study delves into market dynamics, exploring drivers, restraints, opportunities, and challenges with specific attention to regulatory timelines and raw material cost trends.
Stakeholders will also find analysis on market concentration levels, helping to assess competitive intensity and barrier to entry. The research integrates industry context noise, such as subsidy programs and component cost premiums, into a cohesive narrative that explains why the market is moving at its current pace.
Accessing Complete Intelligence
The macro trends and competitive movements outlined above represent only the surface of the available intelligence. To make informed investment or procurement decisions, executives require access to the full dataset, including specific regional revenue valuations, exact voltage segment splits, and detailed technology adoption curves.
Unlocking this critical intelligence ensures that your organization stays ahead of regulatory curves and competitor moves. We invite you to visit the source webpage to download the complete Worldwide Environmentally Friendly Gas Insulated Switchgear Market research. There, you will find the comprehensive data tables, strategic recommendations, and the detailed segmentation splits necessary to build a robust 2026 strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Environmentally Friendly Gas Insulated Switchgear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Handheld Medical Equipment Market to Reach USD 101,721M by 2032 at 8.3% CAGR
By pmarketresearch, 2026-09-16
Strategic Imperative: Navigating the 2026 Handheld Medical Equipment Market Landscape
The global landscape of healthcare delivery is undergoing a profound transformation, driven by an urgent demand for portability, point-of-care accessibility, and intelligent diagnostic capabilities. As we move through 2026, the handheld medical equipment sector stands at the forefront of this shift, representing not merely a product category but a critical vector for strategic growth across the life sciences and medical technology industries. PW Consulting's latest Worldwide Handheld Medical Equipment Market study offers a comprehensive lens into this dynamic environment, providing enterprise leaders with the actionable intelligence required to navigate complex supply chains, regulatory frameworks, and competitive pressures.
For C-suite executives, investors, and product strategists, the decisions made in 2026 will define market positioning for the remainder of the decade. The sector is characterized by rapid technological convergence, where traditional medical hardware integrates seamlessly with artificial intelligence, wireless connectivity, and consumer-grade usability. Understanding the magnitude of this shift requires more than surface-level observation; it demands a rigorous analysis of market trajectories, segmentation nuances, and the evolving tactics of key incumbents. This introduction outlines the strategic value embedded within our full research report, highlighting why deep-dive intelligence is indispensable for capitalizing on the opportunities emerging in this high-growth segment.
Market Trajectory and Financial Scale
The financial scale of the handheld medical equipment market underscores its significance as a core component of the broader medical device ecosystem. Based on rigorous analysis conducted by our research team, the market has demonstrated robust expansion over the historical period from 2020 to 2025, culminating in a substantial valuation in the base year of 2025. Our projections extend through 2032, offering a long-term view essential for capital allocation and R&D planning.
Handheld Tester Market
The market momentum is quantified by a Compound Annual Growth Rate (CAGR) that reflects sustained demand across diverse clinical and consumer applications. This growth trajectory is not linear but is influenced by accelerating adoption rates in emerging healthcare settings, regulatory approvals that open new revenue streams, and the continuous innovation cycles of leading manufacturers. The revenue figures, denominated in USD and measured in millions, illustrate a sector that is scaling efficiently while managing the complexities of global distribution.
By examining the historical data alongside forward-looking estimates, stakeholders can identify inflection points where investment in capacity or strategic partnerships yields the highest return. The forecast period from 2026 to 2032 suggests a continued upward trend, with market value expanding significantly by the end of the forecast window. Such data is critical for modeling total addressable market (TAM) scenarios and assessing the viability of new product launches against the backdrop of overall sector expansion. However, the aggregate numbers are only the starting point; the true strategic insight lies in understanding how these revenues are distributed across types, applications, and regions, which our full report dissects with precision.
Segmentation Dynamics and Growth Vectors
The handheld medical equipment market is not a monolith. It is composed of distinct segments that behave differently under varying economic and clinical pressures. A superficial view of the market misses the nuanced drivers that determine success in specific niches. Our analysis categorizes the market by type, application, and region, revealing where the highest intensity of activity and value creation is occurring.
Within the type segmentation, the market spans monitoring devices, diagnostic and imaging devices, and therapeutic devices. Each category faces unique technological hurdles and regulatory pathways. Monitoring devices, for instance, are seeing heightened interest due to the proliferation of remote patient monitoring initiatives, while diagnostic and imaging devices are benefiting from advancements in miniaturization and AI-powered image analysis. Therapeutic devices represent a specialized but vital segment, often requiring higher levels of clinical validation and integration with surgical workflows.
Application-wise, the market serves hospital-based diagnostics, remote patient monitoring, and emergency and trauma care. The demand for hospital-based diagnostics remains a steady anchor, driven by the need for rapid, bedside decision-making. Remote patient monitoring, however, is reshaping the volume dynamics, shifting care from institutional settings to homes and community clinics. This shift is particularly relevant for chronic disease management and post-acute care, where handheld technologies enable continuous data flow without compromising patient comfort. Emergency and trauma care applications demand ruggedness, speed, and reliability, creating a distinct set of requirements for manufacturers operating in this space.
Regional segmentation further complicates the picture. Demand patterns vary significantly based on healthcare infrastructure maturity, reimbursement policies, and local manufacturing capabilities. Some regions represent mature markets with high saturation and intense competition, while others offer greenfield opportunities driven by healthcare expansion and increasing access to medical technology. Our report provides a detailed geographic breakdown that allows strategists to tailor their market entry or expansion plans according to local realities, avoiding the pitfalls of applying a one-size-fits-all approach. Specific revenue allocations and percentage splits for each region and segment are detailed in the full report, enabling precise benchmarking and target setting.
Competitive Landscape and Strategic Positioning
The competitive environment in the handheld medical equipment market is defined by a mix of established multinational giants and agile innovators disrupting traditional paradigms. Understanding the positioning, capabilities, and recent moves of these players is essential for any company seeking to defend its market share or capture new ground. Our report profiles key companies that collectively shape the industry's direction, analyzing their product portfolios, strategic focus, and recent developments.
Major players such as Koninklijke Philips N.V., GE HealthCare, Medtronic plc, Abbott Laboratories, and Siemens Healthineers command significant influence through their extensive portfolios and global reach. Philips offers handheld and portable ultrasound systems, patient monitoring devices, and point-of-care diagnostic equipment. GE HealthCare provides handheld ultrasound devices and portable patient monitoring systems focused on diagnostic accessibility. Medtronic supplies handheld devices including pulse oximeters, ECG monitors, and surgical navigation tools. Abbott Laboratories delivers portable diagnostic and monitoring solutions, including handheld glucose monitoring systems and cardiac rhythm management devices. Siemens Healthineers contributes with portable ultrasound and point-of-care diagnostic imaging equipment. These incumbents leverage scale, brand trust, and integrated ecosystem strategies to maintain strong positions.
Simultaneously, specialized and innovative firms are carving out niche dominance with focused technologies. Omron Healthcare specializes in handheld and portable blood pressure monitors, nebulizers, and thermometers. Butterfly Network focuses exclusively on smartphone-connected handheld ultrasound devices for whole-body point-of-care imaging. Stryker Corporation develops handheld robotic systems and portable surgical tools. Mindray Medical International produces wireless handheld ultrasound systems and portable patient monitoring equipment. Clarius Mobile Health specializes in wireless handheld ultrasound scanners for point-of-care applications. AliveCor offers Kardia series handheld ECG devices with AI-powered analysis. These companies often drive innovation in usability, cost reduction, and specific clinical workflows, challenging established players to adapt or risk losing relevance in high-growth sub-segments.
Market concentration metrics indicate that while the top players hold substantial shares, there is room for disruption and consolidation. The competitive intensity varies by segment; for example, the handheld ultrasound space is highly contested, while other therapeutic or monitoring niches may have different concentration dynamics. Our report includes a detailed competitive analysis that maps these dynamics, helping companies identify white spaces, assess competitive threats, and formulate differentiation strategies. The full report provides granular insights into market shares, strategic partnerships, and technology roadmaps that are not visible through public announcements alone.
Regulatory and Technology Dynamics
The regulatory environment remains a critical determinant of market access and product viability. Recent developments highlight the ongoing importance of regulatory clearance in shaping the product landscape. Throughout 2025 and early 2026, multiple companies have secured FDA 510(k) clearances for novel handheld devices, signaling an active pipeline of innovations entering the market.
Notable clearances include Swift Medical's FDA 510(k) clearance in March 2026 for the Swift Ray spectral imaging device, a handheld wound assessment tool combining spectral imaging with AI. AliveCor received FDA clearance in January 2026 for the next-generation KAI 12L AI powering the Kardia 12L handheld 12-lead ECG system, adding five new cardiac determinations. Guilin Woodpecker Medical Instrument Co., Ltd. obtained FDA 510(k) clearance in September 2025 for Ai Ray series super capacitor-operated portable handheld dental X-ray devices. Stryker received FDA 510(k) clearance in September 2025 for RPS Primary TKA Software and handheld robotic saw components in the Robotic Power System for knee arthroplasty. AI Optics gained FDA 510(k) clearance in January 2026 for the Sentinel Camera, a portable handheld retinal imaging system for non-dilated eye screening.
These events underscore the regulatory rigor required for handheld devices, whether they involve imaging, diagnostics, or robotics. Handheld medical devices such as dental X-ray units, ECG systems, and spectral imaging tools continue to require FDA 510(k) clearance demonstrating substantial equivalence to predicate devices under general controls including IEC 60601 safety standards. Portable and handheld X-ray equipment must comply with specific radiation protection standards including IEC 60601-1-3 and IEC 61223-3-4 for imaging performance and safety in diagnostic use. Handheld robotic surgical systems like Stryker RPS require FDA clearance under 21 CFR 882.4560 as stereotaxic instruments with camera-guided boundary control for intraoperative resection planning. Compliance with these standards is non-negotiable and influences product design, manufacturing processes, and time-to-market.
Technological dynamics are equally pivotal. Hospital adoption of handheld and portable devices is driven by demand for point-of-care diagnostics in emergency, ambulatory, and remote settings, supported by integration with AI for improved workflow efficiency. The convergence of hardware miniaturization, wireless connectivity, and AI algorithms is enabling capabilities that were previously confined to larger, stationary systems. AI-powered analysis, for instance, is enhancing the diagnostic utility of handheld ECGs and imaging devices, reducing interpretation burden and improving accuracy. Manufacturers that effectively integrate these technologies into user-friendly, clinically validated solutions are poised to capture significant value. Our report analyzes these technology trends in depth, linking them to market demand and competitive responses.
Strategic Implications for 2026 and Beyond
The insights contained in our Worldwide Handheld Medical Equipment Market study are designed to inform critical strategic decisions in 2026. Whether the objective is to launch a new product, expand into a new geography, optimize a supply chain, or assess acquisition targets, the data and analysis provided serve as a foundational resource. The market's growth trajectory, segmentation patterns, and competitive dynamics all point to a landscape where informed agility is a competitive advantage.
For product developers, understanding the specific requirements of different applications and regions is vital for designing devices that meet clinical needs and regulatory standards. For commercial teams, the segmentation data helps prioritize sales efforts and marketing investments in the most promising areas. For finance and strategy leaders, the market size and CAGR projections support valuation models, budgeting, and long-term planning. The competitive profiles and recent developments offer context for anticipating rival moves and identifying partnership opportunities.
Furthermore, the regulatory and technology trends highlight the need for proactive compliance management and innovation investment. Companies must stay ahead of evolving standards and leverage emerging technologies to differentiate their offerings. The report's comprehensive coverage ensures that stakeholders have a holistic view of the factors influencing market outcomes, reducing uncertainty and enabling more confident decision-making.
Unlock the Full Intelligence
While this overview provides a glimpse into the scale, structure, and dynamics of the handheld medical equipment market, the full report contains the detailed data, granular segmentation analysis, comprehensive company profiles, and actionable recommendations necessary for executing a winning strategy. The macro trends and competitive themes discussed here are merely the entry point to a rich repository of market intelligence.
PW Consulting's Worldwide Handheld Medical Equipment Market report is the definitive resource for organizations seeking to navigate this complex and rapidly evolving sector. The report delivers specific revenue figures, percentage splits, regional breakdowns, and deep-dive analyses that empower stakeholders to move from general awareness to precise action. To access the complete dataset, detailed segmentation splits, full competitor profiles, and strategic insights that will drive your 2026 decisions, we invite you to explore the full report. Discover the depth of analysis that can transform your understanding of the market and position your organization for sustained success in the handheld medical equipment landscape.
Worldwide Handheld Medical Equipment Market
For detailed analysis of this topic, please visit the official page: Worldwide Handheld Medical Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Global Memory Packaging Market to Reach $74.38B by 2032 at 10.53% CAGR
By pmarketresearch, 2026-09-16
Navigating the Next Wave: Why the Worldwide Memory Packaging Market Report Is Essential for 2026 Strategic Planning
The Capacity Crunch and the Strategic Imperative for Precision Intelligence
The global memory packaging industry stands at a critical inflection point. As semiconductor architectures grow increasingly complex and demand for high-performance computing, artificial intelligence workloads, and high-bandwidth memory accelerates, the packaging layer has evolved from a commoditized backend process into a decisive competitive differentiator. For executives navigating 2026, understanding the precise contours of this market is no longer optional. PW Consulting's latest Worldwide Memory Packaging Market research delivers a comprehensive, forward-looking intelligence framework designed specifically to inform capacity planning, supply chain positioning, and technology roadmapping.
Over the historical window from 2020 through 2025, the worldwide memory packaging market expanded from approximately 24.15 billion USD to over 36.90 billion USD. This growth trajectory reflects sustained capital allocation, technology transitions, and shifting demand patterns across enterprise, consumer, and high-performance computing segments. Looking ahead to the 2026-2032 forecast period, the market is projected to maintain a compound annual growth rate of 10.53 percent, climbing toward a 74.38 billion USD valuation by the close of the decade. These macroeconomic indicators signal a resilient, high-growth environment, but they also mask underlying segment divergence, regional capacity constraints, and technology migration dynamics that will dictate winners and losers in the years ahead.
The strategic urgency stems from a confluence of operational pressures. In early 2026, leading memory packaging and testing companies announced price adjustments of up to 30 percent, driven by sustained tight supply conditions for DRAM and NAND packaging services. Simultaneously, design wins and outsourcing ramps for advanced memory architectures are reshaping how original equipment manufacturers allocate capacity. Major players are increasingly relying on outsourced semiconductor assembly and test partners to scale production without bottlenecking internal manufacturing lines. This transition amplifies the importance of understanding which regions, packaging technologies, and memory types are driving growth, and which OSAT ecosystems are best positioned to absorb surging demand.
What the Report Delivers: Operational Intelligence for Executive Decision-Making
This Worldwide Memory Packaging Market study is structured to translate high-level market momentum into actionable intelligence. Rather than offering static snapshots, the research provides a dynamic framework that executives can deploy across multiple strategic functions: capacity planning, vendor selection, technology investment, geographic expansion, and competitive positioning. The following components define the operational value of the report.
Worldwide Memory Packaging Market
The analysis begins with a rigorous historical reconstruction spanning 2020 through 2025, establishing a baseline that accounts for cyclical semiconductor demand, supply chain disruptions, and technology transitions. From that foundation, the report extends into a detailed 2026-2032 forecast, providing granular projections that capture how shifts in memory architecture, advanced packaging adoption, and regional capacity utilization will reshape the market landscape. Every projection is anchored to observable supply-side and demand-side indicators, ensuring that strategic planners can validate assumptions against real-world operational signals.
- Historical revenue reconstruction from 2020 to 2025, contextualizing past cycles and identifying inflection points that inform forward-looking assumptions
- Five-year forecast projections from 2026 through 2032, capturing steady-state growth dynamics alongside technology and capacity transition effects
- Technology segmentation analysis covering traditional wire bonding, flip-chip architectures, TSV and 3D stacking, and fan-out and WLCSP approaches, with emphasis on adoption trajectories and value migration
- Memory type analysis examining DRAM, NAND flash, and emerging memory categories, highlighting how workload trends and product roadmaps influence packaging requirements
- Regional capacity and demand mapping that identifies where manufacturing concentration, supply resilience, and market growth intersect
- Competitive landscape profiling of leading OSAT operators, technology differentiators, and pricing strategies shaping procurement and partnership decisions
- Policy and regulatory monitoring that tracks export controls, tariff implementations, critical material licensing, and industry association advocacy efforts affecting supply chain design
Industry Dynamics Shaping the 2026 Landscape
Modern memory packaging strategy cannot be separated from the broader operating environment. Three structural forces are redefining how companies plan, invest, and compete. The first is supply-side tightness and pricing volatility. Throughout early 2026, multiple packaging and testing providers adjusted pricing upward in response to constrained DRAM and NAND packaging capacity. These adjustments reflect not merely cyclical tightness, but structural shifts in demand concentration, qualification lead times, and the capital intensity of advanced packaging lines. For procurement leaders and supply chain planners, the implication is clear: historical price benchmarks no longer apply, and multi-source visibility becomes a strategic asset.
The second force is technology migration and advanced packaging acceleration. As workloads in artificial intelligence, high-performance computing, and cloud infrastructure push memory performance boundaries, packaging architectures are evolving rapidly. Traditional wire bonding continues to serve established product families, but value growth increasingly concentrates in flip-chip configurations, TSV-enabled 3D stacking, and fan-out or WLCSP formats that support smaller form factors and improved electrical characteristics. The report dissects how these technology pathways are gaining traction, where capacity bottlenecks are likely to emerge, and which memory types are driving the most significant architectural shifts.
The third force is geopolitical and regulatory complexity. Recent policy developments have introduced new dimensions of risk and opportunity. The U.S. government has implemented tariff measures on certain advanced computing chips while maintaining export controls affecting advanced semiconductors, high-bandwidth memory, and DRAM. These controls intersect with licensing requirements that affect specific facilities and supply routes, particularly in China. At the same time, upstream material dynamics are intensifying, with export controls and licensing frameworks on critical minerals creating ripple effects through packaging material supply chains. Industry associations are advocating for plurilateral trade frameworks and critical mineral agreements, recognizing that supply chain resilience will increasingly depend on diversified sourcing and coordinated policy engagement.
Beyond these macro forces, recent developments provide concrete signals of how the market is evolving in real time. A major materials engineering company announced a long-term research and development partnership focused on advancing packaging innovations for next-generation DRAM and high-bandwidth memory, signaling deep investment in technology co-optimization. At the same time, outsourcing momentum continues to reshape capacity flows. A significant memory manufacturer's DDR5 outsourcing ramp is influencing packaging trajectories through 2026, with increased reliance on external partners for memory packaging capacity. These developments illustrate how collaboration, outsourcing, and capacity reallocation are becoming central features of the industry's operating model.
Competitive Landscape: Where Capability Meets Scale
The memory packaging market is characterized by a concentrated yet dynamic competitive field. The industry exhibits meaningful consolidation, with a small group of leading operators commanding a substantial share of total market revenue. This concentration reflects the scale economics of advanced packaging lines, the strategic importance of long-term customer relationships, and the technical qualification cycles that raise barriers to entry for new participants. Yet within this concentrated structure, differentiation remains sharp, with capabilities spanning testing, advanced packaging, high-volume memory module assembly, and specialized process expertise.
Leading operators such as ASE, Amkor, Powertech Technology, and ChipMOS have built comprehensive ecosystems serving DRAM, NAND, and advanced memory formats. Their positioning reflects decades of process refinement, capacity expansion, and close alignment with memory manufacturer roadmaps. Other significant players, including Hana Micron, Lingsen Precision Industries, Formosa Advanced Technologies, and Tianshui Huatian Technology, contribute specialized packaging and semiconductor assembly capabilities that support regional demand and niche product families. In parallel, large-scale OSAT operators such as JCET, King Yuan Electronics, TongFu Microelectronics, and STATS ChipPAC continue to expand their memory packaging portfolios, with some leveraging decades of experience in high-volume NAND and DRAM production for leading OEMs.
Regional distribution of capabilities further shapes competitive dynamics. Asia Pacific dominates total market value, reflecting the concentration of memory manufacturing, packaging infrastructure, and downstream electronics demand. North America, Europe, and the rest of the world represent meaningful but comparatively smaller shares, each influenced by distinct technology demand patterns, trade flows, and local capacity constraints. For companies evaluating partnerships, outsourcing strategies, or geographic expansion, understanding this structural distribution is essential. The report maps these relationships in detail, enabling readers to assess where capacity is available, where risk is concentrated, and how competitive intensity may shift as demand evolves.
Why This Research Matters for 2026 Decision-Making
In a market defined by rapid technology migration, pricing volatility, and heightened geopolitical sensitivity, broad market narratives are insufficient. Strategic leaders need intelligence that connects top-line growth projections to operational reality. This report is designed to do exactly that. It enables memory manufacturers to evaluate outsourcing partners and capacity expansion pathways. It supports OSAT operators in prioritizing technology investments, pricing strategies, and regional footprint decisions. It equips semiconductor equipment and materials suppliers with visibility into packaging adoption trends that influence demand for advanced process technologies. It helps investors and corporate development teams assess competitive positioning, consolidation dynamics, and long-term value migration across technology and geographic segments.
The most critical value lies in precision. Aggregate growth figures indicate a market moving decisively upward, but the real strategic questions are more specific. Which packaging technologies will absorb the majority of new investment? Where will capacity tightness translate into pricing power, and where will excess capacity create downward pressure? How will export controls, tariffs, and critical material licensing reshape sourcing strategies across memory types and end markets? Which competitive relationships will intensify, and which will create new partnership opportunities? These are the questions that determine whether a strategy is reactive or strategically ahead of the curve.
Advanced Packaging Market
To answer them, executives need the complete segmentation logic, historical baselines, regional breakdowns, technology adoption curves, and competitive assessments embedded in this research. The preview offered here is intended to demonstrate analytical rigor and establish a foundation of trust. It is not intended to substitute for the full intelligence framework that underpins strategic planning. Detailed segmentations, market size allocations, regional breakdowns, and company-specific assessments are intentionally reserved for the complete report, ensuring that decision-makers have access to the precision data required to act with confidence.
Access the Complete Intelligence Framework
The Worldwide Memory Packaging Market research offers more than a forecast. It provides a structured, evidence-driven lens through which to interpret technology transitions, supply dynamics, competitive positioning, and regulatory pressures affecting one of the semiconductor industry's most strategically important segments. In an environment where capacity constraints, pricing shifts, advanced packaging adoption, and policy developments are reshaping the competitive battlefield, incomplete information carries real cost.
For executives preparing for 2026 and beyond, the opportunity is to move from surface-level awareness to decision-grade intelligence. The full report delivers the detailed segmentation, historical reconstruction, five-year projections, competitive profiles, and industry dynamics analysis needed to translate market momentum into executable strategy. Explore the complete analysis, review the granular segmentation data, and equip your organization with the insight required to navigate the next phase of memory packaging growth with precision and confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Memory Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Aneurysm Coiling Revenue Hits $1,436M in 2025, Forecast 6.91% CAGR to $2,291M by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Neurovascular Frontier: The 2026 Aneurysm Coiling Market Outlook
The landscape of interventional neurology is undergoing a decisive transformation. As healthcare systems globally prioritize minimally invasive neurovascular interventions, the aneurysm coiling market stands at a critical inflection point. For executives, investors, and clinical strategists navigating this complex ecosystem, access to precise, forward-looking intelligence is not merely advantageous. It is imperative. In an environment defined by rapid technological iteration, shifting reimbursement frameworks, and an increasingly concentrated competitive landscape, strategic decisions made in 2026 will dictate market positioning through 2032. This article serves as a strategic preview of our latest market research publication, engineered to equip stakeholders with the analytical rigor required to navigate the coming growth cycle with confidence.
Worldwide Aneurysm Coiling Market
Worldwide Brain Hemorrhage Treatment Market
Market Trajectory and the Fundamentals of Sustained Growth
The macroeconomic foundation of the aneurysm coiling sector reflects a mature yet consistently expanding market. Drawing upon a comprehensive historical analysis spanning 2020 through 2025 and projecting forward across the 2026 to 2032 forecast period, our research delineates a clear trajectory of sustained revenue expansion. The global market generated approximately $1.04 billion in 2020 and has since charted a reliable upward curve, culminating in an estimated $1.44 billion in 2025. This consistent year-over-year progression underscores the structural resilience of neurovascular intervention demand.
Looking ahead, the forecast period indicates that annual revenue will surpass the $1.5 billion mark in 2026, accelerating toward a projected valuation exceeding $2.29 billion by 2032. This growth is underpinned by a compound annual growth rate of 6.91 percent, reflecting a harmonious convergence of expanding procedural volumes, technological refinement, and demographic shifts favoring early detection and intervention. It is crucial to recognize that this trajectory does not represent an organic plateau or a fleeting cycle of novelty-driven adoption. Rather, it signals a structural realignment in how health systems approach intracranial aneurysm management, with coiling increasingly positioned as a first-line therapeutic modality in appropriate clinical scenarios.
For corporate strategists, this macro backdrop provides essential context. The predictability of the revenue curve offers a reliable baseline for capacity planning, R&D allocation, and commercial pipeline sequencing. However, macroeconomic aggregates merely set the stage. The true strategic differentiators lie beneath the surface, within the nuanced segmentation architecture, competitive maneuvering, and regulatory variables that will ultimately determine which organizations capture disproportionate value in the coming years.
Deconstructing the Segmentation Architecture
The market is not a monolith. Our analysis decomposes the total revenue stream across multiple intersecting dimensions, revealing distinct value pools that demand tailored strategic responses. By examining product differentiation, regional deployment patterns, and end-user institutional pathways, the research maps out how revenue is distributed across the ecosystem and identifies the operational levers that most directly influence commercial performance.
Within the product landscape, the analysis highlights the continued dominance of established filtration and mechanical delivery architectures alongside the measured emergence of bioactive and coated variants. The market profile indicates a clear bifurcation in value contribution, where primary embolization platforms anchor the majority of total revenue, while specialized adjunctive and advanced-material coils represent a focused but strategically vital growth vector. Understanding the precise valuation and volume trajectory of each product category enables manufacturers to prioritize engineering roadmaps, clinical evidence generation, and pricing architectures with surgical precision.
Geographically, the revenue distribution reflects a healthcare ecosystem in transition. Established markets with mature neurovascular infrastructure demonstrate robust, stable demand profiles, supported by high procedural volumes and entrenched screening pathways. Concurrently, emerging regional markets are exhibiting accelerated uptake trajectories, driven by expanding interventional capabilities, growing patient awareness, and the gradual penetration of neurovascular services into previously underserved territories. The regional segmentation analysis within our report unpacks these dynamics without relying on superficial top-line figures, offering instead a granular assessment of procurement behaviors, channel structures, and localized reimbursement realities that shape market entry and scaling strategies.
The institutional adoption landscape further refines the strategic picture. Hospitals continue to function as the primary procedural and procurement anchor, driven by complex case volumes and integrated neurovascular service lines. Simultaneously, ambulatory surgical centers represent a meaningful and expanding value segment, reflecting broader healthcare trends toward outpatient procedural migration and cost-optimized care delivery. The interplay between these two institutional pathways influences everything from device packaging and delivery logistics to clinical training programs and surgeon preference development. Our research quantifies these institutional dynamics in a manner that directly informs channel strategy, partnership structures, and commercialization sequencing.
Competitive Landscape: Concentration, Positioning, and Strategic Maneuvering
Market structure in the aneurysm coiling sector is characterized by pronounced concentration. With three major players accounting for nearly three-quarters of total market revenue and five leading organizations collectively commanding close to 90 percent, the competitive environment operates within a tightly woven ecosystem of established incumbents, technological innovators, and regional challengers. This concentration does not imply stagnation. Rather, it creates a high-stakes arena where marginal gains in product differentiation, clinical positioning, and geographic expansion yield outsized strategic advantages.
The incumbency advantage is anchored by organizations whose product families have achieved deep clinical integration and widespread procedural familiarity. Medtronic, headquartered in Dublin, has sustained its market presence through the Axium Detachable Coils family, encompassing the Axium, Axium Prime, and Axium MicroFX platforms designed for endovascular embolization of intracranial aneurysms and related neurovascular abnormalities. Stryker, based in Kalamazoo, Michigan, competes with its Target Detachable Coils family, including the Target Tetra configuration, engineered specifically for aneurysm coiling procedures. Terumo Neuro, operating from Aliso Viejo, California, delivers a comprehensive portfolio through its Cosmos Platinum Coils, Helical Specialty Coils, and related detachable configurations for brain aneurysm treatment. Penumbra, headquartered in Alameda, markets its Neuro Embolization System with the SwiftPAC, POD400, PAC400, PC400, and Ruby Coil System architectures for aneurysm embolization. Johnson & Johnson MedTech, through its Cerenovus division in New Brunswick, provides the Spectra Family of Coils designed to address aneurysm treatment requirements from framing through finishing. These organizations collectively establish the clinical reference points against which new entrants and next-generation platforms are measured.
The competitive field, however, extends well beyond the entrenched major players. Kaneka Corporation, based in Osaka, has entered the commercial arena with the i-ED COIL for brain aneurysm embolization, achieving a notable regulatory milestone through EU Medical Device Regulation certification, which enabled commercial sales in Europe starting in late 2025. Balt Group, operating from Montmorency, France, supplies neurovascular embolization coils and devices that support intracranial aneurysm treatment within European and international clinical networks. Phenox GmbH, part of the Wallaby Medical ecosystem and headquartered in Bochum, Germany, develops embolization coils and flow modulation devices that participate in aneurysm coiling and related neurovascular procedures. MicroPort NeuroTech, headquartered in Shanghai, China, provides neurovascular coils and devices focused on aneurysm embolization, reflecting the growing technological and commercial influence of the Asia-Pacific manufacturing base. Neuravention Inc., operating out of Buffalo, New York, is advancing an advanced brain aneurysm coil technology with a regulatory submission anticipated in early 2026 and a potential commercial launch or sale targeted within the same year. This array of competitors illustrates a market where established clinical credibility must be continuously defended while new entrants exploit regulatory pathways and geographic openings to establish footholds.
Market Dynamics: Reimbursement, Regulation, and Procedural Economics
Strategic planning in the aneurysm coiling sector must account for the interplay between clinical adoption and economic architecture. Reimbursement frameworks, regulatory approvals, and institutional cost structures function as powerful forces shaping procurement decisions, procedural volume trajectories, and ultimately, revenue realization. The 2026 operating environment introduces new variables that demand proactive integration into commercial and clinical strategy.
From a physician-facing economic standpoint, reimbursement for brain aneurysm coiling procedures remains a critical consideration for procedural volume and practice sustainability. Estimates indicate that physician payment for the relevant CPT code approximates $1,045 nationally in 2026, based on approximately 19.5 work RVUs under the Medicare Fee Schedule. This reimbursement level establishes a procedural economic baseline that influences provider willingness to expand coiling service lines, invest in training, and adopt new device platforms. Simultaneously, institutional reimbursement realities shape hospital and ambulatory center purchasing behaviors. The DRG payment for ruptured aneurysm with complications was adjusted to approximately $57,259 in 2026, creating a financial context in which device selection, procedural efficiency, and complication management carry direct implications for institutional margin performance. Understanding how device characteristics, delivery systems, and clinical outcomes intersect with these reimbursement parameters is essential for manufacturers seeking to align value propositions with the economic realities of healthcare providers.
Regulatory milestones further modulate the competitive landscape. The European Union Medical Device Regulation certification achieved by Kaneka for the i-ED COIL exemplifies the type of regulatory clearance that can unlock regional commercial activity and shift competitive dynamics. As regulatory frameworks continue to evolve across jurisdictions, market participants must navigate not only product approval pathways but also post-market surveillance requirements, clinical evidence expectations, and conformity assessment obligations. These regulatory layers influence time-to-market, market access strategies, and the long-term sustainability of product portfolios. In this context, strategic agility requires continuous monitoring of regulatory calendars, anticipation of compliance shifts, and alignment of clinical evidence generation with the evidentiary thresholds demanded by regulators and payers alike.
What the Research Delivers: Actionable Intelligence for 2026 Decision-Making
The strategic value of comprehensive market research lies not in retrospective validation but in forward-looking decision support. Our Worldwide Aneurysm Coiling Market study is engineered to provide exactly that. Rather than delivering generic overviews, the report constructs an operational intelligence framework designed for use by corporate strategy teams, commercial leadership, clinical affairs groups, and investor research functions.
The report delivers a detailed segmentation analysis that moves beyond surface-level aggregates to examine how revenue, volume, and adoption patterns unfold across product categories, geographic territories, and institutional end-user pathways. This breakdown equips readers with the ability to model scenario-based forecasts, evaluate market share dynamics, and identify underserved or high-growth segments that align with organizational capabilities and strategic objectives. The segmentation architecture is presented in a manner that supports both top-down portfolio planning and bottom-up tactical execution, enabling users to translate macro trends into specific commercial priorities.
Beyond segmentation, the research provides a competitive profiling structure that examines the strategic positioning, product architectures, technological differentiation, and commercial footprints of the leading market participants. Each company profile is contextualized within broader market dynamics, allowing readers to assess competitive threats, identify potential partnership or licensing opportunities, and evaluate the strategic implications of competitor product launches, regulatory achievements, and geographic expansion initiatives. This competitive analysis is paired with a forward-looking review of recent and anticipated developments, including product introductions, regulatory submissions, and certification milestones, ensuring that readers are equipped to anticipate rather than merely react to market shifts.
The report also integrates an assessment of market dynamics that connects reimbursement structures, regulatory frameworks, and procedural economics to commercial strategy. This section is designed to help stakeholders understand how policy and payment environments influence adoption curves, purchasing decisions, and long-term revenue sustainability. By mapping these dynamics against the competitive landscape and segmentation profile, the research provides a holistic view of the forces shaping the market and the levers available to influence outcomes.
Furthermore, the study incorporates historical trend analysis that establishes a reliable baseline for interpreting current market conditions and projecting future trajectories. This historical context is essential for distinguishing cyclical fluctuations from structural transitions, enabling organizations to allocate resources with confidence and avoid strategic missteps driven by short-term noise. The forecast architecture extends through 2032, offering a multi-year planning horizon that supports capital allocation decisions, pipeline development timelines, and market entry sequencing.
Navigating the 2026 Inflection Point
The aneurysm coiling market in 2026 is defined by a combination of predictable growth, concentrated competition, evolving reimbursement parameters, and a steady stream of regulatory and product developments. For organizations operating in this space, the margin between strategic success and marginal performance will depend on the ability to interpret these forces with precision and act upon that interpretation with discipline. High-level market size figures and top-line growth rates provide essential orientation, but they do not substitute for the segment-level insight, competitive depth, and dynamic context required to make informed decisions.
Our research publication closes these information gaps. It provides the analytical structure necessary to evaluate product portfolio positioning, assess commercial viability across regions and end-user segments, anticipate competitive responses, and align internal planning with the economic and regulatory realities of the operating environment. By integrating historical performance data, forward-looking forecasts, and contemporary industry developments into a single, coherent framework, the report delivers the strategic intelligence required to navigate the 2026 to 2032 growth cycle with clarity and confidence.
For executives seeking to translate market opportunity into executable strategy, this research serves as a foundational decision-support tool. Detailed segmentation valuations, regional volume trajectories, end-user adoption pathways, competitive benchmarking matrices, and scenario-based modeling frameworks are presented within the full report to enable precise planning and targeted execution. Readers are encouraged to access the complete publication to explore these elements in full and to integrate the comprehensive dataset into their 2026 strategic planning processes.
For detailed analysis of this topic, please visit the official page: Worldwide Aneurysm Coiling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EMS Market Hits $54.3B in 2025, Poised for 13.52% CAGR Through 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Decade Ahead: Navigating the Global Power Energy Management System Market in 2026
The global energy landscape is undergoing a structural transformation that rewards precision, foresight, and decisive investment. As utilities, industrial operators, and commercial enterprises confront electrification, distributed resource integration, and grid modernization simultaneously, the power energy management system market has evolved from a supporting infrastructure category to a central strategic asset. Our newly published Worldwide Power Energy Management System Market research synthesizes historical trends, near-term trajectories, and long-term demand drivers into a single actionable intelligence framework. For executive teams planning capital allocation, technology roadmaps, and partnership strategies in 2026, this study functions as a navigational instrument for a market defined by rapid scale, regulatory recalibration, and intensifying platform competition.
The market has demonstrated sustained momentum over the past half-decade, expanding from a base of approximately 29.4 billion USD in 2020 to 54.3 billion USD in 2025. That progression reflects more than incremental growth; it signals a broadening institutional mandate for real-time monitoring, optimization, and automated control across generation, transmission, and consumption environments. Our forecast window extends through 2032, and the trajectory points toward a sustained compound annual growth rate of 13.52 percent. By 2032, the worldwide market is projected to approach 132 billion USD, driven by recurring investment cycles in grid intelligence, industrial efficiency mandates, and the acceleration of data center and electrification load profiles. The implication for decision-makers is clear: energy management is no longer a discretionary upgrade but a foundational layer of operational resilience and regulatory compliance.
This research is structured to convert macroeconomic signals into business-relevant guidance. Rather than presenting isolated figures, the analysis connects growth patterns to the operational realities that executives face when evaluating technology adoption, portfolio positioning, and regional expansion. The study establishes a baseline from 2020 through 2025, then projects forward across the 2026-2032 period, allowing leadership teams to compare historical adoption curves against forward-looking demand scenarios. By anchoring the analysis in real-world deployment logic, the report helps organizations distinguish between temporary market enthusiasm and durable structural demand.
Because the competitive landscape is both consolidated and highly differentiated, the report provides a detailed assessment of the major platforms shaping market behavior. Large multinational vendors continue to anchor the sector, and their strategic positioning reflects distinct value propositions across utility-scale grid control, industrial optimization, building operations, and integrated hardware-software services. Siemens AG remains a central reference point for comprehensive power EMS deployments, particularly where grid control, generation optimization, and renewable integration intersect. Schneider Electric SE leverages advanced power management platforms for electro-intensive facilities, utilities, and grid optimization, emphasizing operational continuity and asset-level visibility. ABB Ltd delivers real-time monitoring and consumption optimization capabilities tailored to power facilities and industrial applications, while General Electric Company and GE Vernova focus on transmission and generation asset monitoring through digital EMS platforms and grid solutions.
The industrial and demand-response segment draws additional strength from Honeywell International Inc., whose energy optimization and efficiency solutions target power and utility sectors with a strong emphasis on operational responsiveness. Eaton Corporation plc supports reliable energy distribution and optimization through branch circuit monitoring and integrated power management systems. Emerson Electric Co. contributes process-oriented EMS capabilities through control platforms designed for generation, transmission, and facility optimization, while Johnson Controls International plc maintains a strong presence in commercial and industrial power environments through energy efficiency, distributed energy resource integration, and building and power EMS solutions. Rockwell Automation Inc. aligns industrial automation with power monitoring and optimization, and Mitsubishi Electric Corporation, Yokogawa Electric Corporation, and Hitachi Energy Ltd extend the competitive field with platforms focused on efficiency, grid integration, control system functionality, and renewable integration.
These vendors do not compete in a vacuum. The research evaluates how platform breadth, software depth, hardware integration, and services capability shape buyer preferences across different end-user environments. The competitive framework is particularly important for 2026 planning, as consolidation pressure, digital service expansion, and local manufacturing investments begin to influence both pricing dynamics and deployment timelines. For example, recent corporate commitments signal how major players are preparing for sustained demand rather than reacting to short-term cycles. Schneider Electric SE, for instance, committed substantial capital toward U.S. factory upgrades and digital service expansion supporting energy management solutions, an indication that supply-chain readiness and service scalability are becoming strategic differentiators. Johnson Controls International plc reported meaningful growth in its building solutions business in North America alongside a large backlog, with performance closely tied to demand for digital energy management services.
Worldwide Power Energy Management System (EMS) Market
The report also examines the competitive fabric through the lens of market concentration. The sector exhibits meaningful but not absolute consolidation, leaving room for specialized deployments, regional service providers, and vertical-specific platforms to compete on integration quality, responsiveness, and domain expertise. This balance matters because procurement decisions increasingly depend on total cost of ownership, interoperability with existing control environments, and the ability to support evolving data and control requirements rather than on headline brand recognition alone.
One of the most decisive value drivers in this study is its treatment of market structure. The analysis partitions the landscape across region, solution type, component category, and end-user profile, giving leadership teams the granularity needed to align product strategy, sales coverage, and partnership models with where demand is actually forming. Industrial EMS continues to represent a substantial share of the overall addressable market, reflecting the scale of continuous-process operations, capacity constraints, and efficiency mandates that shape industrial procurement. Building EMS remains a major demand center as commercial and institutional operators prioritize energy performance, operational control, and integration of distributed resources. Home EMS represents a distinct and expanding segment as residential load management, consumer-facing energy visibility, and smart energy ecosystems mature.
From a component perspective, the research explains how software, hardware, and services interact to define deployment economics. Software-centric capabilities increasingly determine platform differentiation, particularly where analytics, automation, and integration with distributed energy resources are required. Hardware remains essential for measurement, control, and physical connectivity, while services support implementation, optimization, and ongoing performance management. The report does not treat these categories as siloed line items; instead, it maps how their interplay affects project scale, margin profiles, and the pace of adoption across different customer environments.
The end-user dimension further clarifies where strategic opportunities are forming. Power and energy organizations remain central users of EMS platforms as grid operators and generation providers seek greater visibility and control. Manufacturing and IT and telecom environments contribute significant demand, reflecting the pressure to manage rising load profiles and maintain operational reliability. Healthcare and residential applications provide additional growth pathways, each with distinct performance expectations, compliance considerations, and deployment patterns. By connecting these segments to operational drivers rather than abstract classifications, the study helps executives identify which customer groups present the most favorable combination of urgency, budget availability, and solution fit.
No strategic assessment of this market would be complete without examining the regulatory and structural forces that are reshaping procurement logic. In 2026, one of the most consequential developments is the update to the National Electrical Code, which relocates and revises the article governing energy management systems and introduces clearer distinctions between EMS and power control system functionality. This change supports safer power-flow-based management of distributed energy resources and alters how integrators, designers, and operators think about system scope, compatibility, and compliance. Parallel to this, the U.S. Department of Energy's virtual power plant update charts a path toward substantial aggregated distributed energy resource capacity by 2030, increasing the requirement for advanced energy management capabilities that can coordinate heterogeneous assets at scale.
Infrastructure planning is also amplifying demand. Grid operators and regional transmission organizations are responding to load growth from electrification and data centers with major transmission expansion initiatives, which in turn raise the value of advanced energy management and grid optimization tools. In parallel, national-level strategies in neighboring markets are reinforcing investment in generation and grid modernization, creating broader regional momentum for energy management capabilities. At the same time, international energy management standards continue to support optimization and efficiency improvement, aligning operational practice with decarbonization and grid modernization goals. Together, these forces create a policy and infrastructure environment in which EMS adoption is being reinforced by multiple, mutually reinforcing drivers rather than by a single regulation or technology trend.
Industrial Energy Management System (IEMS) Market
Recent project-level activity reinforces the direction of travel. Regulatory and system-operator actions are accelerating EMS modernization where mission-critical reliability is at stake. Approved upgrade initiatives intended to strengthen grid operations capabilities illustrate how operators are treating EMS not as a static utility tool but as a continuously evolving operational backbone. Such developments matter because they validate the market's transition from early-stage adoption to expanded deployment in environments where control fidelity, resilience, and interoperability are non-negotiable.
For companies planning 2026 decisions, this report translates those dynamics into strategic questions that leadership teams can act on immediately. Where should capital be directed across software, hardware, and services to maximize competitive advantage? Which customer environments offer the strongest near-term deployment potential, and which require longer maturation? How should organizations prepare for regulatory shifts that change system definitions, integration expectations, and compliance pathways? Which competitive positions are sustainable, and where might platform differentiation erode as digital services and local delivery capabilities become more important?
The study is designed to support those decisions with a comprehensive yet practical architecture. It combines market sizing with qualitative interpretation, competitive profiling with structural analysis, and regulatory context with deployment patterns. Readers can use the report to benchmark internal assumptions, pressure-test expansion plans, and identify the segments and solution attributes most likely to shape procurement behavior over the forecast horizon. Because the market is moving quickly, the research also provides a framework for monitoring the signals that matter most: load growth trajectories, distributed resource coordination requirements, platform virtualization trends, and the growing importance of services-led value creation.
This is an intelligence asset for organizations that need to move beyond generalized market narratives and make decisions with a clear view of scale, segmentation, and competitive intensity. The full report offers the detailed breakdowns, scenario-based interpretation, and company-level insights necessary to convert high-level momentum into concrete strategy. We invite executives, strategy teams, and market planners to access the complete analysis and use it as the foundation for 2026 planning across product positioning, investment prioritization, and partnership design. In a market expanding at this pace, the organizations that outperform will be those that understand not only how large the opportunity is, but where its most defensible value is being created.
For detailed analysis of this topic, please visit the official page: Worldwide Power Energy Management System (EMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Moving Table Grinding Machine Market Hits $3.15B in 2025, 4.62% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Outlook on the Worldwide Grinding Machine With Moving Table Market: Navigating 2026 and Beyond
The global manufacturing landscape is undergoing a quiet convergence of precision demands, automation mandates, and capital efficiency pressures. Within this shifting terrain, the worldwide market for grinding machines with moving tables stands as a critical enabler of high-tolerance component production. Our newly published research tracks this segment from 2020 through a ten-year forecast window ending in 2032, offering a granular, decision-ready map for executives navigating procurement, capacity planning, regional expansion, and technology investment. Grounded in 2025 as the base year, the analysis captures a mature but structurally evolving market, where incremental growth compounds into meaningful strategic advantage when paired with disciplined market intelligence.
A Decade of Measured Expansion: Market Trajectory and Structural Signals
The market has demonstrated a consistent upward trajectory across the historical review period, reflecting the steady replacement cycle of precision machining capacity and the incremental adoption of moving-table configurations that enable multi-axis handling, reduced setup changeover, and improved surface integrity. By the close of the forecast horizon, the market is projected to surpass the four-billion threshold in USD millions, a milestone that underscores both the durability of core industrial demand and the compounding effect of modernization investments. The compound annual growth rate of approximately 4.62 percent frames a market that is expanding at a pace faster than population-driven consumption but slower than speculative technology cycles, making it a textbook case of structurally supported, capex-sensitive growth.
This trajectory is not uniform in its drivers. The historical years reveal how production backlogs, supply chain recalibrations, and regional manufacturing rebalancing shaped purchasing behavior. In the forward window, the growth path is increasingly influenced by equipment lifecycle economics, labor availability, and the accelerating digitization of shop floors. Our forecast model integrates these variables to illustrate how revenue concentration, replacement demand, and technology upgrades will interact over the depreciation cycles of installed base assets. For strategic planners, the key takeaway is that growth in the period ahead will be earned through timing, configuration selection, and the ability to align machine capabilities with rising tolerances and unattended-operation expectations.
Report Architecture: Operational Intelligence for Decision Makers
The study is constructed to translate market behavior into procurement and investment decisions. It maps the competitive terrain, tracks structural shifts, and isolates the variables that determine return on equipment investment. Below is a structured overview of the analysis framework:
- Core market sizing and multi-year forecasting anchored to a 2025 baseline, with explicit linkage to replacement cycles and capacity utilization patterns
- Technology configuration evaluation that distinguishes moving-table architectures from alternative grinding setups, including throughput implications and precision pathway comparisons
- Competitive profiling of leading OEMs and their strategic positioning, product differentiation, and regional presence
- Macro and micro demand drivers, including raw material cost exposure, sustainability mandates, and Industry 4.0 adoption curves
- Strategic implications for capacity planning, after-sales service design, and distributor/manufacturer collaboration models
Each section is designed to feed directly into capital allocation discussions, RFP design, and regional entry or partnership evaluation. Rather than stopping at descriptive trends, the report isolates the decision points that determine which investments outperform over a seven-year horizon.
Gear Grinding Machine Market
Who Moves the Table: Competitive Landscape and Strategic Profiles
The competitive set in this market is defined by a blend of European precision heritage, Asian scale and speed-to-market, and regional specialists capable of serving heavy-industry and niche tolerance requirements. Market concentration data indicates that the top three players account for a meaningful but not dominant share, while the top five approach a near-majority position, signaling a landscape with strong incumbents and continuing room for targeted differentiation. This structure matters: it implies pricing discipline in mainstream configurations, yet significant latitude for technology-led differentiation in heavy-duty, high-precision, and hybrid-operation segments.
Danobat has built a notable profile around hybrid operations that combine grinding with hard turning, milling, boring, and drilling in a single setup, supported by hydrostatic bearings and sub-micron precision on large workspace envelopes. This configuration philosophy reduces part handling and accelerates complex component throughput, an increasingly valuable attribute as manufacturers seek to compress process steps. In early 2026, a precision gear manufacturer expanded its capabilities by adding a Danobat universal OD configuration, illustrating how moving-table platforms are being adopted as enabling nodes in specialized production cells.
Worldwide Grinding Machine With Moving Table Market
Herkules continues to anchor its positioning around roll grinding with traveling table and traversing saddle designs, emphasizing large-roll handling, automatic loading and unloading, and steady-rest integration. For segments where workpiece size and rotational stability define capability requirements, this architectural focus translates into durable competitive advantage. Meanwhile, the Robbi Group provides universal CNC/PLC cylindrical platforms with hydrodynamic spindles and robot integration pathways, aligning with the broader move toward flexible, programmable cells. Morara’s MH series extends this logic to external and internal cylindrical work, including heavy-duty applications such as railway axles, while HMT Machine Tools contributes horizontal spindle reciprocating table CNC surface grinding platforms designed for rigid, programmable axis control in flat and profile applications.
JTEKT Machinery brings high-production precision with configurations compatible with moving-table principles, supporting throughput-sensitive environments. In Italy, Gioria, AZ, and Grinding Technology’s Morara presence reinforce a regional strength in conventional and CNC table-moving cylindrical designs, including hydraulic and controlled variants with high payload capacities. Across southern Europe, these players demonstrate how configuration specialization and application-specific tuning create defensible niches. LGB Scop supplies surface grinding platforms with moving table configurations for industrial use, while Dowell Machine contributes rotary table surface grinders built on high-quality castings, offering vertical spindle variants adaptable to precision requirements. Kehren focuses on high-precision surface grinding with rotary tables and vertical/horizontal spindle orientation, emphasizing creep feed and profile grinding systems. UNITED GRINDING, through its MÄGERLE lineage, offers large-diameter rotary table centers with substantial load capacity, addressing heavy turbine and coupling components with hydrostatically mounted tables.
Strategically, the field is less about a single dominant playbook and more about configuration-to-application fit, service ecosystem depth, and the ability to reduce integration friction for end users. Our report profiles these players not simply to list strengths, but to surface where each is most likely to win, where substitution risk is highest, and how procurement teams can use competitive spacing to negotiate capability and service terms.
Forces Shaping the Next Cycle: Dynamics, Materials, and Manufacturing Mandates
The market’s forward movement is being shaped by overlapping forces that influence both demand timing and equipment economics. Industry 4.0 integration is steadily shifting grinding platforms from isolated workstations toward connected assets with predictive maintenance capability, optimized cycle control, and improved resource efficiency. In parallel, energy efficiency mandates and sustainability initiatives are nudging manufacturers toward designs with lower power consumption and more effective cooling architectures. On the shop floor, automation and smart factory trends, including digital twins and connected CNC systems, are accelerating fleet modernization for unattended operation and higher repeatability.
These dynamics intersect with material cost realities. Iron prices in early 2026 reached levels that directly affect the cost base of cast iron and steel structures used in machine beds and tables, while global scrap price movements across regions have influenced recycled steel supply for machine frames. For capital equipment buyers, this translates into a more variable cost environment where lead-time planning, specification choices, and service-part inventories must be managed with greater foresight. The research integrates these inputs to help manufacturers evaluate total cost of ownership rather than sticker price alone, especially when comparing moving-table configurations with alternative architectures.
Beyond cost, regulation and labor dynamics are altering the value proposition of moving-table designs. Where skilled labor availability is constrained, the appeal of configurations that reduce setup complexity and enable programmed handling increases. Where tolerance requirements tighten in aerospace, defense, medical device, and automotive applications, the precision pathway offered by stable table mechanics and controlled wheel movement becomes a competitive differentiator. The report synthesizes these signals into a demand-side narrative that explains where growth will concentrate and which buyers are most likely to accelerate replacement or expansion spending.
Where Precision Meets Volume: Application Realities and Demand Concentration
The demand base spans multiple industrial ecosystems, each with distinct tolerance requirements, batch profiles, and capital cycles. General machinery and automotive sectors represent substantial portions of end-user demand, driven by high-volume component production and recurring replacement of worn or precision-degraded surfaces. Aerospace and defense applications contribute a structurally important layer, where tighter tolerances, material complexity, and longer procurement cycles elevate the strategic value of capable grinding platforms. Medical device manufacturing, though smaller in relative scale, reflects a demand segment that prioritizes surface integrity, repeatability, and contamination-controlled processes.
These application profiles matter because they shape not only which machines are purchased, but how they are specified, serviced, and integrated into production cells. A moving table can change changeover times, part orientation flexibility, and wheel-to-workpiece engagement consistency. Our analysis examines these operational consequences without reducing them to oversimplified generalizations, allowing procurement and engineering leaders to map application requirements to configuration strengths with greater precision.
Regionally, demand is distributed across established industrial centers and emerging capacity hubs, with Asia Pacific representing the largest share of market activity, followed by Europe and North America. This distribution reflects the interplay of installed base age, local manufacturing intensity, and the pace of modernization. Because regional dynamics are heavily influenced by local labor conditions, energy costs, and supply chain structure, a single global growth figure is insufficient for operational planning. The study provides the regional context needed to interpret where investment timing is favorable, where service coverage matters most, and where local partnerships can reduce integration risk.
Translating Forecast Into Action: Strategic Implications for 2026 and Beyond
For executives planning the 2026 decision cycle, the most valuable use of this research is not simply to confirm that growth will continue, but to determine how to position for it. The forecast period to 2032 reveals a market that rewards discipline in three areas: timing, configuration selection, and ecosystem readiness.
- Timing: Replacement cycles interact with macroeconomic signals, raw material volatility, and technology adoption curves. Companies that align procurement with credible capex windows can reduce cost exposure and capture capability upgrades at optimal points in the cycle.
- Configuration selection: Moving-table architectures are not universally superior, but they offer distinct advantages in applications requiring reduced handling, improved surface consistency, and programmable axis control. Matching configuration to application profile is central to achieving the intended return on equipment investment.
- Ecosystem readiness: Automation, Industry 4.0 integration, and service coverage increasingly determine real-world performance. Buyers benefit from evaluating not only the machine but the software interfaces, maintenance model, and training path that determine uptime and repeatability.
These implications extend beyond purchasing. For manufacturers, the study informs product roadmap priorities, where hybrid capability, heavy-duty payload capacity, and energy-efficient design are most valued. For distributors and service providers, it identifies where coverage gaps create competitive openings and where regional density strengthens account retention. For investors and strategists, it clarifies where concentration remains limited and where application-specific differentiation can sustain margin resilience.
Why This Study Matters Now: The Case for Actionable Intelligence
A market growing at a steady but not spectacular pace can still generate disproportionate strategic outcomes for organizations that understand its internal structure. The difference between reacting to demand and shaping it lies in the quality of intelligence available at the point of decision. Our Worldwide Grinding Machine With Moving Table Market report is built to provide that intelligence: a forecast framework, competitive mapping, application context, and dynamic drivers that together support capital planning, vendor evaluation, and regional strategy.
To access the complete segmentation detail, regional breakdowns, competitive positioning tables, and forward modeling, request the full study through our official research portal. The source page contains the full intelligence set required to translate these strategic themes into procurement specifications, investment memos, and market-entry evaluations. In a market where configuration fit, service depth, and timing determine outcomes, complete data is not a luxury; it is the foundation of durable advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Grinding Machine With Moving Table Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: JAK Inhibitors Market to Reach $40.5B by 2032, 14.01% CAGR
By pmarketresearch, 2026-09-16
Navigating the Next Wave: Strategic Insights from the 2026 Worldwide JAK Inhibitors Market Intelligence
The Janus Kinase (JAK) inhibitor landscape is undergoing a fundamental transformation. As the therapeutic class matures beyond its initial breakthrough era, pharmaceutical executives, investors, and healthcare strategists face a complex matrix of clinical differentiation, regulatory reinterpretations, patent cliff disruptions, and shifting reimbursement architectures. Our newly released Worldwide JAK Inhibitors Market research delivers the analytical rigor required to navigate this inflection point. This publication is not merely a retrospective summary of historical sales; it is a forward-looking decision architecture designed explicitly for enterprise strategy in 2026 and beyond. By mapping the trajectory from baseline market conditions through the 2026-2032 forecast horizon, the study provides a structured lens through which stakeholders can anticipate competitive displacement, evaluate pipeline positioning, and allocate capital with precision.
The Macro Trajectory: Why 2026 Serves as a Strategic Inflection Point
Historical momentum establishes the foundation. Between 2020 and 2025, the global JAK inhibitors market expanded from approximately 7.4 billion to 16.2 billion USD, reflecting a sustained adoption curve across inflammatory, autoimmune, and hematologic indications. The forecast period extends this trajectory through 2032, with base-year positioning in 2025 and a compound annual growth rate of 14.01 percent. By mid-decade, the market is projected to cross the 17.7 billion threshold, with continued acceleration pushing toward the 40 billion mark by the close of the forecast window. These figures represent more than aggregate revenue; they signal a structural reallocation of therapeutic preference, payer budget prioritization, and clinical guideline integration.
For corporate strategy teams, the 2026 baseline is particularly consequential. It sits at the intersection of multiple simultaneous forces: the expiration of foundational patents, the widening of label expansions into pediatric and niche dermatology populations, the maturation of next-generation selective molecules, and the ongoing recalibration of safety monitoring frameworks. The 14 percent CAGR does not emerge in a vacuum. It is the product of overlapping demand drivers, supply chain adaptations, and commercialization agility. Understanding how these variables compound—and where they diverge across therapeutic categories and geographic commercial footprints—requires the granular segmentation and scenario modeling contained in the full report.
Structural Pillars of the Analysis: What the Report Delivers
The research is engineered to translate macroeconomic signals into actionable commercial intelligence. Rather than presenting static snapshots, the study employs a multi-dimensional segmentation architecture that enables clients to isolate the levers most relevant to their strategic mandate. The analytical framework is organized around three core dimensions, each designed to answer specific decision-making questions:
- Therapeutic Selectivity & Molecular Architecture: The study dissects the commercial footprint across JAK1-selective inhibitors, JAK1/JAK2 dual-target agents, and pan-JAK inhibitors. This classification is not merely biochemical; it maps directly to safety profile differentiation, prescriber confidence trajectories, formulary positioning, and patient compliance dynamics. The segmentation reveals how selectivity profiles influence market share allocation, pricing resilience, and the competitive runway for pipeline assets seeking to capture adjacent indications.
- Clinical Application & Indication Expansion: Demand is analyzed across rheumatoid arthritis, atopic dermatitis, myelofibrosis, and the combined ulcerative colitis/psoriatic arthritis spectrum. The report tracks how label expansions, real-world evidence accumulation, and guideline endorsements have reshaped utilization patterns. It further examines the commercialization implications of跨界 prescribing, off-label adoption curves, and the strategic value of indication sequencing when navigating payer segmentation and specialty pharmacy distribution networks.
- Regional Commercial Dynamics: The geographic breakdown isolates pricing architecture variability, regulatory approval cadence, market access timelines, and competitive density across major commercial territories. The report evaluates how localized reimbursement frameworks, health technology assessment (HTA) requirements, and distribution channel maturity influence revenue realization. Regional analysis is structured to help multinational teams calibrate launch sequencing, prioritize market entry investments, and anticipate the velocity of generic or biosimilar erosion in mature markets.
Beyond segmentation, the study integrates supply chain vulnerability mapping, manufacturing capacity constraints, and raw material dependency analysis, drawing on observable industry signals to highlight where operational resilience will become a competitive differentiator. The report also incorporates payer behavior modeling, formulary tier positioning, and coverage determination dynamics that directly affect prescription volume conversion. Each analytical module is paired with executive-ready visualizations, scenario sensitivity tables, and strategic implication summaries tailored for cross-functional alignment between commercial, medical affairs, market access, and corporate development teams.
Competitive Architecture: Incumbents, Expansionists, and Pipeline Challengers
The JAK inhibitor market is characterized by pronounced concentration among a core group of multinational innovators, yet the competitive environment is far from static. The research maps the strategic posture, portfolio architecture, and recent commercialization moves of the principal market participants, providing a comparative lens through which clients can benchmark positioning, identify white-space opportunities, and anticipate tactical responses.
Pfizer continues to anchor a substantial share of the legacy market through its tofacitinib franchise, leveraging a broad indication footprint across rheumatoid arthritis, psoriatic arthritis, ulcerative colitis, and ankylosing spondylitis. Recent regulatory expansions into pediatric polyarticular course juvenile idiopathic arthritis and juvenile psoriatic arthritis demonstrate a deliberate strategy to extend the product lifecycle, deepen prescriber familiarity, and capture earlier intervention pathways. Incyte maintains a differentiated position through its ruxolitinib portfolio, with therapeutic applications spanning myelofibrosis, polycythemia vera, and graft-versus-host disease. The recent topical formulation approval for nonsegmental vitiligo reflects an ongoing effort to translate systemic JAK inhibition into specialty dermatology channels, broadening the commercial addressable market beyond hematology. Eli Lilly has positioned baricitinib as a multi-indication asset, capturing autoimmune and inflammatory segments including severe alopecia areata, where pediatric label expansion signals an intent to capture unmet demand in younger patient cohorts. AbbVie has aggressively expanded its upadacitinib franchise across rheumatology, dermatology, and gastroenterology, with pediatric ulcerative colitis approval reinforcing its commitment to broad therapeutic coverage and competitive density in high-prescription-volume disease states. Gilead, operating through a strategic partnership model, continues to advance filgotinib in select markets, illustrating how collaborative commercialization structures can sustain presence in mature therapeutic categories while managing risk and resource allocation. Meanwhile, emerging players such as Conatus Pharmaceuticals, backed by Roivant Sciences, are pursuing next-generation molecular designs targeting selective IRAK4/JAK1 pathways, with clinical-stage programs directed at hematologic malignancies. This pipeline activity signals a gradual diversification of the molecular target landscape, raising the strategic question of whether future market leadership will be defined by incremental selectivity optimization or by entirely new pathway combinations.
The concentration metrics underscore the entrenched nature of the incumbent base, with the top three participants commanding a substantial share of aggregate revenue and the top five entities controlling an even larger portion of market value. High concentration does not, however, equate to static market behavior. Patent expirations, safety-signal recalibration, payer formulary re-evaluations, and pipeline-driven indication displacement are introducing dynamic competitive friction. The report dissects these interactions through a competitive positioning matrix, assessing relative strength across innovation velocity, commercial execution, market access sophistication, and lifecycle management capability.
Worldwide Janus Kinase (JAK) Inhibitors Market
Beyond Headline Growth: Regulatory, Supply, and Reimbursement Undercurrents
Market trajectory is never purely a function of clinical efficacy or sales momentum. It is continuously shaped by regulatory architecture, manufacturing realities, and reimbursement policy calibration. The research integrates these structural undercurrents into a cohesive market dynamics framework, enabling clients to stress-test their strategic assumptions against observable industry pressures.
Safety monitoring and risk communication remain central to prescriber behavior and formulary management. The 2021 regulatory addition of boxed warnings across the JAK inhibitor class for cardiovascular events, malignancy risk, thrombosis, and mortality has had lasting implications for prescribing confidence, patient selection criteria, and risk mitigation protocols. The study examines how manufacturers have adapted communication strategies, how guidelines have evolved, and how payer and provider risk tolerance continues to influence utilization patterns. These safety considerations intersect directly with market concentration dynamics, as established incumbents with mature safety databases may leverage real-world evidence to stabilize prescribing, while newer entrants must navigate heightened scrutiny and longer evidence-generation timelines.
Patent lifecycle management introduces another critical variable. The impending expiration of foundational patents on legacy molecules will alter competitive economics, potentially enabling generic entry and reshaping pricing architectures in mature markets. The report maps the timing, geographic scope, and commercial implications of these transitions, providing scenario analysis that helps teams anticipate revenue erosion curves, evaluate lifecycle extension strategies, and assess the feasibility of next-generation positioning ahead of market disruption.
Reimbursement policy continues to shape utilization at scale. National coverage determinations and specialty pharmacy benefit designs directly influence patient access, copayment structures, and prescription conversion rates. The study evaluates how coverage frameworks are evolving across major markets, how prior authorization requirements are altering prescribing workflows, and how manufacturers are structuring patient support programs and market access negotiations to preserve volume while navigating cost-containment pressures.
Supply chain resilience has emerged as a non-trivial commercial risk factor. Observed constraints in active pharmaceutical ingredient availability, driven by raw material dependencies and manufacturing bottlenecks, have introduced volatility into production planning and distribution reliability. The report integrates supply-side risk mapping into the broader commercial forecast, highlighting where capacity constraints may influence market share dynamics, delay launch execution, or create pricing dislocations in underserved distribution channels.
Translating Intelligence into 2026 Strategic Action
The strategic value of this research lies in its operational translation. For portfolio and lifecycle managers, the study provides the indication-by-indication demand mapping, competitive displacement risk assessment, and patent expiration scenario modeling needed to prioritize lifecycle extension investments, pipeline advancement decisions, and combination therapy positioning. For market access and pricing teams, it delivers payer segmentation insights, coverage determination trajectories, and formulary positioning analysis that inform rebate architecture, patient access program design, and commercial negotiation strategy. For corporate development and investment teams, it offers a structured view of competitive concentration, emerging molecular differentiation, and regional growth velocity that supports acquisition screening, partnership evaluation, and capital allocation discipline.
Worldwide Juvenile Idiopathic Arthritis Treatment Market
Crucially, the report does not treat growth as a uniform phenomenon. It isolates where demand is converging across selectivity profiles, where clinical adoption is accelerating or encountering friction, and where regional commercial execution will determine whether pipeline assets translate into durable market share or remain confined to niche utilization. By aligning segmentation depth with scenario flexibility, the study enables leadership teams to move beyond retrospective hindsight and operate with forward-looking strategic clarity.
The complete Worldwide JAK Inhibitors Market research provides the full segmentation architecture, region-by-region commercial profiling, selectivity-based demand analysis, application-specific utilization tracking, competitive positioning matrices, scenario sensitivity tables, and strategic implication playbooks required to operationalize these insights. The underlying data, modeling assumptions, and cross-referenced industry intelligence are structured to support rigorous internal review, executive alignment, and investment-grade decision-making.
For stakeholders preparing for the 2026 landscape and the forecast years that follow, the full report offers the depth, granularity, and strategic framing necessary to navigate a market defined by concentration, innovation velocity, regulatory recalibration, and shifting access dynamics. To access the complete analytical framework, segmentation detail, and decision-ready intelligence, explore the full publication and accompanying executive resources.
For detailed analysis of this topic, please visit the official page: Worldwide Janus Kinase (JAK) Inhibitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com