

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Aneurysm Coiling Revenue Hits $1,436M in 2025, Forecast 6.91% CAGR to $2,291M by 2032

Strategic Intelligence for the Neurovascular Frontier: The 2026 Aneurysm Coiling Market Outlook
The landscape of interventional neurology is undergoing a decisive transformation. As healthcare systems globally prioritize minimally invasive neurovascular interventions, the aneurysm coiling market stands at a critical inflection point. For executives, investors, and clinical strategists navigating this complex ecosystem, access to precise, forward-looking intelligence is not merely advantageous. It is imperative. In an environment defined by rapid technological iteration, shifting reimbursement frameworks, and an increasingly concentrated competitive landscape, strategic decisions made in 2026 will dictate market positioning through 2032. This article serves as a strategic preview of our latest market research publication, engineered to equip stakeholders with the analytical rigor required to navigate the coming growth cycle with confidence.
Worldwide Aneurysm Coiling Market
Worldwide Brain Hemorrhage Treatment Market
Market Trajectory and the Fundamentals of Sustained Growth
The macroeconomic foundation of the aneurysm coiling sector reflects a mature yet consistently expanding market. Drawing upon a comprehensive historical analysis spanning 2020 through 2025 and projecting forward across the 2026 to 2032 forecast period, our research delineates a clear trajectory of sustained revenue expansion. The global market generated approximately $1.04 billion in 2020 and has since charted a reliable upward curve, culminating in an estimated $1.44 billion in 2025. This consistent year-over-year progression underscores the structural resilience of neurovascular intervention demand.
Looking ahead, the forecast period indicates that annual revenue will surpass the $1.5 billion mark in 2026, accelerating toward a projected valuation exceeding $2.29 billion by 2032. This growth is underpinned by a compound annual growth rate of 6.91 percent, reflecting a harmonious convergence of expanding procedural volumes, technological refinement, and demographic shifts favoring early detection and intervention. It is crucial to recognize that this trajectory does not represent an organic plateau or a fleeting cycle of novelty-driven adoption. Rather, it signals a structural realignment in how health systems approach intracranial aneurysm management, with coiling increasingly positioned as a first-line therapeutic modality in appropriate clinical scenarios.
For corporate strategists, this macro backdrop provides essential context. The predictability of the revenue curve offers a reliable baseline for capacity planning, R&D allocation, and commercial pipeline sequencing. However, macroeconomic aggregates merely set the stage. The true strategic differentiators lie beneath the surface, within the nuanced segmentation architecture, competitive maneuvering, and regulatory variables that will ultimately determine which organizations capture disproportionate value in the coming years.
Deconstructing the Segmentation Architecture
The market is not a monolith. Our analysis decomposes the total revenue stream across multiple intersecting dimensions, revealing distinct value pools that demand tailored strategic responses. By examining product differentiation, regional deployment patterns, and end-user institutional pathways, the research maps out how revenue is distributed across the ecosystem and identifies the operational levers that most directly influence commercial performance.
Within the product landscape, the analysis highlights the continued dominance of established filtration and mechanical delivery architectures alongside the measured emergence of bioactive and coated variants. The market profile indicates a clear bifurcation in value contribution, where primary embolization platforms anchor the majority of total revenue, while specialized adjunctive and advanced-material coils represent a focused but strategically vital growth vector. Understanding the precise valuation and volume trajectory of each product category enables manufacturers to prioritize engineering roadmaps, clinical evidence generation, and pricing architectures with surgical precision.
Geographically, the revenue distribution reflects a healthcare ecosystem in transition. Established markets with mature neurovascular infrastructure demonstrate robust, stable demand profiles, supported by high procedural volumes and entrenched screening pathways. Concurrently, emerging regional markets are exhibiting accelerated uptake trajectories, driven by expanding interventional capabilities, growing patient awareness, and the gradual penetration of neurovascular services into previously underserved territories. The regional segmentation analysis within our report unpacks these dynamics without relying on superficial top-line figures, offering instead a granular assessment of procurement behaviors, channel structures, and localized reimbursement realities that shape market entry and scaling strategies.
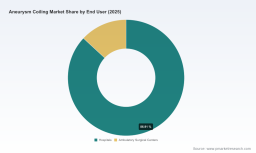
The institutional adoption landscape further refines the strategic picture. Hospitals continue to function as the primary procedural and procurement anchor, driven by complex case volumes and integrated neurovascular service lines. Simultaneously, ambulatory surgical centers represent a meaningful and expanding value segment, reflecting broader healthcare trends toward outpatient procedural migration and cost-optimized care delivery. The interplay between these two institutional pathways influences everything from device packaging and delivery logistics to clinical training programs and surgeon preference development. Our research quantifies these institutional dynamics in a manner that directly informs channel strategy, partnership structures, and commercialization sequencing.
Competitive Landscape: Concentration, Positioning, and Strategic Maneuvering
Market structure in the aneurysm coiling sector is characterized by pronounced concentration. With three major players accounting for nearly three-quarters of total market revenue and five leading organizations collectively commanding close to 90 percent, the competitive environment operates within a tightly woven ecosystem of established incumbents, technological innovators, and regional challengers. This concentration does not imply stagnation. Rather, it creates a high-stakes arena where marginal gains in product differentiation, clinical positioning, and geographic expansion yield outsized strategic advantages.
The incumbency advantage is anchored by organizations whose product families have achieved deep clinical integration and widespread procedural familiarity. Medtronic, headquartered in Dublin, has sustained its market presence through the Axium Detachable Coils family, encompassing the Axium, Axium Prime, and Axium MicroFX platforms designed for endovascular embolization of intracranial aneurysms and related neurovascular abnormalities. Stryker, based in Kalamazoo, Michigan, competes with its Target Detachable Coils family, including the Target Tetra configuration, engineered specifically for aneurysm coiling procedures. Terumo Neuro, operating from Aliso Viejo, California, delivers a comprehensive portfolio through its Cosmos Platinum Coils, Helical Specialty Coils, and related detachable configurations for brain aneurysm treatment. Penumbra, headquartered in Alameda, markets its Neuro Embolization System with the SwiftPAC, POD400, PAC400, PC400, and Ruby Coil System architectures for aneurysm embolization. Johnson & Johnson MedTech, through its Cerenovus division in New Brunswick, provides the Spectra Family of Coils designed to address aneurysm treatment requirements from framing through finishing. These organizations collectively establish the clinical reference points against which new entrants and next-generation platforms are measured.
The competitive field, however, extends well beyond the entrenched major players. Kaneka Corporation, based in Osaka, has entered the commercial arena with the i-ED COIL for brain aneurysm embolization, achieving a notable regulatory milestone through EU Medical Device Regulation certification, which enabled commercial sales in Europe starting in late 2025. Balt Group, operating from Montmorency, France, supplies neurovascular embolization coils and devices that support intracranial aneurysm treatment within European and international clinical networks. Phenox GmbH, part of the Wallaby Medical ecosystem and headquartered in Bochum, Germany, develops embolization coils and flow modulation devices that participate in aneurysm coiling and related neurovascular procedures. MicroPort NeuroTech, headquartered in Shanghai, China, provides neurovascular coils and devices focused on aneurysm embolization, reflecting the growing technological and commercial influence of the Asia-Pacific manufacturing base. Neuravention Inc., operating out of Buffalo, New York, is advancing an advanced brain aneurysm coil technology with a regulatory submission anticipated in early 2026 and a potential commercial launch or sale targeted within the same year. This array of competitors illustrates a market where established clinical credibility must be continuously defended while new entrants exploit regulatory pathways and geographic openings to establish footholds.
Market Dynamics: Reimbursement, Regulation, and Procedural Economics
Strategic planning in the aneurysm coiling sector must account for the interplay between clinical adoption and economic architecture. Reimbursement frameworks, regulatory approvals, and institutional cost structures function as powerful forces shaping procurement decisions, procedural volume trajectories, and ultimately, revenue realization. The 2026 operating environment introduces new variables that demand proactive integration into commercial and clinical strategy.
From a physician-facing economic standpoint, reimbursement for brain aneurysm coiling procedures remains a critical consideration for procedural volume and practice sustainability. Estimates indicate that physician payment for the relevant CPT code approximates $1,045 nationally in 2026, based on approximately 19.5 work RVUs under the Medicare Fee Schedule. This reimbursement level establishes a procedural economic baseline that influences provider willingness to expand coiling service lines, invest in training, and adopt new device platforms. Simultaneously, institutional reimbursement realities shape hospital and ambulatory center purchasing behaviors. The DRG payment for ruptured aneurysm with complications was adjusted to approximately $57,259 in 2026, creating a financial context in which device selection, procedural efficiency, and complication management carry direct implications for institutional margin performance. Understanding how device characteristics, delivery systems, and clinical outcomes intersect with these reimbursement parameters is essential for manufacturers seeking to align value propositions with the economic realities of healthcare providers.
Regulatory milestones further modulate the competitive landscape. The European Union Medical Device Regulation certification achieved by Kaneka for the i-ED COIL exemplifies the type of regulatory clearance that can unlock regional commercial activity and shift competitive dynamics. As regulatory frameworks continue to evolve across jurisdictions, market participants must navigate not only product approval pathways but also post-market surveillance requirements, clinical evidence expectations, and conformity assessment obligations. These regulatory layers influence time-to-market, market access strategies, and the long-term sustainability of product portfolios. In this context, strategic agility requires continuous monitoring of regulatory calendars, anticipation of compliance shifts, and alignment of clinical evidence generation with the evidentiary thresholds demanded by regulators and payers alike.
What the Research Delivers: Actionable Intelligence for 2026 Decision-Making
The strategic value of comprehensive market research lies not in retrospective validation but in forward-looking decision support. Our Worldwide Aneurysm Coiling Market study is engineered to provide exactly that. Rather than delivering generic overviews, the report constructs an operational intelligence framework designed for use by corporate strategy teams, commercial leadership, clinical affairs groups, and investor research functions.
The report delivers a detailed segmentation analysis that moves beyond surface-level aggregates to examine how revenue, volume, and adoption patterns unfold across product categories, geographic territories, and institutional end-user pathways. This breakdown equips readers with the ability to model scenario-based forecasts, evaluate market share dynamics, and identify underserved or high-growth segments that align with organizational capabilities and strategic objectives. The segmentation architecture is presented in a manner that supports both top-down portfolio planning and bottom-up tactical execution, enabling users to translate macro trends into specific commercial priorities.
Beyond segmentation, the research provides a competitive profiling structure that examines the strategic positioning, product architectures, technological differentiation, and commercial footprints of the leading market participants. Each company profile is contextualized within broader market dynamics, allowing readers to assess competitive threats, identify potential partnership or licensing opportunities, and evaluate the strategic implications of competitor product launches, regulatory achievements, and geographic expansion initiatives. This competitive analysis is paired with a forward-looking review of recent and anticipated developments, including product introductions, regulatory submissions, and certification milestones, ensuring that readers are equipped to anticipate rather than merely react to market shifts.
The report also integrates an assessment of market dynamics that connects reimbursement structures, regulatory frameworks, and procedural economics to commercial strategy. This section is designed to help stakeholders understand how policy and payment environments influence adoption curves, purchasing decisions, and long-term revenue sustainability. By mapping these dynamics against the competitive landscape and segmentation profile, the research provides a holistic view of the forces shaping the market and the levers available to influence outcomes.
Furthermore, the study incorporates historical trend analysis that establishes a reliable baseline for interpreting current market conditions and projecting future trajectories. This historical context is essential for distinguishing cyclical fluctuations from structural transitions, enabling organizations to allocate resources with confidence and avoid strategic missteps driven by short-term noise. The forecast architecture extends through 2032, offering a multi-year planning horizon that supports capital allocation decisions, pipeline development timelines, and market entry sequencing.
Navigating the 2026 Inflection Point
The aneurysm coiling market in 2026 is defined by a combination of predictable growth, concentrated competition, evolving reimbursement parameters, and a steady stream of regulatory and product developments. For organizations operating in this space, the margin between strategic success and marginal performance will depend on the ability to interpret these forces with precision and act upon that interpretation with discipline. High-level market size figures and top-line growth rates provide essential orientation, but they do not substitute for the segment-level insight, competitive depth, and dynamic context required to make informed decisions.
Our research publication closes these information gaps. It provides the analytical structure necessary to evaluate product portfolio positioning, assess commercial viability across regions and end-user segments, anticipate competitive responses, and align internal planning with the economic and regulatory realities of the operating environment. By integrating historical performance data, forward-looking forecasts, and contemporary industry developments into a single, coherent framework, the report delivers the strategic intelligence required to navigate the 2026 to 2032 growth cycle with clarity and confidence.
For executives seeking to translate market opportunity into executable strategy, this research serves as a foundational decision-support tool. Detailed segmentation valuations, regional volume trajectories, end-user adoption pathways, competitive benchmarking matrices, and scenario-based modeling frameworks are presented within the full report to enable precise planning and targeted execution. Readers are encouraged to access the complete publication to explore these elements in full and to integrate the comprehensive dataset into their 2026 strategic planning processes.
For detailed analysis of this topic, please visit the official page: Worldwide Aneurysm Coiling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com