

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Handheld Medical Equipment Market to Reach USD 101,721M by 2032 at 8.3% CAGR

Strategic Imperative: Navigating the 2026 Handheld Medical Equipment Market Landscape
The global landscape of healthcare delivery is undergoing a profound transformation, driven by an urgent demand for portability, point-of-care accessibility, and intelligent diagnostic capabilities. As we move through 2026, the handheld medical equipment sector stands at the forefront of this shift, representing not merely a product category but a critical vector for strategic growth across the life sciences and medical technology industries. PW Consulting's latest Worldwide Handheld Medical Equipment Market study offers a comprehensive lens into this dynamic environment, providing enterprise leaders with the actionable intelligence required to navigate complex supply chains, regulatory frameworks, and competitive pressures.
For C-suite executives, investors, and product strategists, the decisions made in 2026 will define market positioning for the remainder of the decade. The sector is characterized by rapid technological convergence, where traditional medical hardware integrates seamlessly with artificial intelligence, wireless connectivity, and consumer-grade usability. Understanding the magnitude of this shift requires more than surface-level observation; it demands a rigorous analysis of market trajectories, segmentation nuances, and the evolving tactics of key incumbents. This introduction outlines the strategic value embedded within our full research report, highlighting why deep-dive intelligence is indispensable for capitalizing on the opportunities emerging in this high-growth segment.
Market Trajectory and Financial Scale
The financial scale of the handheld medical equipment market underscores its significance as a core component of the broader medical device ecosystem. Based on rigorous analysis conducted by our research team, the market has demonstrated robust expansion over the historical period from 2020 to 2025, culminating in a substantial valuation in the base year of 2025. Our projections extend through 2032, offering a long-term view essential for capital allocation and R&D planning.
Handheld Tester Market
The market momentum is quantified by a Compound Annual Growth Rate (CAGR) that reflects sustained demand across diverse clinical and consumer applications. This growth trajectory is not linear but is influenced by accelerating adoption rates in emerging healthcare settings, regulatory approvals that open new revenue streams, and the continuous innovation cycles of leading manufacturers. The revenue figures, denominated in USD and measured in millions, illustrate a sector that is scaling efficiently while managing the complexities of global distribution.
By examining the historical data alongside forward-looking estimates, stakeholders can identify inflection points where investment in capacity or strategic partnerships yields the highest return. The forecast period from 2026 to 2032 suggests a continued upward trend, with market value expanding significantly by the end of the forecast window. Such data is critical for modeling total addressable market (TAM) scenarios and assessing the viability of new product launches against the backdrop of overall sector expansion. However, the aggregate numbers are only the starting point; the true strategic insight lies in understanding how these revenues are distributed across types, applications, and regions, which our full report dissects with precision.
Segmentation Dynamics and Growth Vectors
The handheld medical equipment market is not a monolith. It is composed of distinct segments that behave differently under varying economic and clinical pressures. A superficial view of the market misses the nuanced drivers that determine success in specific niches. Our analysis categorizes the market by type, application, and region, revealing where the highest intensity of activity and value creation is occurring.
Within the type segmentation, the market spans monitoring devices, diagnostic and imaging devices, and therapeutic devices. Each category faces unique technological hurdles and regulatory pathways. Monitoring devices, for instance, are seeing heightened interest due to the proliferation of remote patient monitoring initiatives, while diagnostic and imaging devices are benefiting from advancements in miniaturization and AI-powered image analysis. Therapeutic devices represent a specialized but vital segment, often requiring higher levels of clinical validation and integration with surgical workflows.
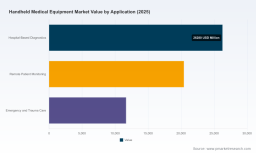
Application-wise, the market serves hospital-based diagnostics, remote patient monitoring, and emergency and trauma care. The demand for hospital-based diagnostics remains a steady anchor, driven by the need for rapid, bedside decision-making. Remote patient monitoring, however, is reshaping the volume dynamics, shifting care from institutional settings to homes and community clinics. This shift is particularly relevant for chronic disease management and post-acute care, where handheld technologies enable continuous data flow without compromising patient comfort. Emergency and trauma care applications demand ruggedness, speed, and reliability, creating a distinct set of requirements for manufacturers operating in this space.
Regional segmentation further complicates the picture. Demand patterns vary significantly based on healthcare infrastructure maturity, reimbursement policies, and local manufacturing capabilities. Some regions represent mature markets with high saturation and intense competition, while others offer greenfield opportunities driven by healthcare expansion and increasing access to medical technology. Our report provides a detailed geographic breakdown that allows strategists to tailor their market entry or expansion plans according to local realities, avoiding the pitfalls of applying a one-size-fits-all approach. Specific revenue allocations and percentage splits for each region and segment are detailed in the full report, enabling precise benchmarking and target setting.
Competitive Landscape and Strategic Positioning
The competitive environment in the handheld medical equipment market is defined by a mix of established multinational giants and agile innovators disrupting traditional paradigms. Understanding the positioning, capabilities, and recent moves of these players is essential for any company seeking to defend its market share or capture new ground. Our report profiles key companies that collectively shape the industry's direction, analyzing their product portfolios, strategic focus, and recent developments.
Major players such as Koninklijke Philips N.V., GE HealthCare, Medtronic plc, Abbott Laboratories, and Siemens Healthineers command significant influence through their extensive portfolios and global reach. Philips offers handheld and portable ultrasound systems, patient monitoring devices, and point-of-care diagnostic equipment. GE HealthCare provides handheld ultrasound devices and portable patient monitoring systems focused on diagnostic accessibility. Medtronic supplies handheld devices including pulse oximeters, ECG monitors, and surgical navigation tools. Abbott Laboratories delivers portable diagnostic and monitoring solutions, including handheld glucose monitoring systems and cardiac rhythm management devices. Siemens Healthineers contributes with portable ultrasound and point-of-care diagnostic imaging equipment. These incumbents leverage scale, brand trust, and integrated ecosystem strategies to maintain strong positions.
Simultaneously, specialized and innovative firms are carving out niche dominance with focused technologies. Omron Healthcare specializes in handheld and portable blood pressure monitors, nebulizers, and thermometers. Butterfly Network focuses exclusively on smartphone-connected handheld ultrasound devices for whole-body point-of-care imaging. Stryker Corporation develops handheld robotic systems and portable surgical tools. Mindray Medical International produces wireless handheld ultrasound systems and portable patient monitoring equipment. Clarius Mobile Health specializes in wireless handheld ultrasound scanners for point-of-care applications. AliveCor offers Kardia series handheld ECG devices with AI-powered analysis. These companies often drive innovation in usability, cost reduction, and specific clinical workflows, challenging established players to adapt or risk losing relevance in high-growth sub-segments.
Market concentration metrics indicate that while the top players hold substantial shares, there is room for disruption and consolidation. The competitive intensity varies by segment; for example, the handheld ultrasound space is highly contested, while other therapeutic or monitoring niches may have different concentration dynamics. Our report includes a detailed competitive analysis that maps these dynamics, helping companies identify white spaces, assess competitive threats, and formulate differentiation strategies. The full report provides granular insights into market shares, strategic partnerships, and technology roadmaps that are not visible through public announcements alone.
Regulatory and Technology Dynamics
The regulatory environment remains a critical determinant of market access and product viability. Recent developments highlight the ongoing importance of regulatory clearance in shaping the product landscape. Throughout 2025 and early 2026, multiple companies have secured FDA 510(k) clearances for novel handheld devices, signaling an active pipeline of innovations entering the market.
Notable clearances include Swift Medical's FDA 510(k) clearance in March 2026 for the Swift Ray spectral imaging device, a handheld wound assessment tool combining spectral imaging with AI. AliveCor received FDA clearance in January 2026 for the next-generation KAI 12L AI powering the Kardia 12L handheld 12-lead ECG system, adding five new cardiac determinations. Guilin Woodpecker Medical Instrument Co., Ltd. obtained FDA 510(k) clearance in September 2025 for Ai Ray series super capacitor-operated portable handheld dental X-ray devices. Stryker received FDA 510(k) clearance in September 2025 for RPS Primary TKA Software and handheld robotic saw components in the Robotic Power System for knee arthroplasty. AI Optics gained FDA 510(k) clearance in January 2026 for the Sentinel Camera, a portable handheld retinal imaging system for non-dilated eye screening.
These events underscore the regulatory rigor required for handheld devices, whether they involve imaging, diagnostics, or robotics. Handheld medical devices such as dental X-ray units, ECG systems, and spectral imaging tools continue to require FDA 510(k) clearance demonstrating substantial equivalence to predicate devices under general controls including IEC 60601 safety standards. Portable and handheld X-ray equipment must comply with specific radiation protection standards including IEC 60601-1-3 and IEC 61223-3-4 for imaging performance and safety in diagnostic use. Handheld robotic surgical systems like Stryker RPS require FDA clearance under 21 CFR 882.4560 as stereotaxic instruments with camera-guided boundary control for intraoperative resection planning. Compliance with these standards is non-negotiable and influences product design, manufacturing processes, and time-to-market.
Technological dynamics are equally pivotal. Hospital adoption of handheld and portable devices is driven by demand for point-of-care diagnostics in emergency, ambulatory, and remote settings, supported by integration with AI for improved workflow efficiency. The convergence of hardware miniaturization, wireless connectivity, and AI algorithms is enabling capabilities that were previously confined to larger, stationary systems. AI-powered analysis, for instance, is enhancing the diagnostic utility of handheld ECGs and imaging devices, reducing interpretation burden and improving accuracy. Manufacturers that effectively integrate these technologies into user-friendly, clinically validated solutions are poised to capture significant value. Our report analyzes these technology trends in depth, linking them to market demand and competitive responses.
Strategic Implications for 2026 and Beyond
The insights contained in our Worldwide Handheld Medical Equipment Market study are designed to inform critical strategic decisions in 2026. Whether the objective is to launch a new product, expand into a new geography, optimize a supply chain, or assess acquisition targets, the data and analysis provided serve as a foundational resource. The market's growth trajectory, segmentation patterns, and competitive dynamics all point to a landscape where informed agility is a competitive advantage.
For product developers, understanding the specific requirements of different applications and regions is vital for designing devices that meet clinical needs and regulatory standards. For commercial teams, the segmentation data helps prioritize sales efforts and marketing investments in the most promising areas. For finance and strategy leaders, the market size and CAGR projections support valuation models, budgeting, and long-term planning. The competitive profiles and recent developments offer context for anticipating rival moves and identifying partnership opportunities.
Furthermore, the regulatory and technology trends highlight the need for proactive compliance management and innovation investment. Companies must stay ahead of evolving standards and leverage emerging technologies to differentiate their offerings. The report's comprehensive coverage ensures that stakeholders have a holistic view of the factors influencing market outcomes, reducing uncertainty and enabling more confident decision-making.
Unlock the Full Intelligence
While this overview provides a glimpse into the scale, structure, and dynamics of the handheld medical equipment market, the full report contains the detailed data, granular segmentation analysis, comprehensive company profiles, and actionable recommendations necessary for executing a winning strategy. The macro trends and competitive themes discussed here are merely the entry point to a rich repository of market intelligence.
PW Consulting's Worldwide Handheld Medical Equipment Market report is the definitive resource for organizations seeking to navigate this complex and rapidly evolving sector. The report delivers specific revenue figures, percentage splits, regional breakdowns, and deep-dive analyses that empower stakeholders to move from general awareness to precise action. To access the complete dataset, detailed segmentation splits, full competitor profiles, and strategic insights that will drive your 2026 decisions, we invite you to explore the full report. Discover the depth of analysis that can transform your understanding of the market and position your organization for sustained success in the handheld medical equipment landscape.
Worldwide Handheld Medical Equipment Market
For detailed analysis of this topic, please visit the official page: Worldwide Handheld Medical Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com