

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Ibrutinib Market Hits $954.91M in 2025, 3.88% CAGR to 2032

Strategic Intelligence for 2026: Navigating the Pharma Grade Ibrutinib Market
The global pharmaceutical landscape is entering a definitive period of transformation, characterized by the complex interplay of patent cliffs, biosimilar competition, and evolving reimbursement architectures. At the center of this shift lies the Pharma Grade Ibrutinib Market, a critical segment within the oncology supply chain that demands precise strategic positioning. As enterprise leaders formulate their roadmaps for 2026 and beyond, understanding the nuanced trajectory of this market is not merely an academic exercise but a commercial imperative. This insight serves as a precursor to our comprehensive Worldwide Pharma Grade Ibrutinib Market research, designed to equip stakeholders with the actionable intelligence required to mitigate risk and capture growth in a maturing therapeutic category.
Our analysis indicates that the sector is moving past the early adoption phase of novel BTK inhibitors into a period of stabilized demand and intensified supply chain scrutiny. For manufacturers, procurement officers, and investment strategists, the ability to distinguish between short-term volatility and long-term structural trends will define competitive advantage. The following overview outlines the macro-economic context, the competitive architecture, and the regulatory headwinds that our full report dissect in granular detail.
Market Magnitude and Growth Trajectory
To anchor strategic planning, one must first establish the baseline of market performance. Historical data from 2020 through 2025 reveals a consistent upward trajectory in revenue generation for pharma grade ibrutinib. The market has demonstrated resilience even amidst broader pharmaceutical supply chain disruptions. Our baseline year analysis places the 2025 revenue at approximately 954.91 Million USD, reflecting a mature yet expanding ecosystem. This growth is not accidental; it is driven by entrenched usage in key oncology indications and the gradual expansion of formulations to improve patient compliance.
Worldwide Pharma Grade Ibrutinib Market
Looking forward, the forecast period spanning 2026 to 2032 suggests a continued, albeit moderated, expansion. The projected Compound Annual Growth Rate (CAGR) stands at 3.88 percent. This figure is critical for financial modeling, as it implies a market that is growing organically without the explosive entry seen in novel first-in-class drugs. By 2032, the market revenue is projected to reach 1246.34 Million USD. This steady climb underscores the enduring relevance of ibrutinib in treatment protocols, even as next-generation inhibitors enter the pipeline. However, the path to 2032 is not linear. Stakeholders must account for regulatory milestones and pricing pressures that could alter the slope of this growth curve.
Understanding the aggregate size is only the first step. The distribution of this value across regions and applications tells the real story of where value is created and captured. Our full report delineates these segments without exposing the primary intelligence to the open market, ensuring that subscribers gain an edge over competitors who rely on public estimates.
Key Report Content and Operational Utility
The value of a market study lies in its applicability to daily decision-making. Our research is constructed to serve as a functional toolkit rather than a static document. It encompasses a deep dive into the supply chain mechanics, from active pharmaceutical ingredient (API) sourcing to finished dosage form distribution. We analyze the purity standards that dominate the market, distinguishing between high-purity grades required for branded formulations and the specifications acceptable for generic entrants. This distinction is vital for procurement teams negotiating contracts with API manufacturers in regions such as India and China, where production capabilities vary significantly.
Furthermore, the report details the regulatory landscape governing production and distribution. Quality compliance, Good Manufacturing Practice (GMP) certifications, and regional approval statuses are mapped out to identify potential bottlenecks. For companies looking to enter the market or expand their footprint, understanding the licensing environment is as important as understanding the demand volume. The study also covers logistics and distribution channels, highlighting how temperature-sensitive formulations and oral suspensions are managed across different geographies. This operational granularity allows supply chain managers to stress-test their networks against potential disruptions.
Another critical component is the analysis of pricing dynamics at the raw material level. Transaction-based pricing for ibrutinib API fluctuates based on quantity and destination, creating opportunities for arbitrage or cost optimization depending on the buyer's location and volume commitments. Our report synthesizes this data to provide a benchmark for cost modeling, enabling manufacturers to set competitive pricing strategies without eroding margins.
Competitive Landscape and Strategic Positioning
The market structure is defined by a mix of originator companies and a robust cohort of generic manufacturers. The concentration of market power is significant, with the top three companies holding a substantial share of the revenue. This concentration suggests that barriers to entry remain high, particularly in regulated markets like North America and Europe. However, the presence of multiple active players from India indicates a competitive pressure that will intensify as patent protections evolve.
Leading the branded segment are Janssen Pharmaceuticals (Johnson & Johnson) and Pharmacyclics LLC (AbbVie). These entities remain the dominant commercializers of the branded Imbruvica formulation. Their strategy involves not just maintaining market share but expanding the utility of the drug through new formulations and clinical data. For instance, recent clinical data presentation from November 2025 regarding the Phase 3 CLL17 trial results comparing fixed-duration IMBRUVICA plus venetoclax versus continuous IMBRUVICA in previously untreated CLL at the ASH 2025 plenary session signals a shift in treatment paradigms. Such data can influence prescribing habits and volume demand, making it essential for competitors to monitor these developments closely.
On the generic side, the landscape is dense with activity. Indian pharmaceutical companies are particularly prominent. Natco Pharma Ltd, MSN Labs, Dr. Reddy's Laboratories, Hetero Labs Limited, and Zydus Lifesciences Limited are all active producers or developers of ibrutinib API and formulations. Zydus Lifesciences Limited notably received tentative FDA approval for generic ibrutinib tablets in multiple strengths for CLL/SLL and WM indications in July 2025. This regulatory milestone is a harbinger of future competition once full exclusivity periods lapse. Other key players such as Cipla Limited, Sun Pharmaceutical Industries Ltd, Aurobindo Pharma Limited, Lupin Limited, and Glenmark Pharmaceuticals are listed as active in the generic space, signaling a crowded field ready to capture volume upon patent expiry.
Beyond India, manufacturers like Polpharma in Poland and Senova Technology Co., Ltd. and Sinoway Industrial Co., Ltd. in China represent the globalized nature of API production. The diversity of these players means that supply chain resilience is possible, but quality consistency becomes a paramount concern. Our report profiles these companies to assess their capacity, compliance history, and potential threat level to existing market incumbents.
Regulatory and Reimbursement Dynamics
No strategic assessment of the ibrutinib market is complete without addressing the regulatory and reimbursement environment, which acts as both a gatekeeper and a price setter. One of the most significant developments for the US market is the impact of the Inflation Reduction Act. Under this legislation, the negotiated Medicare Part D maximum fair price for a 30-day supply of ibrutinib is set to be 9,319 USD starting January 2026. This represents a substantial reduction from the 2023 list price of 14,934 USD, marking a 38 percent decrease. This policy shift will inevitably compress margins for branded manufacturers and alter the economic calculus for generic entrants aiming to undercut the negotiated price.
Worldwide Imbruvica Market
Patent cliffs and exclusivity periods further complicate the timeline for market entry. In the U.S., the composition of matter patent covering ibrutinib is expected to expire in 2027, with pediatric regulatory exclusivity extending until May 2028. However, additional patents suggest no generic entry is expected prior to March 30, 2032. This long exclusivity window provides a buffer for branded owners but creates a waiting game for generic manufacturers. In contrast, the situation in China differs markedly. The compound patent for ibrutinib expires at the end of 2026, with multiple local generics already approved by companies such as Simcere, Qilu, and Huadong Medicine. This regional divergence requires multinational strategies to be highly localized, as the competitive intensity in China will likely outpace that in the US during the 2026-2027 period.
Regulatory withdrawals also shape the indication landscape. In April 2023, there was a voluntary withdrawal of U.S. accelerated approvals for IMBRUVICA in mantle cell lymphoma (after prior therapy) and marginal zone lymphoma indications following confirmatory trial results. Such shifts reduce the addressable market size for specific indications and require companies to recalibrate their sales forecasts. Additionally, label expansions, such as the U.S. FDA approval in February 2024 for the IMBRUVICA oral suspension formulation for adult patients, open new avenues for patient access and adherence, potentially offsetting volume losses in other areas.
Strategic Implications for 2026 Decision Makers
For enterprise leaders, the convergence of these factors demands a proactive rather than reactive posture. The 3.88 percent CAGR suggests stability, but the regulatory pressures indicate margin compression. Companies must decide whether to compete on volume, differentiation, or supply chain efficiency. For API manufacturers, the variance in pricing across regions like India and Russia offers opportunities for export optimization, but reliance on single-source regions introduces risk. For branded companies, the focus must remain on clinical differentiation and formulation innovation to justify pricing in the face of reimbursement cuts.
The competitive landscape is bifurcated. While the top players consolidate their position through clinical data and formulation updates, a large cohort of generic manufacturers in India and China is positioning for the eventual expiry of key protections. The tentative approval by Zydus and the early generic approvals in China suggest that the pressure will build incrementally rather than all at once. Monitoring these regulatory filings is essential for predicting market share erosion before it happens.
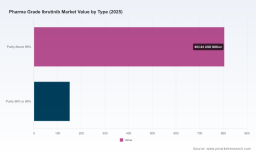
Our full report provides the segmented data necessary to quantify these risks. It breaks down the revenue contribution by region, allowing strategists to identify which markets are over-indexed on growth or decline. It details the split by purity and application, revealing which specific indications are driving demand and which purity grades are commanding premium pricing. This level of detail is crucial for product planning and resource allocation.
Decision makers should use this intelligence to stress-test their 2026 budgets. The reduction in Medicare pricing will impact overall market revenue realization in the US, the largest region by value. Meanwhile, the early patent expiry in China will create a price war environment that could affect global pricing benchmarks. Supply chain managers must verify the compliance status of their API suppliers, particularly those in regions with varying regulatory oversight, to prevent Quality Assurance disruptions that could halt production.
In conclusion, the Pharma Grade Ibrutinib Market is at a inflection point where historical growth meets future constraint. The data indicates a market that will continue to expand in absolute terms but faces significant headwinds in pricing and exclusivity. Success in this environment requires a granular understanding of the competitive moves, regulatory timelines, and supply chain realities. This article serves as an introduction to the depth of analysis available in our Worldwide Pharma Grade Ibrutinib Market study. We invite stakeholders to access the full repository for the specific segmentation data, company profiling, and forecast models that will underpin robust strategic planning for the coming years.
For detailed analysis of this topic, please visit the official page: Worldwide Pharma Grade Ibrutinib Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com