

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: JAK Inhibitors Market to Reach $40.5B by 2032, 14.01% CAGR

Navigating the Next Wave: Strategic Insights from the 2026 Worldwide JAK Inhibitors Market Intelligence
The Janus Kinase (JAK) inhibitor landscape is undergoing a fundamental transformation. As the therapeutic class matures beyond its initial breakthrough era, pharmaceutical executives, investors, and healthcare strategists face a complex matrix of clinical differentiation, regulatory reinterpretations, patent cliff disruptions, and shifting reimbursement architectures. Our newly released Worldwide JAK Inhibitors Market research delivers the analytical rigor required to navigate this inflection point. This publication is not merely a retrospective summary of historical sales; it is a forward-looking decision architecture designed explicitly for enterprise strategy in 2026 and beyond. By mapping the trajectory from baseline market conditions through the 2026-2032 forecast horizon, the study provides a structured lens through which stakeholders can anticipate competitive displacement, evaluate pipeline positioning, and allocate capital with precision.
The Macro Trajectory: Why 2026 Serves as a Strategic Inflection Point
Historical momentum establishes the foundation. Between 2020 and 2025, the global JAK inhibitors market expanded from approximately 7.4 billion to 16.2 billion USD, reflecting a sustained adoption curve across inflammatory, autoimmune, and hematologic indications. The forecast period extends this trajectory through 2032, with base-year positioning in 2025 and a compound annual growth rate of 14.01 percent. By mid-decade, the market is projected to cross the 17.7 billion threshold, with continued acceleration pushing toward the 40 billion mark by the close of the forecast window. These figures represent more than aggregate revenue; they signal a structural reallocation of therapeutic preference, payer budget prioritization, and clinical guideline integration.
For corporate strategy teams, the 2026 baseline is particularly consequential. It sits at the intersection of multiple simultaneous forces: the expiration of foundational patents, the widening of label expansions into pediatric and niche dermatology populations, the maturation of next-generation selective molecules, and the ongoing recalibration of safety monitoring frameworks. The 14 percent CAGR does not emerge in a vacuum. It is the product of overlapping demand drivers, supply chain adaptations, and commercialization agility. Understanding how these variables compound—and where they diverge across therapeutic categories and geographic commercial footprints—requires the granular segmentation and scenario modeling contained in the full report.
Structural Pillars of the Analysis: What the Report Delivers
The research is engineered to translate macroeconomic signals into actionable commercial intelligence. Rather than presenting static snapshots, the study employs a multi-dimensional segmentation architecture that enables clients to isolate the levers most relevant to their strategic mandate. The analytical framework is organized around three core dimensions, each designed to answer specific decision-making questions:
- Therapeutic Selectivity & Molecular Architecture: The study dissects the commercial footprint across JAK1-selective inhibitors, JAK1/JAK2 dual-target agents, and pan-JAK inhibitors. This classification is not merely biochemical; it maps directly to safety profile differentiation, prescriber confidence trajectories, formulary positioning, and patient compliance dynamics. The segmentation reveals how selectivity profiles influence market share allocation, pricing resilience, and the competitive runway for pipeline assets seeking to capture adjacent indications.
- Clinical Application & Indication Expansion: Demand is analyzed across rheumatoid arthritis, atopic dermatitis, myelofibrosis, and the combined ulcerative colitis/psoriatic arthritis spectrum. The report tracks how label expansions, real-world evidence accumulation, and guideline endorsements have reshaped utilization patterns. It further examines the commercialization implications of跨界 prescribing, off-label adoption curves, and the strategic value of indication sequencing when navigating payer segmentation and specialty pharmacy distribution networks.
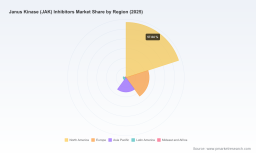
- Regional Commercial Dynamics: The geographic breakdown isolates pricing architecture variability, regulatory approval cadence, market access timelines, and competitive density across major commercial territories. The report evaluates how localized reimbursement frameworks, health technology assessment (HTA) requirements, and distribution channel maturity influence revenue realization. Regional analysis is structured to help multinational teams calibrate launch sequencing, prioritize market entry investments, and anticipate the velocity of generic or biosimilar erosion in mature markets.
Beyond segmentation, the study integrates supply chain vulnerability mapping, manufacturing capacity constraints, and raw material dependency analysis, drawing on observable industry signals to highlight where operational resilience will become a competitive differentiator. The report also incorporates payer behavior modeling, formulary tier positioning, and coverage determination dynamics that directly affect prescription volume conversion. Each analytical module is paired with executive-ready visualizations, scenario sensitivity tables, and strategic implication summaries tailored for cross-functional alignment between commercial, medical affairs, market access, and corporate development teams.
Competitive Architecture: Incumbents, Expansionists, and Pipeline Challengers
The JAK inhibitor market is characterized by pronounced concentration among a core group of multinational innovators, yet the competitive environment is far from static. The research maps the strategic posture, portfolio architecture, and recent commercialization moves of the principal market participants, providing a comparative lens through which clients can benchmark positioning, identify white-space opportunities, and anticipate tactical responses.
Pfizer continues to anchor a substantial share of the legacy market through its tofacitinib franchise, leveraging a broad indication footprint across rheumatoid arthritis, psoriatic arthritis, ulcerative colitis, and ankylosing spondylitis. Recent regulatory expansions into pediatric polyarticular course juvenile idiopathic arthritis and juvenile psoriatic arthritis demonstrate a deliberate strategy to extend the product lifecycle, deepen prescriber familiarity, and capture earlier intervention pathways. Incyte maintains a differentiated position through its ruxolitinib portfolio, with therapeutic applications spanning myelofibrosis, polycythemia vera, and graft-versus-host disease. The recent topical formulation approval for nonsegmental vitiligo reflects an ongoing effort to translate systemic JAK inhibition into specialty dermatology channels, broadening the commercial addressable market beyond hematology. Eli Lilly has positioned baricitinib as a multi-indication asset, capturing autoimmune and inflammatory segments including severe alopecia areata, where pediatric label expansion signals an intent to capture unmet demand in younger patient cohorts. AbbVie has aggressively expanded its upadacitinib franchise across rheumatology, dermatology, and gastroenterology, with pediatric ulcerative colitis approval reinforcing its commitment to broad therapeutic coverage and competitive density in high-prescription-volume disease states. Gilead, operating through a strategic partnership model, continues to advance filgotinib in select markets, illustrating how collaborative commercialization structures can sustain presence in mature therapeutic categories while managing risk and resource allocation. Meanwhile, emerging players such as Conatus Pharmaceuticals, backed by Roivant Sciences, are pursuing next-generation molecular designs targeting selective IRAK4/JAK1 pathways, with clinical-stage programs directed at hematologic malignancies. This pipeline activity signals a gradual diversification of the molecular target landscape, raising the strategic question of whether future market leadership will be defined by incremental selectivity optimization or by entirely new pathway combinations.
The concentration metrics underscore the entrenched nature of the incumbent base, with the top three participants commanding a substantial share of aggregate revenue and the top five entities controlling an even larger portion of market value. High concentration does not, however, equate to static market behavior. Patent expirations, safety-signal recalibration, payer formulary re-evaluations, and pipeline-driven indication displacement are introducing dynamic competitive friction. The report dissects these interactions through a competitive positioning matrix, assessing relative strength across innovation velocity, commercial execution, market access sophistication, and lifecycle management capability.
Worldwide Janus Kinase (JAK) Inhibitors Market
Beyond Headline Growth: Regulatory, Supply, and Reimbursement Undercurrents
Market trajectory is never purely a function of clinical efficacy or sales momentum. It is continuously shaped by regulatory architecture, manufacturing realities, and reimbursement policy calibration. The research integrates these structural undercurrents into a cohesive market dynamics framework, enabling clients to stress-test their strategic assumptions against observable industry pressures.
Safety monitoring and risk communication remain central to prescriber behavior and formulary management. The 2021 regulatory addition of boxed warnings across the JAK inhibitor class for cardiovascular events, malignancy risk, thrombosis, and mortality has had lasting implications for prescribing confidence, patient selection criteria, and risk mitigation protocols. The study examines how manufacturers have adapted communication strategies, how guidelines have evolved, and how payer and provider risk tolerance continues to influence utilization patterns. These safety considerations intersect directly with market concentration dynamics, as established incumbents with mature safety databases may leverage real-world evidence to stabilize prescribing, while newer entrants must navigate heightened scrutiny and longer evidence-generation timelines.
Patent lifecycle management introduces another critical variable. The impending expiration of foundational patents on legacy molecules will alter competitive economics, potentially enabling generic entry and reshaping pricing architectures in mature markets. The report maps the timing, geographic scope, and commercial implications of these transitions, providing scenario analysis that helps teams anticipate revenue erosion curves, evaluate lifecycle extension strategies, and assess the feasibility of next-generation positioning ahead of market disruption.
Reimbursement policy continues to shape utilization at scale. National coverage determinations and specialty pharmacy benefit designs directly influence patient access, copayment structures, and prescription conversion rates. The study evaluates how coverage frameworks are evolving across major markets, how prior authorization requirements are altering prescribing workflows, and how manufacturers are structuring patient support programs and market access negotiations to preserve volume while navigating cost-containment pressures.
Supply chain resilience has emerged as a non-trivial commercial risk factor. Observed constraints in active pharmaceutical ingredient availability, driven by raw material dependencies and manufacturing bottlenecks, have introduced volatility into production planning and distribution reliability. The report integrates supply-side risk mapping into the broader commercial forecast, highlighting where capacity constraints may influence market share dynamics, delay launch execution, or create pricing dislocations in underserved distribution channels.
Translating Intelligence into 2026 Strategic Action
The strategic value of this research lies in its operational translation. For portfolio and lifecycle managers, the study provides the indication-by-indication demand mapping, competitive displacement risk assessment, and patent expiration scenario modeling needed to prioritize lifecycle extension investments, pipeline advancement decisions, and combination therapy positioning. For market access and pricing teams, it delivers payer segmentation insights, coverage determination trajectories, and formulary positioning analysis that inform rebate architecture, patient access program design, and commercial negotiation strategy. For corporate development and investment teams, it offers a structured view of competitive concentration, emerging molecular differentiation, and regional growth velocity that supports acquisition screening, partnership evaluation, and capital allocation discipline.
Worldwide Juvenile Idiopathic Arthritis Treatment Market
Crucially, the report does not treat growth as a uniform phenomenon. It isolates where demand is converging across selectivity profiles, where clinical adoption is accelerating or encountering friction, and where regional commercial execution will determine whether pipeline assets translate into durable market share or remain confined to niche utilization. By aligning segmentation depth with scenario flexibility, the study enables leadership teams to move beyond retrospective hindsight and operate with forward-looking strategic clarity.
The complete Worldwide JAK Inhibitors Market research provides the full segmentation architecture, region-by-region commercial profiling, selectivity-based demand analysis, application-specific utilization tracking, competitive positioning matrices, scenario sensitivity tables, and strategic implication playbooks required to operationalize these insights. The underlying data, modeling assumptions, and cross-referenced industry intelligence are structured to support rigorous internal review, executive alignment, and investment-grade decision-making.
For stakeholders preparing for the 2026 landscape and the forecast years that follow, the full report offers the depth, granularity, and strategic framing necessary to navigate a market defined by concentration, innovation velocity, regulatory recalibration, and shifting access dynamics. To access the complete analytical framework, segmentation detail, and decision-ready intelligence, explore the full publication and accompanying executive resources.
For detailed analysis of this topic, please visit the official page: Worldwide Janus Kinase (JAK) Inhibitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com