

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Omni-channel Warehouse Management Systems Hit $4.99B in 2025, 13.98% CAGR to 2032

Strategic Intelligence for the Omni-Channel Warehouse Era: Insights from the 2026 Global Market Study
The global supply chain has entered a period of irreversible transformation. As customer expectations for speed, transparency, and seamless fulfillment continue to rise, warehouse management systems (WMS) and omni-channel orchestration platforms have evolved from back-office utilities into core strategic assets. Our newly released Worldwide Omni-channel and Warehouse Management Systems Market research study provides decision-makers with a comprehensive, data-driven roadmap for navigating this shift through 2032. Built on rigorous primary and secondary research, the report translates macro-market momentum into actionable intelligence tailored for enterprise strategists, procurement leaders, and technology architects operating in 2026 and beyond.
Retail Omni Channel Commerce Platform Market
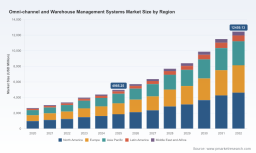
At the foundation of this analysis lies a clear macroeconomic signal: the market has demonstrated sustained, double-digit expansion over the past half-decade, with historical valuations climbing steadily from 2020 through 2025. This trajectory reflects not only incremental digital adoption but a structural reorientation of how organizations design, operate, and scale distribution networks. Looking forward, the study projects continued aggressive growth across the forecast horizon, underpinned by a compound annual growth rate that underscores the strategic urgency of modernizing warehouse execution capabilities. Rather than presenting isolated figures, our methodology contextualizes this momentum within operational realities, investment cycles, and competitive pressures that will define enterprise technology roadmaps in the coming years. Readers seeking the full numerical architecture, scenario modeling, and granular segmentation will find a direct pathway to the complete dataset within the published study.
Why 2026 Demands a New WMS Investment Thesis
Entering 2026, the operational imperative has shifted from incremental efficiency gains to architectural resilience. Several converging forces are redefining how enterprises evaluate warehouse technology investments, and each carries distinct implications for budget allocation, platform selection, and vendor partnerships. First, cloud-native deployment has fundamentally altered the capital expenditure profile of warehouse modernization. By eliminating heavy upfront infrastructure burdens and enabling elastic scaling, cloud-based architectures have captured a dominant share of new implementations. Organizations are no longer choosing between cloud and on-premise as theoretical alternatives; they are weighing total cost of ownership, update cadence, and integration velocity against legacy technical debt. The study dissects this transition across deployment models, highlighting how procurement teams are recalibrating ROI frameworks to prioritize continuous innovation over static license agreements.
Second, labor economics continue to pressure distribution networks worldwide. Chronic workforce constraints, coupled with rising wage expectations and training overhead, have made productivity amplification a non-negotiable requirement. Advanced WMS platforms now deliver measurable throughput improvements and meaningful reductions in operational downtime by orchestrating labor allocation, routing optimization, and real-time task interleaving. These capabilities are no longer treated as optional enhancements; they are embedded into the core value proposition of leading solutions. Our analysis quantifies the operational leverage that modern execution engines provide, enabling leadership teams to model labor risk mitigation against technology investment timelines.
Third, regulatory and compliance expectations are tightening across regulated sectors. Traceability mandates, serialization requirements, and data protection standards are reshaping warehouse compliance from a reactive audit function into a proactive system design principle. Industries handling pharmaceuticals, food, and sensitive consumer goods now require automated batch tracking, audit-ready documentation, and continuous risk management baked into daily operations. The study explores how modern platforms are absorbing these requirements through built-in compliance workflows, reducing manual oversight while maintaining readiness for evolving global standards. For enterprises operating across multiple jurisdictions, this dynamic introduces both complexity and competitive differentiation opportunities that the report examines in detail.
Inside the Study: What Decision-Makers Will Find
This market research is structured to serve both strategic planning and operational evaluation. Rather than offering a superficial survey of vendor offerings, the report delivers a layered analytical framework designed to support purchasing committees, CIO offices, and supply chain transformation teams. The study opens with a comprehensive market overview that maps historical performance against forward-looking projections, establishing a reliable baseline for scenario planning. From there, it progresses into segmentation analysis that disaggregates demand drivers across deployment preferences, end-user industries, and regional adoption patterns. Each segment is evaluated not merely by size, but by structural growth catalysts, adoption barriers, and technology readiness levels that influence procurement timing.
A dedicated competitive landscape module examines the positioning, capability maturity, and strategic maneuvering of the market's most influential players. The analysis moves beyond feature checklists to assess how leading vendors are orchestrating cloud migration, automation integration, and ecosystem expansion. Readers will find executive profiling that connects corporate strategy with product evolution, revealing where consolidation, partnership, and platform bundling are reshaping buyer options. This section is particularly valuable for organizations conducting vendor shortlisting, as it highlights divergent approaches to omni-channel orchestration, labor management, returns handling, and cross-functional integration with transportation and enterprise resource planning environments.
The operational dynamics portion of the study connects technology capability with real-world execution outcomes. It addresses how modern WMS environments are converging with warehouse control systems, execution software, and distributed order management to eliminate planning silos and improve end-to-end visibility. The report also evaluates integration complexity, data governance requirements, and the growing importance of security architecture in multi-tenant cloud deployments. By framing these considerations within procurement and implementation contexts, the study equips leaders with the language and structure needed to translate technical specifications into business-case justification.
To support practical decision-making, the research includes actionable frameworks for evaluating total cost of ownership, assessing cloud migration readiness, and aligning platform selection with industry-specific compliance demands. Case-driven observations illustrate how organizations across retail, manufacturing, food and beverage, healthcare, and third-party logistics are deploying execution technology to resolve fulfillment friction, improve inventory accuracy, and scale without proportional headcount growth. These insights are presented with enough depth to inform internal benchmarking while preserving the strategic objectivity required for unbiased vendor evaluation.
Competitive Landscape: Signals from the Market's Core Players
The vendor ecosystem surrounding omni-channel and warehouse management systems is characterized by both intense competition and rapid structural evolution. A small group of established enterprise platforms continues to anchor significant market share, while a broader field of specialized and regional players competes on implementation agility, industry-specific workflows, and Total cost of ownership. The study maps this landscape through a careful examination of strategic positioning, product architecture, and recent market activity that signals where the industry is heading.
Among the most influential enterprise vendors, Manhattan Associates has maintained a prolonged record of recognition for its cloud-native Active Warehouse Management approach, which emphasizes simultaneous order streaming across wholesale, retail, and direct channels alongside real-time visibility and labor optimization. Its continued leadership positioning, reinforced by high-profile deployments and recurring analyst acknowledgments, reflects a strategy centered on unified omni-channel execution and deep integration with transportation and distribution operations. Blue Yonder has pursued a complementary trajectory, pairing mature warehouse management functionality with workforce performance tools, returns management, and AI-driven orchestration designed for complex distribution environments. Together, these two platforms illustrate how leading vendors are expanding beyond task-level execution into predictive, network-aware fulfillment orchestration.
Large enterprise software ecosystems also remain pivotal. SAP SE continues to leverage its Extended Warehouse Management capability as an integral component of broader supply chain and ERP architectures, appealing to organizations that prioritize tightly coupled inventory control, resource optimization, and cross-docking within a unified enterprise environment. Oracle Corporation pursues a similar integration advantage through its cloud-based warehouse management offerings, embedding mobile capabilities, labor management, and omni-channel support into wider ERP and supply chain platforms. For enterprises already committed to these ecosystems, the strategic question is rarely whether the platform can manage warehouse operations, but how seamlessly it orchestrates them alongside finance, planning, and customer-facing systems.
Infor maintains a strong presence as a cloud-based tier-1 solution provider with particular resonance in manufacturing, distribution, retail, and food and beverage contexts. Its emphasis on inventory optimization, labor management, and third-party logistics capability positions it as a versatile execution platform for organizations seeking industry-tailored functionality without sacrificing cloud scalability. Körber Supply Chain, now operating under its Infios brand following a 2025 rebranding, has simultaneously consolidated its WMS portfolio with warehouse control systems and broadened its execution suite through the acquisition of a transportation management provider. This move reflects a wider industry pattern: vendors are actively reducing planning silos by merging warehouse execution with transportation visibility, enabling more coherent end-to-end supply chain control.
Beyond the entrenched enterprise leaders, a diverse set of specialist and mid-market vendors continues to shape buyer options. Made4net focuses on web-based, cost-effective implementations built on widely understood technology stacks, targeting small-to-mid-sized manufacturers and distributors that value inventory accuracy and labor productivity without enterprise-level complexity. Softeon emphasizes advanced distribution and omni-channel execution with strong integration flexibility for complex warehouse environments. Tecsys brings enterprise-grade execution capabilities with notable relevance in distribution and healthcare, where traceability and controlled handling are especially critical. Deposco has carved a cloud-native niche tailored to third-party logistics providers, bundling distributed order management, planning, and billing on a multi-tenant platform designed for omni-channel scale.
Worldwide Omni-channel and Warehouse Management Systems Market
International participants further diversify the competitive field. Mecalux offers multichannel fulfillment and space utilization optimization through its Easy WMS platform, while Generix Group and Logistics Reply serve manufacturing, wholesale, retail, and 3PL contexts with execution software oriented toward omni-channel process maturity. Hardis Supply Chain has expanded its footprint through SaaS-based warehouse control, omni-channel order orchestration, and in-store logistics capabilities, including recent North American expansion supported by automation partnerships and a strategic transformation agreement with a global retailer. These movements illustrate how regional strength, automation alignment, and channel-specific logistics are becoming decisive differentiators in a market where feature parity alone no longer guarantees competitive advantage.
Recent industry activity reinforces the sense of accelerating consolidation and platform expansion. The completion of a major transportation management acquisition by Körber Supply Chain Software signals a deliberate push toward integrated planning across warehouse and transport domains. Meanwhile, product launches in cloud-based warehouse execution software and sustained recognition of market leaders reflect a broader shift toward real-time orchestration of picking, routing, and order management. For procurement and strategy teams, these developments matter because they reshape integration expectations, expand platform scope, and alter the cost and complexity of multi-vendor architectures. The study synthesizes these signals into a coherent competitive map, enabling readers to anticipate vendor roadmaps rather than merely react to them.
Watching the Structural Shifts Reshaping the Market
Beyond vendor activity and segment sizing, the study pays close attention to the structural dynamics that will determine which organizations capture value from warehouse technology investments and which merely incur cost. Cloud adoption continues to dominate implementation discussions, not simply because of lower upfront capital demands, but because elastic scalability, continuous updates, and reduced maintenance overhead change how IT and supply chain teams plan for growth. At the same time, compliance pressure is intensifying across regulated industries. Detailed batch and serial tracking, automated audit readiness, and stringent data protection controls are becoming baseline expectations rather than premium add-ons. The report examines how these requirements influence platform selection, especially in pharmaceutical, food, and healthcare environments where operational failures carry both financial and reputational risk.
Labor dynamics further complicate the investment calculus. With distribution networks facing persistent workforce challenges, the ability of a WMS to improve throughput and reduce downtime has become a direct contributor to operational resilience. The study frames advanced execution capabilities as a strategic lever for mitigating labor volatility, emphasizing that technology evaluation must now account for productivity outcomes alongside functional coverage. Data security and information governance also occupy a more prominent place in procurement criteria, as cloud and SaaS deployments require controlled access, robust audit trails, and continuous risk management. These factors are no longer peripheral concerns; they are integral to the credibility of any warehouse technology investment.
Positioning Your Organization for the 2032 Outlook
The most valuable insight in this study is not any single statistic, but the structured understanding it provides of how market forces will interact over the next several years. The forecast period extends well beyond the immediate procurement cycle, allowing leadership teams to model technology roadmaps against evolving fulfillment expectations, regulatory milestones, and competitive pressure. Organizations that treat WMS and omni-channel orchestration as static tooling risk being outpaced by those that align platform strategy with continuous orchestration, automation readiness, and compliance-by-design architecture. The research offers the analytical backing needed to make that alignment deliberate rather than reactive.
For enterprises evaluating platform migration, vendor consolidation, or greenfield implementation in 2026, the complete study delivers the depth required to move from high-level direction to confident execution. It combines market sizing, segment intelligence, competitive profiling, and operational context into a single decision-support resource calibrated for strategic planning. Readers who require the full breakdown of market projections, deployment trends, end-user dynamics, regional patterns, and vendor comparisons will find the complete dataset and analytic framework available through the published research. In a market expanding at this pace, the advantage belongs to those who replace assumption with evidence, and the study is built to make that transition possible.
For detailed analysis of this topic, please visit the official page: Worldwide Omni-channel and Warehouse Management Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com