

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Moving Table Grinding Machine Market Hits $3.15B in 2025, 4.62% CAGR to 2032

Strategic Outlook on the Worldwide Grinding Machine With Moving Table Market: Navigating 2026 and Beyond
The global manufacturing landscape is undergoing a quiet convergence of precision demands, automation mandates, and capital efficiency pressures. Within this shifting terrain, the worldwide market for grinding machines with moving tables stands as a critical enabler of high-tolerance component production. Our newly published research tracks this segment from 2020 through a ten-year forecast window ending in 2032, offering a granular, decision-ready map for executives navigating procurement, capacity planning, regional expansion, and technology investment. Grounded in 2025 as the base year, the analysis captures a mature but structurally evolving market, where incremental growth compounds into meaningful strategic advantage when paired with disciplined market intelligence.
A Decade of Measured Expansion: Market Trajectory and Structural Signals
The market has demonstrated a consistent upward trajectory across the historical review period, reflecting the steady replacement cycle of precision machining capacity and the incremental adoption of moving-table configurations that enable multi-axis handling, reduced setup changeover, and improved surface integrity. By the close of the forecast horizon, the market is projected to surpass the four-billion threshold in USD millions, a milestone that underscores both the durability of core industrial demand and the compounding effect of modernization investments. The compound annual growth rate of approximately 4.62 percent frames a market that is expanding at a pace faster than population-driven consumption but slower than speculative technology cycles, making it a textbook case of structurally supported, capex-sensitive growth.
This trajectory is not uniform in its drivers. The historical years reveal how production backlogs, supply chain recalibrations, and regional manufacturing rebalancing shaped purchasing behavior. In the forward window, the growth path is increasingly influenced by equipment lifecycle economics, labor availability, and the accelerating digitization of shop floors. Our forecast model integrates these variables to illustrate how revenue concentration, replacement demand, and technology upgrades will interact over the depreciation cycles of installed base assets. For strategic planners, the key takeaway is that growth in the period ahead will be earned through timing, configuration selection, and the ability to align machine capabilities with rising tolerances and unattended-operation expectations.
Report Architecture: Operational Intelligence for Decision Makers
The study is constructed to translate market behavior into procurement and investment decisions. It maps the competitive terrain, tracks structural shifts, and isolates the variables that determine return on equipment investment. Below is a structured overview of the analysis framework:
- Core market sizing and multi-year forecasting anchored to a 2025 baseline, with explicit linkage to replacement cycles and capacity utilization patterns
- Technology configuration evaluation that distinguishes moving-table architectures from alternative grinding setups, including throughput implications and precision pathway comparisons
- Competitive profiling of leading OEMs and their strategic positioning, product differentiation, and regional presence
- Macro and micro demand drivers, including raw material cost exposure, sustainability mandates, and Industry 4.0 adoption curves
- Strategic implications for capacity planning, after-sales service design, and distributor/manufacturer collaboration models
Each section is designed to feed directly into capital allocation discussions, RFP design, and regional entry or partnership evaluation. Rather than stopping at descriptive trends, the report isolates the decision points that determine which investments outperform over a seven-year horizon.
Gear Grinding Machine Market
Who Moves the Table: Competitive Landscape and Strategic Profiles
The competitive set in this market is defined by a blend of European precision heritage, Asian scale and speed-to-market, and regional specialists capable of serving heavy-industry and niche tolerance requirements. Market concentration data indicates that the top three players account for a meaningful but not dominant share, while the top five approach a near-majority position, signaling a landscape with strong incumbents and continuing room for targeted differentiation. This structure matters: it implies pricing discipline in mainstream configurations, yet significant latitude for technology-led differentiation in heavy-duty, high-precision, and hybrid-operation segments.
Danobat has built a notable profile around hybrid operations that combine grinding with hard turning, milling, boring, and drilling in a single setup, supported by hydrostatic bearings and sub-micron precision on large workspace envelopes. This configuration philosophy reduces part handling and accelerates complex component throughput, an increasingly valuable attribute as manufacturers seek to compress process steps. In early 2026, a precision gear manufacturer expanded its capabilities by adding a Danobat universal OD configuration, illustrating how moving-table platforms are being adopted as enabling nodes in specialized production cells.
Worldwide Grinding Machine With Moving Table Market
Herkules continues to anchor its positioning around roll grinding with traveling table and traversing saddle designs, emphasizing large-roll handling, automatic loading and unloading, and steady-rest integration. For segments where workpiece size and rotational stability define capability requirements, this architectural focus translates into durable competitive advantage. Meanwhile, the Robbi Group provides universal CNC/PLC cylindrical platforms with hydrodynamic spindles and robot integration pathways, aligning with the broader move toward flexible, programmable cells. Morara’s MH series extends this logic to external and internal cylindrical work, including heavy-duty applications such as railway axles, while HMT Machine Tools contributes horizontal spindle reciprocating table CNC surface grinding platforms designed for rigid, programmable axis control in flat and profile applications.
JTEKT Machinery brings high-production precision with configurations compatible with moving-table principles, supporting throughput-sensitive environments. In Italy, Gioria, AZ, and Grinding Technology’s Morara presence reinforce a regional strength in conventional and CNC table-moving cylindrical designs, including hydraulic and controlled variants with high payload capacities. Across southern Europe, these players demonstrate how configuration specialization and application-specific tuning create defensible niches. LGB Scop supplies surface grinding platforms with moving table configurations for industrial use, while Dowell Machine contributes rotary table surface grinders built on high-quality castings, offering vertical spindle variants adaptable to precision requirements. Kehren focuses on high-precision surface grinding with rotary tables and vertical/horizontal spindle orientation, emphasizing creep feed and profile grinding systems. UNITED GRINDING, through its MÄGERLE lineage, offers large-diameter rotary table centers with substantial load capacity, addressing heavy turbine and coupling components with hydrostatically mounted tables.
Strategically, the field is less about a single dominant playbook and more about configuration-to-application fit, service ecosystem depth, and the ability to reduce integration friction for end users. Our report profiles these players not simply to list strengths, but to surface where each is most likely to win, where substitution risk is highest, and how procurement teams can use competitive spacing to negotiate capability and service terms.
Forces Shaping the Next Cycle: Dynamics, Materials, and Manufacturing Mandates
The market’s forward movement is being shaped by overlapping forces that influence both demand timing and equipment economics. Industry 4.0 integration is steadily shifting grinding platforms from isolated workstations toward connected assets with predictive maintenance capability, optimized cycle control, and improved resource efficiency. In parallel, energy efficiency mandates and sustainability initiatives are nudging manufacturers toward designs with lower power consumption and more effective cooling architectures. On the shop floor, automation and smart factory trends, including digital twins and connected CNC systems, are accelerating fleet modernization for unattended operation and higher repeatability.
These dynamics intersect with material cost realities. Iron prices in early 2026 reached levels that directly affect the cost base of cast iron and steel structures used in machine beds and tables, while global scrap price movements across regions have influenced recycled steel supply for machine frames. For capital equipment buyers, this translates into a more variable cost environment where lead-time planning, specification choices, and service-part inventories must be managed with greater foresight. The research integrates these inputs to help manufacturers evaluate total cost of ownership rather than sticker price alone, especially when comparing moving-table configurations with alternative architectures.
Beyond cost, regulation and labor dynamics are altering the value proposition of moving-table designs. Where skilled labor availability is constrained, the appeal of configurations that reduce setup complexity and enable programmed handling increases. Where tolerance requirements tighten in aerospace, defense, medical device, and automotive applications, the precision pathway offered by stable table mechanics and controlled wheel movement becomes a competitive differentiator. The report synthesizes these signals into a demand-side narrative that explains where growth will concentrate and which buyers are most likely to accelerate replacement or expansion spending.
Where Precision Meets Volume: Application Realities and Demand Concentration
The demand base spans multiple industrial ecosystems, each with distinct tolerance requirements, batch profiles, and capital cycles. General machinery and automotive sectors represent substantial portions of end-user demand, driven by high-volume component production and recurring replacement of worn or precision-degraded surfaces. Aerospace and defense applications contribute a structurally important layer, where tighter tolerances, material complexity, and longer procurement cycles elevate the strategic value of capable grinding platforms. Medical device manufacturing, though smaller in relative scale, reflects a demand segment that prioritizes surface integrity, repeatability, and contamination-controlled processes.
These application profiles matter because they shape not only which machines are purchased, but how they are specified, serviced, and integrated into production cells. A moving table can change changeover times, part orientation flexibility, and wheel-to-workpiece engagement consistency. Our analysis examines these operational consequences without reducing them to oversimplified generalizations, allowing procurement and engineering leaders to map application requirements to configuration strengths with greater precision.
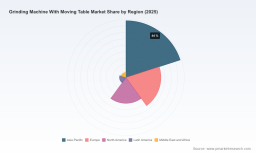
Regionally, demand is distributed across established industrial centers and emerging capacity hubs, with Asia Pacific representing the largest share of market activity, followed by Europe and North America. This distribution reflects the interplay of installed base age, local manufacturing intensity, and the pace of modernization. Because regional dynamics are heavily influenced by local labor conditions, energy costs, and supply chain structure, a single global growth figure is insufficient for operational planning. The study provides the regional context needed to interpret where investment timing is favorable, where service coverage matters most, and where local partnerships can reduce integration risk.
Translating Forecast Into Action: Strategic Implications for 2026 and Beyond
For executives planning the 2026 decision cycle, the most valuable use of this research is not simply to confirm that growth will continue, but to determine how to position for it. The forecast period to 2032 reveals a market that rewards discipline in three areas: timing, configuration selection, and ecosystem readiness.
- Timing: Replacement cycles interact with macroeconomic signals, raw material volatility, and technology adoption curves. Companies that align procurement with credible capex windows can reduce cost exposure and capture capability upgrades at optimal points in the cycle.
- Configuration selection: Moving-table architectures are not universally superior, but they offer distinct advantages in applications requiring reduced handling, improved surface consistency, and programmable axis control. Matching configuration to application profile is central to achieving the intended return on equipment investment.
- Ecosystem readiness: Automation, Industry 4.0 integration, and service coverage increasingly determine real-world performance. Buyers benefit from evaluating not only the machine but the software interfaces, maintenance model, and training path that determine uptime and repeatability.
These implications extend beyond purchasing. For manufacturers, the study informs product roadmap priorities, where hybrid capability, heavy-duty payload capacity, and energy-efficient design are most valued. For distributors and service providers, it identifies where coverage gaps create competitive openings and where regional density strengthens account retention. For investors and strategists, it clarifies where concentration remains limited and where application-specific differentiation can sustain margin resilience.
Why This Study Matters Now: The Case for Actionable Intelligence
A market growing at a steady but not spectacular pace can still generate disproportionate strategic outcomes for organizations that understand its internal structure. The difference between reacting to demand and shaping it lies in the quality of intelligence available at the point of decision. Our Worldwide Grinding Machine With Moving Table Market report is built to provide that intelligence: a forecast framework, competitive mapping, application context, and dynamic drivers that together support capital planning, vendor evaluation, and regional strategy.
To access the complete segmentation detail, regional breakdowns, competitive positioning tables, and forward modeling, request the full study through our official research portal. The source page contains the full intelligence set required to translate these strategic themes into procurement specifications, investment memos, and market-entry evaluations. In a market where configuration fit, service depth, and timing determine outcomes, complete data is not a luxury; it is the foundation of durable advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Grinding Machine With Moving Table Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com