

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Global Memory Packaging Market to Reach $74.38B by 2032 at 10.53% CAGR

Navigating the Next Wave: Why the Worldwide Memory Packaging Market Report Is Essential for 2026 Strategic Planning
The Capacity Crunch and the Strategic Imperative for Precision Intelligence
The global memory packaging industry stands at a critical inflection point. As semiconductor architectures grow increasingly complex and demand for high-performance computing, artificial intelligence workloads, and high-bandwidth memory accelerates, the packaging layer has evolved from a commoditized backend process into a decisive competitive differentiator. For executives navigating 2026, understanding the precise contours of this market is no longer optional. PW Consulting's latest Worldwide Memory Packaging Market research delivers a comprehensive, forward-looking intelligence framework designed specifically to inform capacity planning, supply chain positioning, and technology roadmapping.
Over the historical window from 2020 through 2025, the worldwide memory packaging market expanded from approximately 24.15 billion USD to over 36.90 billion USD. This growth trajectory reflects sustained capital allocation, technology transitions, and shifting demand patterns across enterprise, consumer, and high-performance computing segments. Looking ahead to the 2026-2032 forecast period, the market is projected to maintain a compound annual growth rate of 10.53 percent, climbing toward a 74.38 billion USD valuation by the close of the decade. These macroeconomic indicators signal a resilient, high-growth environment, but they also mask underlying segment divergence, regional capacity constraints, and technology migration dynamics that will dictate winners and losers in the years ahead.
The strategic urgency stems from a confluence of operational pressures. In early 2026, leading memory packaging and testing companies announced price adjustments of up to 30 percent, driven by sustained tight supply conditions for DRAM and NAND packaging services. Simultaneously, design wins and outsourcing ramps for advanced memory architectures are reshaping how original equipment manufacturers allocate capacity. Major players are increasingly relying on outsourced semiconductor assembly and test partners to scale production without bottlenecking internal manufacturing lines. This transition amplifies the importance of understanding which regions, packaging technologies, and memory types are driving growth, and which OSAT ecosystems are best positioned to absorb surging demand.
What the Report Delivers: Operational Intelligence for Executive Decision-Making
This Worldwide Memory Packaging Market study is structured to translate high-level market momentum into actionable intelligence. Rather than offering static snapshots, the research provides a dynamic framework that executives can deploy across multiple strategic functions: capacity planning, vendor selection, technology investment, geographic expansion, and competitive positioning. The following components define the operational value of the report.
Worldwide Memory Packaging Market
The analysis begins with a rigorous historical reconstruction spanning 2020 through 2025, establishing a baseline that accounts for cyclical semiconductor demand, supply chain disruptions, and technology transitions. From that foundation, the report extends into a detailed 2026-2032 forecast, providing granular projections that capture how shifts in memory architecture, advanced packaging adoption, and regional capacity utilization will reshape the market landscape. Every projection is anchored to observable supply-side and demand-side indicators, ensuring that strategic planners can validate assumptions against real-world operational signals.
- Historical revenue reconstruction from 2020 to 2025, contextualizing past cycles and identifying inflection points that inform forward-looking assumptions
- Five-year forecast projections from 2026 through 2032, capturing steady-state growth dynamics alongside technology and capacity transition effects
- Technology segmentation analysis covering traditional wire bonding, flip-chip architectures, TSV and 3D stacking, and fan-out and WLCSP approaches, with emphasis on adoption trajectories and value migration
- Memory type analysis examining DRAM, NAND flash, and emerging memory categories, highlighting how workload trends and product roadmaps influence packaging requirements
- Regional capacity and demand mapping that identifies where manufacturing concentration, supply resilience, and market growth intersect
- Competitive landscape profiling of leading OSAT operators, technology differentiators, and pricing strategies shaping procurement and partnership decisions
- Policy and regulatory monitoring that tracks export controls, tariff implementations, critical material licensing, and industry association advocacy efforts affecting supply chain design
Industry Dynamics Shaping the 2026 Landscape
Modern memory packaging strategy cannot be separated from the broader operating environment. Three structural forces are redefining how companies plan, invest, and compete. The first is supply-side tightness and pricing volatility. Throughout early 2026, multiple packaging and testing providers adjusted pricing upward in response to constrained DRAM and NAND packaging capacity. These adjustments reflect not merely cyclical tightness, but structural shifts in demand concentration, qualification lead times, and the capital intensity of advanced packaging lines. For procurement leaders and supply chain planners, the implication is clear: historical price benchmarks no longer apply, and multi-source visibility becomes a strategic asset.
The second force is technology migration and advanced packaging acceleration. As workloads in artificial intelligence, high-performance computing, and cloud infrastructure push memory performance boundaries, packaging architectures are evolving rapidly. Traditional wire bonding continues to serve established product families, but value growth increasingly concentrates in flip-chip configurations, TSV-enabled 3D stacking, and fan-out or WLCSP formats that support smaller form factors and improved electrical characteristics. The report dissects how these technology pathways are gaining traction, where capacity bottlenecks are likely to emerge, and which memory types are driving the most significant architectural shifts.
The third force is geopolitical and regulatory complexity. Recent policy developments have introduced new dimensions of risk and opportunity. The U.S. government has implemented tariff measures on certain advanced computing chips while maintaining export controls affecting advanced semiconductors, high-bandwidth memory, and DRAM. These controls intersect with licensing requirements that affect specific facilities and supply routes, particularly in China. At the same time, upstream material dynamics are intensifying, with export controls and licensing frameworks on critical minerals creating ripple effects through packaging material supply chains. Industry associations are advocating for plurilateral trade frameworks and critical mineral agreements, recognizing that supply chain resilience will increasingly depend on diversified sourcing and coordinated policy engagement.
Beyond these macro forces, recent developments provide concrete signals of how the market is evolving in real time. A major materials engineering company announced a long-term research and development partnership focused on advancing packaging innovations for next-generation DRAM and high-bandwidth memory, signaling deep investment in technology co-optimization. At the same time, outsourcing momentum continues to reshape capacity flows. A significant memory manufacturer's DDR5 outsourcing ramp is influencing packaging trajectories through 2026, with increased reliance on external partners for memory packaging capacity. These developments illustrate how collaboration, outsourcing, and capacity reallocation are becoming central features of the industry's operating model.
Competitive Landscape: Where Capability Meets Scale
The memory packaging market is characterized by a concentrated yet dynamic competitive field. The industry exhibits meaningful consolidation, with a small group of leading operators commanding a substantial share of total market revenue. This concentration reflects the scale economics of advanced packaging lines, the strategic importance of long-term customer relationships, and the technical qualification cycles that raise barriers to entry for new participants. Yet within this concentrated structure, differentiation remains sharp, with capabilities spanning testing, advanced packaging, high-volume memory module assembly, and specialized process expertise.
Leading operators such as ASE, Amkor, Powertech Technology, and ChipMOS have built comprehensive ecosystems serving DRAM, NAND, and advanced memory formats. Their positioning reflects decades of process refinement, capacity expansion, and close alignment with memory manufacturer roadmaps. Other significant players, including Hana Micron, Lingsen Precision Industries, Formosa Advanced Technologies, and Tianshui Huatian Technology, contribute specialized packaging and semiconductor assembly capabilities that support regional demand and niche product families. In parallel, large-scale OSAT operators such as JCET, King Yuan Electronics, TongFu Microelectronics, and STATS ChipPAC continue to expand their memory packaging portfolios, with some leveraging decades of experience in high-volume NAND and DRAM production for leading OEMs.
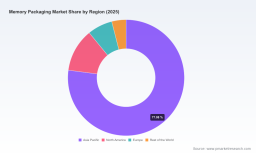
Regional distribution of capabilities further shapes competitive dynamics. Asia Pacific dominates total market value, reflecting the concentration of memory manufacturing, packaging infrastructure, and downstream electronics demand. North America, Europe, and the rest of the world represent meaningful but comparatively smaller shares, each influenced by distinct technology demand patterns, trade flows, and local capacity constraints. For companies evaluating partnerships, outsourcing strategies, or geographic expansion, understanding this structural distribution is essential. The report maps these relationships in detail, enabling readers to assess where capacity is available, where risk is concentrated, and how competitive intensity may shift as demand evolves.
Why This Research Matters for 2026 Decision-Making
In a market defined by rapid technology migration, pricing volatility, and heightened geopolitical sensitivity, broad market narratives are insufficient. Strategic leaders need intelligence that connects top-line growth projections to operational reality. This report is designed to do exactly that. It enables memory manufacturers to evaluate outsourcing partners and capacity expansion pathways. It supports OSAT operators in prioritizing technology investments, pricing strategies, and regional footprint decisions. It equips semiconductor equipment and materials suppliers with visibility into packaging adoption trends that influence demand for advanced process technologies. It helps investors and corporate development teams assess competitive positioning, consolidation dynamics, and long-term value migration across technology and geographic segments.
The most critical value lies in precision. Aggregate growth figures indicate a market moving decisively upward, but the real strategic questions are more specific. Which packaging technologies will absorb the majority of new investment? Where will capacity tightness translate into pricing power, and where will excess capacity create downward pressure? How will export controls, tariffs, and critical material licensing reshape sourcing strategies across memory types and end markets? Which competitive relationships will intensify, and which will create new partnership opportunities? These are the questions that determine whether a strategy is reactive or strategically ahead of the curve.
Advanced Packaging Market
To answer them, executives need the complete segmentation logic, historical baselines, regional breakdowns, technology adoption curves, and competitive assessments embedded in this research. The preview offered here is intended to demonstrate analytical rigor and establish a foundation of trust. It is not intended to substitute for the full intelligence framework that underpins strategic planning. Detailed segmentations, market size allocations, regional breakdowns, and company-specific assessments are intentionally reserved for the complete report, ensuring that decision-makers have access to the precision data required to act with confidence.
Access the Complete Intelligence Framework
The Worldwide Memory Packaging Market research offers more than a forecast. It provides a structured, evidence-driven lens through which to interpret technology transitions, supply dynamics, competitive positioning, and regulatory pressures affecting one of the semiconductor industry's most strategically important segments. In an environment where capacity constraints, pricing shifts, advanced packaging adoption, and policy developments are reshaping the competitive battlefield, incomplete information carries real cost.
For executives preparing for 2026 and beyond, the opportunity is to move from surface-level awareness to decision-grade intelligence. The full report delivers the detailed segmentation, historical reconstruction, five-year projections, competitive profiles, and industry dynamics analysis needed to translate market momentum into executable strategy. Explore the complete analysis, review the granular segmentation data, and equip your organization with the insight required to navigate the next phase of memory packaging growth with precision and confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Memory Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com