

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: EMS Market Hits $54.3B in 2025, Poised for 13.52% CAGR Through 2032

Strategic Intelligence for the Decade Ahead: Navigating the Global Power Energy Management System Market in 2026
The global energy landscape is undergoing a structural transformation that rewards precision, foresight, and decisive investment. As utilities, industrial operators, and commercial enterprises confront electrification, distributed resource integration, and grid modernization simultaneously, the power energy management system market has evolved from a supporting infrastructure category to a central strategic asset. Our newly published Worldwide Power Energy Management System Market research synthesizes historical trends, near-term trajectories, and long-term demand drivers into a single actionable intelligence framework. For executive teams planning capital allocation, technology roadmaps, and partnership strategies in 2026, this study functions as a navigational instrument for a market defined by rapid scale, regulatory recalibration, and intensifying platform competition.
The market has demonstrated sustained momentum over the past half-decade, expanding from a base of approximately 29.4 billion USD in 2020 to 54.3 billion USD in 2025. That progression reflects more than incremental growth; it signals a broadening institutional mandate for real-time monitoring, optimization, and automated control across generation, transmission, and consumption environments. Our forecast window extends through 2032, and the trajectory points toward a sustained compound annual growth rate of 13.52 percent. By 2032, the worldwide market is projected to approach 132 billion USD, driven by recurring investment cycles in grid intelligence, industrial efficiency mandates, and the acceleration of data center and electrification load profiles. The implication for decision-makers is clear: energy management is no longer a discretionary upgrade but a foundational layer of operational resilience and regulatory compliance.
This research is structured to convert macroeconomic signals into business-relevant guidance. Rather than presenting isolated figures, the analysis connects growth patterns to the operational realities that executives face when evaluating technology adoption, portfolio positioning, and regional expansion. The study establishes a baseline from 2020 through 2025, then projects forward across the 2026-2032 period, allowing leadership teams to compare historical adoption curves against forward-looking demand scenarios. By anchoring the analysis in real-world deployment logic, the report helps organizations distinguish between temporary market enthusiasm and durable structural demand.
Because the competitive landscape is both consolidated and highly differentiated, the report provides a detailed assessment of the major platforms shaping market behavior. Large multinational vendors continue to anchor the sector, and their strategic positioning reflects distinct value propositions across utility-scale grid control, industrial optimization, building operations, and integrated hardware-software services. Siemens AG remains a central reference point for comprehensive power EMS deployments, particularly where grid control, generation optimization, and renewable integration intersect. Schneider Electric SE leverages advanced power management platforms for electro-intensive facilities, utilities, and grid optimization, emphasizing operational continuity and asset-level visibility. ABB Ltd delivers real-time monitoring and consumption optimization capabilities tailored to power facilities and industrial applications, while General Electric Company and GE Vernova focus on transmission and generation asset monitoring through digital EMS platforms and grid solutions.
The industrial and demand-response segment draws additional strength from Honeywell International Inc., whose energy optimization and efficiency solutions target power and utility sectors with a strong emphasis on operational responsiveness. Eaton Corporation plc supports reliable energy distribution and optimization through branch circuit monitoring and integrated power management systems. Emerson Electric Co. contributes process-oriented EMS capabilities through control platforms designed for generation, transmission, and facility optimization, while Johnson Controls International plc maintains a strong presence in commercial and industrial power environments through energy efficiency, distributed energy resource integration, and building and power EMS solutions. Rockwell Automation Inc. aligns industrial automation with power monitoring and optimization, and Mitsubishi Electric Corporation, Yokogawa Electric Corporation, and Hitachi Energy Ltd extend the competitive field with platforms focused on efficiency, grid integration, control system functionality, and renewable integration.
These vendors do not compete in a vacuum. The research evaluates how platform breadth, software depth, hardware integration, and services capability shape buyer preferences across different end-user environments. The competitive framework is particularly important for 2026 planning, as consolidation pressure, digital service expansion, and local manufacturing investments begin to influence both pricing dynamics and deployment timelines. For example, recent corporate commitments signal how major players are preparing for sustained demand rather than reacting to short-term cycles. Schneider Electric SE, for instance, committed substantial capital toward U.S. factory upgrades and digital service expansion supporting energy management solutions, an indication that supply-chain readiness and service scalability are becoming strategic differentiators. Johnson Controls International plc reported meaningful growth in its building solutions business in North America alongside a large backlog, with performance closely tied to demand for digital energy management services.
Worldwide Power Energy Management System (EMS) Market
The report also examines the competitive fabric through the lens of market concentration. The sector exhibits meaningful but not absolute consolidation, leaving room for specialized deployments, regional service providers, and vertical-specific platforms to compete on integration quality, responsiveness, and domain expertise. This balance matters because procurement decisions increasingly depend on total cost of ownership, interoperability with existing control environments, and the ability to support evolving data and control requirements rather than on headline brand recognition alone.
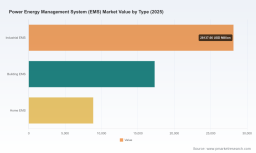
One of the most decisive value drivers in this study is its treatment of market structure. The analysis partitions the landscape across region, solution type, component category, and end-user profile, giving leadership teams the granularity needed to align product strategy, sales coverage, and partnership models with where demand is actually forming. Industrial EMS continues to represent a substantial share of the overall addressable market, reflecting the scale of continuous-process operations, capacity constraints, and efficiency mandates that shape industrial procurement. Building EMS remains a major demand center as commercial and institutional operators prioritize energy performance, operational control, and integration of distributed resources. Home EMS represents a distinct and expanding segment as residential load management, consumer-facing energy visibility, and smart energy ecosystems mature.
From a component perspective, the research explains how software, hardware, and services interact to define deployment economics. Software-centric capabilities increasingly determine platform differentiation, particularly where analytics, automation, and integration with distributed energy resources are required. Hardware remains essential for measurement, control, and physical connectivity, while services support implementation, optimization, and ongoing performance management. The report does not treat these categories as siloed line items; instead, it maps how their interplay affects project scale, margin profiles, and the pace of adoption across different customer environments.
The end-user dimension further clarifies where strategic opportunities are forming. Power and energy organizations remain central users of EMS platforms as grid operators and generation providers seek greater visibility and control. Manufacturing and IT and telecom environments contribute significant demand, reflecting the pressure to manage rising load profiles and maintain operational reliability. Healthcare and residential applications provide additional growth pathways, each with distinct performance expectations, compliance considerations, and deployment patterns. By connecting these segments to operational drivers rather than abstract classifications, the study helps executives identify which customer groups present the most favorable combination of urgency, budget availability, and solution fit.
No strategic assessment of this market would be complete without examining the regulatory and structural forces that are reshaping procurement logic. In 2026, one of the most consequential developments is the update to the National Electrical Code, which relocates and revises the article governing energy management systems and introduces clearer distinctions between EMS and power control system functionality. This change supports safer power-flow-based management of distributed energy resources and alters how integrators, designers, and operators think about system scope, compatibility, and compliance. Parallel to this, the U.S. Department of Energy's virtual power plant update charts a path toward substantial aggregated distributed energy resource capacity by 2030, increasing the requirement for advanced energy management capabilities that can coordinate heterogeneous assets at scale.
Infrastructure planning is also amplifying demand. Grid operators and regional transmission organizations are responding to load growth from electrification and data centers with major transmission expansion initiatives, which in turn raise the value of advanced energy management and grid optimization tools. In parallel, national-level strategies in neighboring markets are reinforcing investment in generation and grid modernization, creating broader regional momentum for energy management capabilities. At the same time, international energy management standards continue to support optimization and efficiency improvement, aligning operational practice with decarbonization and grid modernization goals. Together, these forces create a policy and infrastructure environment in which EMS adoption is being reinforced by multiple, mutually reinforcing drivers rather than by a single regulation or technology trend.
Industrial Energy Management System (IEMS) Market
Recent project-level activity reinforces the direction of travel. Regulatory and system-operator actions are accelerating EMS modernization where mission-critical reliability is at stake. Approved upgrade initiatives intended to strengthen grid operations capabilities illustrate how operators are treating EMS not as a static utility tool but as a continuously evolving operational backbone. Such developments matter because they validate the market's transition from early-stage adoption to expanded deployment in environments where control fidelity, resilience, and interoperability are non-negotiable.
For companies planning 2026 decisions, this report translates those dynamics into strategic questions that leadership teams can act on immediately. Where should capital be directed across software, hardware, and services to maximize competitive advantage? Which customer environments offer the strongest near-term deployment potential, and which require longer maturation? How should organizations prepare for regulatory shifts that change system definitions, integration expectations, and compliance pathways? Which competitive positions are sustainable, and where might platform differentiation erode as digital services and local delivery capabilities become more important?
The study is designed to support those decisions with a comprehensive yet practical architecture. It combines market sizing with qualitative interpretation, competitive profiling with structural analysis, and regulatory context with deployment patterns. Readers can use the report to benchmark internal assumptions, pressure-test expansion plans, and identify the segments and solution attributes most likely to shape procurement behavior over the forecast horizon. Because the market is moving quickly, the research also provides a framework for monitoring the signals that matter most: load growth trajectories, distributed resource coordination requirements, platform virtualization trends, and the growing importance of services-led value creation.
This is an intelligence asset for organizations that need to move beyond generalized market narratives and make decisions with a clear view of scale, segmentation, and competitive intensity. The full report offers the detailed breakdowns, scenario-based interpretation, and company-level insights necessary to convert high-level momentum into concrete strategy. We invite executives, strategy teams, and market planners to access the complete analysis and use it as the foundation for 2026 planning across product positioning, investment prioritization, and partnership design. In a market expanding at this pace, the organizations that outperform will be those that understand not only how large the opportunity is, but where its most defensible value is being created.
For detailed analysis of this topic, please visit the official page: Worldwide Power Energy Management System (EMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com