

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Global Skin Care App Market Hits $450M in 2025, Projected to Reach $876.93M by 2032 with 10.02% CAGR
By pmarketresearch, 2026-09-16
Navigating the Next Wave of Digital Dermatology: Strategic Intelligence for the Global Skin Care App Market
Executive Summary: A Market at the Inflection Point
The global skin care app market stands at a critical juncture, evolving rapidly from a niche convenience into a core component of the broader beauty and wellness ecosystem. As consumer reliance on mobile platforms for personalized care intensifies, organizations must understand not just the current scale of the opportunity, but the drivers that will dictate competitive advantage through the end of the decade. Our latest Worldwide Skin Care App Market research provides the comprehensive intelligence necessary to navigate this complex landscape, offering a detailed roadmap for strategic decision-making in 2026 and beyond.
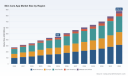
Recent historical performance underscores the momentum behind this digital transformation. Total market revenue has demonstrated consistent upward trajectory, growing from a base of approximately 275.5 Million USD in 2020 to an estimated 450.0 Million USD in 2025. This expansion reflects a fundamental shift in how consumers engage with skincare brands, prioritizing personalized, data-driven interactions over traditional one-size-fits-all recommendations. Our extensive analysis of market dynamics indicates that this growth will continue to accelerate throughout the forecast window, with total revenue projected to surpass 876 Million USD by 2032. This remarkable trajectory corresponds to a Compound Annual Growth Rate of 10.02 percent, a metric that signals robust long-term viability and substantial headroom for innovation-led market participants.
However, navigating this environment requires more than an appreciation of broad scale. The market is becoming increasingly sophisticated, with distinct functional, platform, and regional dynamics shaping delivery models and consumer adoption. The strategic value of our latest report lies in its capacity to dissect these layers, providing enterprise stakeholders with the granular context needed to allocate capital, refine product roadmaps, and mitigate emerging risks. By synthesizing proprietary market modeling with actionable competitive benchmarks, this publication serves as an indispensable tool for guiding high-stakes decisions across product development, strategic partnerships, and geographic expansion.
Deep Dive into Report Methodology and Core Content
Our worldwide market assessment integrates rigorous historical reconstruction with forward-looking forecasting, ensuring that every strategic takeaway is anchored in credible, validated data. The foundational dataset spans a comprehensive evaluation window, establishing reliable baselines while accounting for anomalies, seasonal fluctuations, and structural demand shifts observed across recent years. This meticulous approach allows decision-makers to move beyond speculative projections and base their planning on quantifiable growth pathways.
At the core of the study is an exhaustive segmentation framework that deconstructs market activity along multiple dimensions. Functional utilization patterns are analyzed to reveal how consumer preferences diverge across diagnostic, tracking, consultation, and ancillary solution categories. Platform ecosystems are similarly evaluated, illuminating the competitive interplay between closed and open mobile environments and identifying where monetization potential and user engagement patterns intersect. These layered alignments enable clients to pinpoint precisely where to focus development resources to maximize return on investment.
Geographic dynamics receive equal analytical rigor throughout the publication. Rather than providing static regional snapshots, the report maps demand trajectories, regulatory pressures, and competitive saturation levels across all major territories. This regional intelligence is instrumental for multinational brands calibrating market entry timing, as well as for regional players assessing when and where to expand their digital footprint. Cross-referencing local consumer behavior with macroeconomic indicators yields contextualized growth scenarios that reflect the unique market maturity of each territory.
Beyond structural segmentation, the publication delivers a suite of practical analysis modules designed to translate data into executable strategy. These modules include demand-supply alignment assessments, readiness scoring for emerging technical capabilities, pricing and monetization benchmarking, and risk sensitivity evaluations. Each component is structured to answer the specific operational questions that market leaders, product managers, and investment directors face when allocating limited resources in a fast-moving sector.
The report also features dedicated sections on technology enablement, examining how underlying computational resources, cloud infrastructure, and engineering talent constraints influence go-to-market feasibility. By quantifying the cost and availability parameters surrounding app development and AI model deployment, the analysis equips stakeholders with realistic benchmarks for budgeting and investment planning. This operational transparency is particularly valuable for distinguishing hype from feasible deployment, guiding lean, strategically sound development cycles.
Competitive Landscape and Strategic Positioning in an Expanding Field
The competitive field in the global skin care app market reflects a convergence of pure-play technology developers, legacy beauty conglomerates, pharmaceutical-adjacent skincare specialists, and ingredient transparency platforms. Each category brings distinct strengths and vulnerabilities, and understanding the positioning of leading players is essential to mapping realistic pathways for differentiation. Our report evaluates the strategic footprints of these key entities, providing comparative perspectives on their technological capabilities, ecosystem integrations, and market reach.
Leading technology-focused developers have demonstrated remarkable agility in deploying advanced computer vision and selfie-based diagnostic tools. These firms have built recognizable brands by offering highly visual, interactive experiences that combine aesthetic customization with routine optimization. Their product pipelines increasingly emphasize higher-fidelity three-dimensional facial mapping and tighter integrations with merchandising flows, reflecting a concerted effort to convert diagnostic engagement into commercial conversion.
Major global beauty and personal care corporations have pursued complementary strategies, leveraging acquired or internal capabilities to embed AI-driven skin diagnostics within broader brand ecosystems. By integrating product matching, regimen advice, and virtual consultation functions, these players are positioning their applications as comprehensive skincare companions rather than isolated utility tools. Recent expansion initiatives illustrate how established enterprises are accelerating their digital footprint by adding predictive environmental damage assessments and broadening compatibility across new international markets.
Dermatology-aligned and clinically oriented brands are advancing a different value proposition. Through dedicated routine management applications and health-integrated tracking, these entities emphasize measurable skin-health metrics and longitudinal progress reporting. Recent integrations with established health data ecosystems underscore a growing appetite for seamless data synchronization, allowing consumers to monitor skin trends alongside broader wellness indicators. This convergence of skincare and health data highlights a critical frontier for competitive differentiation, where data continuity and clinical credibility increasingly influence adoption decisions.
Specialized platforms serving ingredient transparency and safety evaluation represent an adjacent but influential force. By empowering consumers to scan labels and assess formulation purity, these applications shape purchasing behavior and raise the standard for product communication. Meanwhile, clinical-grade AI dermatology tools are expanding from professional settings into consumer-facing workflows, focusing on lesion monitoring and early detection. Their rise introduces both opportunity and complexity, particularly as they intersect with evolving regulatory scrutiny around diagnostic claims and medical classification.
Recent corporate developments illustrate the pace of innovation across this field. Prominent deployment of enhanced facial mapping for more precise wrinkle and pore assessment demonstrates sustained investment in analytical precision. Similarly, multi-market expansions incorporating UV damage prediction and broadened product matching capabilities highlight a strategic push toward environmental personalization. At the same time, deeper interoperability with mainstream health platforms signals a broader industry trend toward unified consumer data experiences. These moves collectively indicate that competitive advantage will increasingly depend on the speed and quality of feature iteration, the breadth of ecosystem integration, and the credibility of the underlying diagnostic models.
Regulatory Complexity, Infrastructure Realities, and Market Dynamics
Advances in functionality and competitive intensity must be evaluated alongside the regulatory and operational realities that shape market participation. Governing bodies in key territories are refining the frameworks that apply to AI-enabled skin applications, particularly where diagnostic language, health outcomes, or medical-like claims are involved. In the European Union, certain skin diagnostic tools are increasingly treated as high-risk AI systems, requiring conformity assessments before they can circulate broadly. In the United States, regulatory attention has intensified around consumer-facing applications that purport to detect skin cancer without appropriate clearance. These developments signal that risk management, claim substantiation, and compliance architecture are no longer peripheral concerns but strategic imperatives.
Consumer Skin Care Devices Market
Operational economics introduce further complexity. Engineering talent with relevant skin AI expertise remains in high demand, influencing both development timelines and cost structures. The skilled labor required to build, refine, and maintain diagnostic algorithms carries meaningful expense implications, and this factor increasingly shapes the viability of bespoke development versus platform-based or partnership-driven approaches. Concurrently, the computational resources required to process high-resolution facial imagery and support iterative model training contribute materially to ongoing operating costs. Organizations that fail to internalize these infrastructure dynamics risk underestimating the long-term economics of scaling sophisticated diagnostic features.
Data governance requirements add another dimension of strategic consideration. Regulatory mandates around biometric and facial data storage in certain major markets necessitate localized processing, storage, and consent frameworks for global providers. These constraints affect architecture decisions, market entry sequencing, and partnership models. Companies must therefore balance the desire for centralized data advantages against compliance realities, designing systems that can flex across jurisdictions without sacrificing analytical performance.
Taken together, these factors redefine competitive success. Market leadership will not be determined solely by feature quantity or initial download velocity; it will hinge on a combination of compliance readiness, scalable engineering execution, credible diagnostic performance, and the ability to integrate cleanly into evolving consumer ecosystems. Strategic agility, therefore, becomes the defining characteristic of resilient market participants.
Strategic Lessons for 2026 Enterprise Decisions
For organizations preparing investment and product decisions in 2026, the implications of these market conditions are clear and actionable. First, product roadmaps must prioritize validated diagnostic accuracy and responsible cadence of feature releases. The most successful applications will be those that align advanced analytics with transparent claims and robust user education, avoiding overpromising while consistently delivering tangible personalization value.
Second, ecosystem integration is no longer optional. Consumers increasingly expect their skincare tools to connect meaningfully with broader health, wellness, and commerce platforms. The ability to synchronize metrics, support longitudinal tracking, and enable frictionless purchasing journeys will differentiate mature applications from standalone utilities. Firms that design for interoperability from the outset are better positioned to capture sustained engagement and repeat monetization.
Third, geographic strategy must be informed by a realistic understanding of local regulatory environments and data sovereignty constraints. Market entries should be sequenced with compliance readiness in mind, and architectural choices should support regional adaptation without compromising central product coherence. A disciplined approach to localization can transform regulatory complexity from a barrier into a competitive moat.
Worldwide Skin Care App Market
Fourth, cost structures require careful modeling. The economics of AI-driven skin applications are influenced by engineering labor intensity and cloud compute requirements, and these variables should be embedded into business case assumptions rather than treated as generic overhead. Scenario planning that accounts for talent availability, model iteration frequency, and usage-based infrastructure charges will produce more resilient investment decisions.
Finally, competitive positioning should be guided by the recognition that collaboration may be as valuable as competition in certain contexts. Partnerships with device manufacturers, health data platforms, and clinical authorities can accelerate credibility, broaden distribution, and improve data quality. In a market where consumer trust in algorithmic recommendations remains paramount, credible affiliations and transparent data practices can provide meaningful differentiation.
Why the Latest Worldwide Skin Care App Market Research Is Essential Reading
Comprehensive intelligence is the foundation of confident strategic action. The worldwide skin care app market is undergoing structural change that affects how value is created, how risk is managed, and how durable advantage is built. Our latest report synthesizes the macro growth framework, the segmentation dynamics, the competitive behaviors, and the regulatory and operational realities that together define the opportunity set for the coming years. By grounding strategic choices in detailed forecasting, verified historical baselines, and context-rich competitive analysis, organizations can move from reactive reaction to proactive positioning.
The market trajectory reflects a market expanding at a steady double-digit pace, supported by durable consumer demand for personalized digital skincare. Yet the granular pathways to success vary significantly depending on product focus, geographic ambition, and risk tolerance. Our analysis connects those pathways to practical decision inputs, helping leaders determine which capabilities to build, which markets to prioritize, and which partnerships to pursue.
Access to the full report provides stakeholders with the complete dataset, the comprehensive segmentation breakdowns, and the targeted strategic frameworks required to translate insight into execution. For enterprises seeking to strengthen their market position, refine product investment plans, or anticipate regulatory and cost pressures, this publication delivers the depth and clarity necessary to guide the next stage of growth. We encourage interested readers to secure the complete Worldwide Skin Care App Market research for their teams and begin aligning strategy with the intelligence that will shape the market through 2032.
For detailed analysis of this topic, please visit the official page: Worldwide Skin Care App Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global ESD Packing Market Hits $5,035M in 2025, Poised for 8.1% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Static: Strategic Imperatives in the Global ESD Packing Market (2026-2032)
Executive Overview
The worldwide electrostatic discharge (ESD) packing market is entering a defining growth cycle. As electronics manufacturing becomes increasingly miniaturized and sensitive, the packaging sector responsible for protecting these components must evolve beyond basic containment. Our latest research, Worldwide ESD Packing Market, provides a comprehensive roadmap for stakeholders navigating this complex landscape between 2026 and 2032.
Based on historical performance from 2020 through 2025, the market has demonstrated consistent resilience. The total revenue is projected to expand from approximately 5,035.0 million USD in the base year to roughly 8,685.19 million USD by 2032. This trajectory represents a compound annual growth rate (CAGR) of 8.1 percent during the forecast period. For strategic planners, this growth is not merely a number; it signals a structural shift in how high-value goods are secured, transported, and regulated globally.
The Macro Landscape: Growth Drivers and Constraints
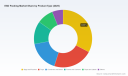
Several converging forces are fueling this expansion. The proliferation of consumer electronics, the relentless demand in semiconductor manufacturing, and the electrification of automotive systems are primary demand engines. However, growth is not uniform. The market is characterized by a moderate concentration level, with the top three competitors holding a combined share of 32.4 percent and the top five reaching 45.85 percent. This fragmentation suggests ample opportunity for niche players while indicating that scaling requires significant operational efficiency or specialized technological advantages.
Supply chain dynamics also play a critical role. Polyethylene (PE) remains the dominant raw material due to its cost-effectiveness and versatility. Yet, reliance on conventional polymers is becoming a liability. The industry is witnessing a pivot toward specialized polymers and conductive fillers, such as carbon black, which inevitably contribute to higher production costs compared to standard materials. Strategic procurement and material innovation are now central to margin preservation.
Worldwide ESD Packing Market
Regulatory Tailwinds and Headwinds
Compliance is no longer a backend function; it is a front-line strategic driver. In the United States, legislative momentum is accelerating. California's SB 54 Plastic Pollution Prevention and Packaging Producer Responsibility Act mandates that producers ensure 100 percent of single-use packaging is recyclable or compostable by 2032. This comes with escalating targets for recycled content and recycling rates. Similarly, Oregon's Plastic Pollution and Recycling Modernization Act has initiated enforcement with producer responsibility fees, and Maryland has recently signed its own packaging EPR law as the sixth U.S. state to do so.
These regulations compel manufacturers to rethink material composition fundamentally. The pressure is not just on end-users but extends through the supply chain to packaging producers. Companies that fail to align their product portfolios with these evolving legal frameworks risk obsolescence or significant penalty costs. Our report dissects these regulatory timelines to help firms anticipate compliance costs and adjust their R&D pipelines accordingly.
Product and End-User Segmentation Dynamics
The market structure is diverse, spanning various physical formats and industry verticals. In terms of product types, solutions range from flexible bags and pouches to rigid trays, containers, boxes, foams, cushions, tapes, and labels. Each format serves specific protection requirements based on the sensitivity of the component and the logistics environment. The shift in demand is visible across these categories, with a notable trend toward solutions that offer both static dissipation and environmental sustainability.
Regarding end-user industries, the demand base is broad. Consumer electronics and semiconductor manufacturing represent significant portions of the addressable market, driven by the need for precision protection during assembly and transport. Automotive electronics and aerospace and defense sectors also contribute substantially, often requiring higher durability and certification standards. Healthcare applications, while smaller in volume, demand strict hygiene and safety compliance alongside ESD protection. Understanding the specific pain points of each vertical is crucial for targeted marketing and product development.
Competitive Landscape and Strategic Movements
The competitive environment is active and innovation-driven. Major players are headquartered across the United States, Europe, and Asia, reflecting the global nature of electronics manufacturing. Key entities such as DESCO Industries Inc., 3M Company, and Sealed Air Corporation provide a wide range of static dissipative and shielding solutions. Meanwhile, large packaging conglomerates like Smurfit Kappa Group and DS Smith plc are leveraging their corrugated and paper-based expertise to develop ESD-safe alternatives for electronics distribution.
Recent developments highlight a clear industry pivot toward sustainability and dual-protection features. In mid-2025, Cortec Corporation launched EcoSonic ESD Paper, offering a sustainable recyclable paper alternative to standard plastic bags with dual ESD and corrosion protection. Similarly, EcoCortec introduced films with post-consumer recycled content, and Daubert Cromwell unveiled poly films combining corrosion inhibition and static dissipation for automotive and aerospace sectors. Weber Verpackungen even introduced what was noted as the world's first ESD Paper Bag as a green alternative. These moves indicate that the next battleground for market share is material innovation that satisfies both safety and environmental mandates.
Regional players are also making strides. Nefab Group continues to emphasize reusable and sustainable systems for logistics across electronics, automotive, and aerospace. Dou Yee Enterprises in Singapore tailors solutions for semiconductor manufacturing, while Teknis Limited and GWP Group in the UK focus on custom conductive and dissipative solutions. The presence of specialized firms like Caltex Plastics, Indepak, and Kiva Container underscores the demand for custom thermoformed and multi-layer packaging that standard off-the-shelf products cannot meet.
ESD Grounding Mats Market
Strategic Value for 2026 Decision-Making
Why does this specific research matter for 2026 planning? Because the margin for error is shrinking. The intersection of regulatory pressure, material cost volatility, and technological requirements creates a complex decision matrix. Companies cannot afford to rely on outdated market estimates or generalized industry knowledge.
Our study provides the granularity needed to model future revenue streams accurately. It analyzes the shifting balance between conventional plastic solutions and emerging sustainable alternatives. It maps the competitive intensity across regions without exposing sensitive granular percentages that would compromise the strategic advantage of early readers. Instead, it offers qualitative insights into where capacity is expanding and where consolidation is likely.
For procurement managers, the report offers context on raw material trends, helping to anticipate cost fluctuations related to conductive fillers and polymer availability. For product developers, the analysis of recent launches provides a benchmark for innovation priorities. For executives, the competitive concentration data informs M&A strategy and partnership opportunities. The goal is to equip leadership with the intelligence required to allocate capital efficiently in a market projected to gain over 3,600 million USD in revenue over the forecast period.
Conclusion: Accessing the Full Intelligence
The Worldwide ESD Packing Market is poised for robust expansion, but realizing value within this growth requires navigating a maze of regulatory changes, material science advancements, and competitive maneuvers. The 8.1 percent CAGR is an invitation, but the path to capturing that growth is fraught with nuances that only deep data can reveal.
This article serves as a strategic preview. To build a fully informed 2026 roadmap, stakeholders need access to the complete segmentation analysis, detailed competitor profiles, and specific regional trajectory data contained within the full report. We invite you to explore the comprehensive findings of our Worldwide ESD Packing Market research to secure the detailed intelligence necessary for decisive action.
For detailed analysis of this topic, please visit the official page: Worldwide ESD Packing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Disposable Surgical Electrodes Market to Hit $2.75B by 2032, 6.48% CAGR
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Global Disposable Surgical Electrodes Market: A 2026 Outlook
The worldwide market for disposable surgical electrodes is entering a decisive phase of expansion, driven by shifting surgical paradigms, stringent infection control protocols, and rapid technological iteration across electrosurgical platforms. As healthcare systems modernize operating room workflows and prioritize single-use instrumentation to mitigate cross-contamination risks, the demand for precision-engineered electrosurgical electrodes has become a critical component of surgical supply chain strategy. This market research report delivers a comprehensive, data-grounded assessment of industry trajectories, competitive dynamics, and regulatory forces shaping the sector through the end of the decade. For executives, procurement leaders, and clinical technology strategists, the findings provide an essential foundation for capital allocation, product portfolio planning, and market entry decisions in 2026 and beyond.
Market Trajectory and Structural Growth Drivers
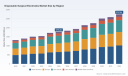
The industry has demonstrated a consistent upward trajectory over the past half-decade, reflecting both volume expansion and value appreciation across global healthcare markets. Historical performance data indicates that the market reached approximately 1,320.5 million USD in 2020, progressing to 1,403.52 million USD in 2021, 1,507.81 million USD in 2022, 1,539.25 million USD in 2023, 1,717.36 million USD in 2024, and 1,770.45 million USD in 2025. This established baseline anchors a forward-looking forecast period spanning 2026 through 2032, during which the market is projected to accelerate under favorable clinical and economic conditions. By 2026, revenue is expected to reach 1,838.53 million USD, followed by progression to 1,934.83 million USD in 2027, 2,144.23 million USD in 2028, 2,254.87 million USD in 2029, 2,512.51 million USD in 2030, 2,589.21 million USD in 2031, and culminating at 2,747.64 million USD in 2032. These projections reflect a compound annual growth rate of 6.48 percent, underscoring the sector's resilience and its alignment with broader minimally invasive surgical adoption curves.
Several macro-level catalysts converge to support this expansion. Surgical volume recovery and growth in ambulatory care centers, coupled with aging demographic profiles in developed economies, continue to elevate procedure frequencies across multiple specialties. Simultaneously, hospital administrators and surgical directors increasingly mandate single-use alternatives to reusable instrumentation, motivated by sterilization overhead, liability considerations, and workflow standardization objectives. The electrosurgical segment benefits directly from these procurement shifts, as disposable electrodes offer consistent performance characteristics, reduced reprocessing burdens, and alignment with modern surgical energy platform ecosystems. Furthermore, incremental innovation in electrode tip geometry, coating technologies, and shaft configurations expands clinical utility, enabling surgeons to perform cutting, coagulation, and ablation with greater precision across open, laparoscopic, and arthroscopic modalities.
Competitive Landscape and Strategic Positioning
The market operates within a moderately concentrated environment, with the top three participants collectively representing 42.15 percent of industry revenue and the top five firms accounting for 56.4 percent. This concentration indicates a landscape where established multinational players maintain strong clinical credibility and distribution infrastructure, while specialized and regional manufacturers compete through cost efficiency, niche procedural focus, and differentiated product features. Understanding the strategic posture of leading companies is essential for evaluating partnership opportunities, competitive threats, and whitespace positioning.
Medtronic, headquartered in Dublin, Ireland, maintains a prominent position through its Valleylab platform, offering PolyHesive corded patient return electrodes alongside a broad suite of electrosurgical instruments and disposable electrodes designed for both open and laparoscopic applications. The company's integrated energy ecosystem and global commercial reach provide significant leverage in institutional procurement frameworks. CONMED Corporation, based in Utica, New York, delivers a comprehensive line of electrosurgical disposables, including pencils, pads, and electrodes such as MacroLyte, SureFit, and ThermoGard dispersive electrodes, addressing the requirements of diverse surgical environments with an emphasis on reliability and procedural versatility.
Johnson & Johnson MedTech, operating through its Ethicon business unit in New Brunswick, New Jersey, supplies electrosurgical devices and disposable electrodes as integral components of its surgical energy portfolio. The company's cross-portfolio integration and strong surgeon relationships enable consistent placement of its electrode solutions across multiple specialties. ERBE Elektromedizin GmbH, located in Tübingen, Germany, manufactures single-use monopolar electrodes spanning spatula, needle, ball, snare, knife, and hook configurations, complemented by electrosurgical pencils with varied shaft sizes and tip geometries tailored for precise cutting and coagulation tasks. Kirwan Surgical Products, LLC, based in Marshfield, Massachusetts, specializes in microsurgical bipolar and monopolar products, including disposable bipolar forceps, pencils, and monopolar suction coagulators and electrodes, serving highly specialized procedural requirements.
Olympus Corporation, with global headquarters in Tokyo, Japan, contributes to the disposable laparoscopic electrode segment, offering specialized solutions such as DTAD electrodes for tonsil and adenoid procedures with monopolar coagulation capability. In the Asia-Pacific manufacturing corridor, Beijing iTrason Technologies produces disposable mini-invasive surgery electrodes and electrosurgical unit electrodes applicable to orthopedic, neurosurgical, arthroscopic, and general use cases. Canwell Medical, based in China, manufactures disposable RF plasma surgical electrodes targeting sports medicine and related applications. Promed, also operating within the Chinese medical device ecosystem, supplies disposable mini-invasive, ENT, laparoscopic, orthopedic, and arthroscopic electrosurgical electrodes for cutting, coagulation, and ablation routines. Hangzhou Valued Medtech Co., Ltd., known commercially as Weide Medical and headquartered in Hangzhou, China, produces disposable electrosurgical hook electrodes and complementary laparoscopic instruments. Progressive Medical Inc., located in St. Louis, Missouri, offers PTFE-coated non-stick disposable electrosurgical electrodes, tips in blade, L-hook, J-hook, and needle configurations, LLETZ tips, and associated pencils and ground pads, emphasizing anti-eschar functionality. Shining World Health Care Co., Ltd., operating from Taiwan as Shinmed, manufactures disposable electrosurgical electrodes in blade, needle, ball, loop, and angled formats, together with pencils and accessories, supporting broad procedural coverage across multiple clinical settings.
Medical Electrodes Market
This diversified field of incumbents, regional manufacturers, and specialty innovators creates a competitive structure in which differentiation increasingly depends on coating performance, tip configuration flexibility, regulatory clearance velocity, and distribution alignment with surgical energy vendors. Companies that can synchronize product development with procedural demand trends and streamline supply chain reliability are best positioned to capture share as the market expands.
Regulatory, Reimbursement, and Operational Dynamics
Market evolution is heavily influenced by regulatory frameworks, safety standards, and reimbursement structures that govern product clearance, clinical deployment, and commercial viability. In the United States, disposable electrosurgical electrodes and related devices, classified under product code GEI, are regulated as Class II medical devices under 21 CFR 878.4400 and typically require 510(k) premarket notification for market clearance. This pathway shapes product launch timelines, competitive sequencing, and the strategic importance of predicate device selection. Recent regulatory activity illustrates the ongoing pace of market entry and innovation. In August 2025, Agnes Medical Co., Ltd. secured FDA 510(k) clearance for its RFMagik electrosurgical device incorporating single-use electrodes for dermatologic and general surgical electrocoagulation and hemostasis. Earlier that year, in June 2025, CnS Medical Co., Ltd. obtained clearance for the DELPHI System, including DELPHI PLUS and DISCORE single-use bipolar electrosurgical electrodes designed for tissue coagulation, ablation, and hemostasis in arthroscopic surgery. Agnes Medical subsequently received clearance in April 2025 for the RFMagik Lite electrosurgical device with single-use electrodes intended for dermatologic and general surgical procedures. More recently, in March 2026, Technomed Europe cleared a new line of disposable concentric needle electrodes for physical medicine and rehabilitation applications.
Worldwide Disposable Surgical Electrodes Market
Beyond premarket clearance, manufacturers must ensure that single-use electrosurgical electrodes comply with IEC 60601-1, IEC 60601-1-2, and IEC 60601-2-2 electrical safety and performance standards, reinforcing the technical rigor required for market participation. Sterilization protocols also constitute a critical operational parameter, as sterile single-use electrodes are typically EO gas sterilized with a three-year shelf life in many cleared devices. These parameters influence inventory planning, logistics design, and hospital procurement cycles. Reimbursement considerations further shape commercial strategy, as electrosurgical procedures utilizing disposable electrodes are billed under various CPT codes depending on specialty, including general surgery, gynecology, and urology. Medicare payments vary according to facility versus physician office settings and incorporate geographic adjustments, requiring manufacturers and service providers to understand coding pathways and payment differentials when positioning products across care environments.
From a materials and performance standpoint, manufacturers increasingly employ PTFE coatings on disposable monopolar electrodes to reduce eschar build-up and improve non-stick performance during surgery. This engineering trend reflects a broader emphasis on procedural efficiency, instrument longevity during a case, and the reduction of intraoperative interruptions caused by electrode fouling. As coating technologies mature and become more widely adopted, they contribute to product differentiation and can influence formulary preferences in high-volume surgical centers.
Segmentation Architecture and Strategic Interpretation
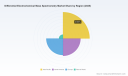
The report maps the market across multiple segmentation dimensions to clarify where revenue concentration, growth momentum, and competitive intensity are most pronounced. Analysis by region captures the relative scale and growth posture of North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, providing context for distribution strategy, market entry timing, and localized regulatory navigation. Product-type segmentation distinguishes among monopolar electrodes, bipolar electrodes, and patient return electrodes, illuminating the differing clinical roles, procedural demands, and commercial characteristics of each category. Procedure-based segmentation further decomposes demand across general surgery, cardiovascular surgery, gynecological surgery, orthopedic surgery, and other applications, enabling stakeholders to align product development and marketing emphasis with the procedural areas generating the strongest consumption trends.
While detailed numerical splits for each region, product type, and procedure are reserved for the full report, the structural composition of the market reveals clear strategic implications. The interplay between segmental demand and competitive positioning suggests that growth will not be uniform; rather, it will be shaped by procedural volume dynamics, specialty adoption rates, and the ability of suppliers to match electrode configurations to specific surgical workflows. Readers seeking precise segment valuations, share estimates, and forward-looking segment projections will find the complete dataset essential for scenario modeling and portfolio prioritization.
What the Full Report Delivers
This market research study is designed to supply decision-makers with a rigorous, operationally useful intelligence framework. The full publication includes historical and forecast revenue analysis, segmentation breakdowns, competitive profiling, regulatory mapping, and strategic recommendations calibrated to the 2026 to 2032 horizon. It integrates primary and secondary research methodologies to triangulate market size, growth pathways, and participant positioning, ensuring that conclusions rest on a defensible analytical foundation. In addition to macro trends, the report examines product development directions, procurement behavior, sterilization and shelf-life considerations, reimbursement context, and the competitive moves that are reshaping market shares. The objective is to equip executives with the clarity required to evaluate expansion opportunities, assess vendor and partner suitability, and anticipate regulatory and technological shifts that will influence purchasing decisions and product roadmaps.
Strategic Value for 2026 Decision-Making
As organizations plan capital deployment, product launches, and market expansion during 2026, access to precise, forward-looking intelligence becomes a competitive necessity. The disposable surgical electrodes market is transitioning from a broadly mature supply environment into a more dynamic landscape characterized by technological refinement, regulatory velocity, and regionally varied growth patterns. Leaders who understand the underlying drivers of demand, the posture of incumbent and emerging competitors, and the operational requirements imposed by safety standards and reimbursement structures will be better prepared to make informed strategic commitments. This report provides that perspective, balancing high-level market direction with the detailed segmentation, company-level profiles, and procedural insights needed to translate market awareness into actionable strategy.
For stakeholders seeking complete segment valuations, regional revenue trajectories, competitive share decompositions, and granular forecast tables across the 2026 to 2032 period, the full report delivers the comprehensive dataset necessary for detailed planning. Accessing the complete analysis ensures that strategic decisions are grounded in the full scope of available evidence, enabling organizations to navigate this growth phase with confidence and precision.
For detailed analysis of this topic, please visit the official page: Worldwide Disposable Surgical Electrodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Differential Electrochemical Mass Spectrometry Market Hits $52.45M in 2025, Surging to $97.43M by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: The Worldwide Differential Electrochemical Mass Spectrometry Market
As the global energy transition accelerates and advanced battery chemistries move from laboratory prototypes to commercial deployment, the analytical tools underpinning electrochemical research are undergoing a structural transformation. Differential Electrochemical Mass Spectrometry has emerged as a critical capability for researchers and industrial R&D teams seeking real-time, quantifiable insight into gas evolution, solid electrolyte interphase formation, degradation pathways, and catalytic surface dynamics. PW Consulting has compiled a comprehensive Worldwide Differential Electrochemical Mass Spectrometry Market study, spanning the base year 2025 and extending through a detailed forecast horizon to 2032. This report is designed to function as a decision-grade intelligence asset, equipping corporate strategists, equipment procurement leaders, technology investment committees, and market entry planners with the structural clarity required to navigate a rapidly consolidating and technically demanding landscape in 2026 and beyond.
The strategic value of this market assessment lies not only in its quantitative trajectory but in its operational mapping of how hardware innovation, workflow integration, and application-driven demand are reshaping procurement behavior across electrochemical research ecosystems. For organizations making capital allocation, vendor selection, partnership, or regional expansion decisions in 2026, the findings provide a disciplined framework to separate genuine technology readiness from marketing narrative, to anticipate integration bottlenecks before they become procurement liabilities, and to calibrate go-to-market or sourcing strategies against where the market is structurally heading rather than where it stood in prior cycles.
A Market in Structural Expansion: From Historical Baselines to 2032 Trajectories
The worldwide differential electrochemical mass spectrometry market has progressed through a consistent expansion arc across the historical observation window. Revenue levels advanced from 33.85 million USD in 2020 to 37.99 million USD in 2021, crossed 38.97 million USD in 2022, and continued upward through 42.68 million USD in 2023 and 48.03 million USD in 2024. The base year 2025 closed at 52.45 million USD, reflecting sustained demand intensification as research organizations expanded electrochemical characterization capacity in response to battery optimization mandates, electrocatalysis program growth, and gas-phase degradation analysis requirements.
The forward trajectory outlined in this study projects continued expansion, with the market reaching 56.11 million USD in 2026, advancing to 64.26 million USD in 2027, 68.0 million USD in 2028, 73.91 million USD in 2029, and 83.77 million USD in 2030. The forecast then proceeds to 89.1 million USD in 2031 and 97.43 million USD in 2032. Across the forecast period, the study documents a compound annual growth rate of 9.25 percent, a rate that signals more than cyclical research spending. It reflects a structural incorporation of differential electrochemical mass spectrometry capabilities into core characterization workflows, where real-time gas and volatile species monitoring is increasingly embedded into experiment design rather than treated as an auxiliary measurement.
For decision-makers in 2026, this growth path carries several strategic implications. First, it indicates that demand is broadening beyond a narrow set of early adopters and that the addressable user base across battery research, fuel cell and electrocatalysis programs, and CO2 conversion and electrolysis investigations is expanding in both depth and organizational diversity. Second, it suggests that procurement timing, integration readiness, and vendor capability assessment are increasingly consequential, because capacity additions made without an understanding of workflow synchronization, membrane interface maintenance realities, and software interoperability can create operational friction that undermines research throughput. Third, the trajectory underscores that the competitive field is consolidating around firms with differentiated hardware platforms, application-tuned configurations, and credible integration ecosystems, making vendor evaluation a strategic rather than transactional exercise.
Report Blueprint: Actionable Intelligence Structured for Decision-Makers
The Worldwide Differential Electrochemical Mass Spectrometry Market study is built to translate market structure into operational guidance. Rather than offering abstract market commentary, the report is organized around the practical questions that R&D directors, procurement leaders, and strategy teams confront when evaluating analytical instrumentation portfolios, assessing supplier options, or planning internal capability expansion. The report content is structured to support evidence-based decision-making across multiple dimensions of the market.
Worldwide High Resolution Mass Spectrometry System Market
Scope Architecture and Analytical Coverage
The study delivers a multi-layered analytical architecture designed to capture both the macroeconomic trajectory and the operational anatomy of the market. Core coverage includes a fully articulated revenue history and forecast series, paired with segmentation analysis that disaggregates demand patterns by region, by system type, and by application context. This segmentation framework is developed not merely as a numerical breakdown but as an interpretive map of how different end-use environments shape purchasing priorities, performance expectations, and integration requirements. The report further incorporates a competitive landscape assessment, an examination of technology and workflow dynamics, and a structured treatment of frequently encountered operational questions that influence procurement and deployment decisions.
Practical Utility for Corporate and Research Strategy Teams
To ensure the study functions as a working reference rather than a static summary, its content is engineered around several categories of actionable insight:
- Documented revenue baselines and forward projections that allow strategy teams to model capacity investments, forecast procurement timing, and align internal roadmap milestones with observable market momentum.
- Segment-level interpretation of how system types and application contexts differ in demand intensity, configuration preferences, and deployment considerations, enabling more precise targeting of product positioning, service packaging, and customer engagement strategies.
- Competitive profiling and landscape mapping that identify where leading providers differentiate through hardware architecture, cell module design, software synchronization, and application-specific configurations, helping buyers and market participants understand relative positioning and integration maturity.
- Technology and workflow dynamics analysis that addresses operational realities such as membrane interface performance and maintenance considerations, standardization needs for potentiostat integration, and laboratory usage context, providing decision-makers with practical context that affects total cost of ownership and research continuity.
- Regulatory and standardization context that clarifies how DEMS instruments are situated within laboratory safety and vacuum system protocols, and what that implies for procurement documentation, compliance framing, and deployment planning in research environments.
- FAQ-oriented guidance that distinguishes research-use laboratory applications from clinical, diagnostic, or production-scale use cases, helping organizations scope expectations, define intended use, and align purchasing decisions with operational reality.
By combining these layers, the report aims to give users a comprehensive yet practical intelligence package. The objective is to enable strategy teams to interpret market movement with sufficient depth to support confident planning, while preserving exclusivity of the detailed segmentation values, regional breakdowns, and company-level performance indicators that constitute the full analytical core of the study.
Competitive Landscape: Differentiated Platforms, Integration Ecosystems, and Emerging Positioning
The differential electrochemical mass spectrometry market is defined by a competitive field in which hardware architecture, cell module design, software synchronization, and application-specific tuning determine commercial positioning. Concentration patterns in the market indicate that a limited set of established participants holds a substantial share of revenue, while specialized providers compete through modularity, real-time data correlation capabilities, and targeted application support. This structure has direct implications for procurement strategy, partnership evaluation, and market entry planning in 2026.
Among the profiled participants, Hiden Analytical, based in Warrington, United Kingdom, offers the HPR-40 DEMS membrane inlet mass spectrometer system for in situ, real-time analysis of gases and volatile species in electrochemical research, covering energy storage, catalysis, corrosion, and advanced materials. Its portfolio incorporates modular ECL Series electrochemical cells, including ECL-Static, ECL-Insight, and ECL-Probe, designed for integration with potentiostats such as BioLogic and Metrohm Autolab. In February 2026, Hiden Analytical highlighted the features of the newly launched ECL Series electrochemical cells for integration with the HPR-40 DEMS, emphasizing the real-time synchronization of electrochemical parameters with mass spectrometric data for gases and volatile species analysis. This development reflects a broader market emphasis on synchronized data correlation between potential or current and mass signals, an integration requirement that is increasingly central to research workflow performance and to buyer evaluation criteria.
Spectro Inlets, headquartered in Denmark, provides the EC-MS Premium system for real-time, quantifiable electrochemical mass spectrometry, with a focus on battery gas evolution, SEI formation, and degradation studies across lithium-ion, sodium-ion, and other battery chemistries. Its positioning illustrates the market’s application-driven differentiation, where the ability to capture and interpret gas-related degradation signatures is becoming a decisive capability in advanced battery research programs.
Liquid Loop, operating in Europe, supplies compact and modular DEMS hardware, including the FlowSys microfluidic system, PoGASi interface, electrochemical capillary cell, dual thin layer cell, and Twin Extractor for gaseous and volatile product separation in electrocatalysis and related applications. Its modular hardware orientation underscores the value that research organizations place in configuration flexibility and application-specific cell design, particularly in electrocatalysis workflows where product separation and interface adaptability are critical to experimental throughput.
Shanghai Linglu Instruments, based in Shanghai, China, manufactures in-situ DEMS systems such as the QAS-100/PrismaPro for battery DEMS and classic DEMS electrochemical cells, supporting electrocatalysis, battery research, and gas evolution monitoring. Its presence reflects expanding manufacturing and application support capacity within Asia Pacific, consistent with the region’s growing role in electrochemical research and instrumentation demand.
From a strategy perspective, the competitive profile of these participants demonstrates that differentiation is increasingly determined by integration readiness, application specificity, and the ability to deliver synchronized, interpretable data streams within laboratory workflows. Buyers evaluating suppliers in 2026 should weigh not only instrument specifications but the maturity of cell modules, software synchronization pathways, and support for the specific electrochemical and gas-phase analyses central to their programs. For vendors and investors, the landscape signals the importance of building defensible positions through integration ecosystems, configurable hardware, and credible application expertise rather than competing solely on base hardware pricing.
Market Dynamics: Hardware Realities, Workflow Integration, and Standardization Context
Beyond revenue trajectory and competitive positioning, the strategic value of this market study depends heavily on its treatment of operational dynamics. Differential electrochemical mass spectrometry is not a commoditized measurement category; it is a laboratory workflow in which hardware interfaces, synchronization requirements, maintenance constraints, and usage context all affect research output and procurement outcomes. The report addresses these dynamics directly so that decision-makers can evaluate options with operational realism.
One important hardware consideration is the membrane interface that enables selective transport of gases and volatile species from the electrochemical cell into the mass spectrometer vacuum environment. This interface is a primary performance and maintenance focal point in DEMS systems, and its susceptibility to failure or clogging in volatile electrolytes creates recurring maintenance obligations that can influence total cost of ownership and experimental continuity. Understanding these constraints is essential for research organizations planning procurement, because system reliability and workflow interruption risks are not always visible in high-level product descriptions but have direct consequences for lab productivity and instrument utilization.
Integration and standardization demands represent another critical dynamic. Connecting DEMS instruments with potentiostats requires standardized cabling and software synchronization to achieve real-time correlation between potential or current and mass signals. As highlighted by recent application documentation involving Metrohm Autolab VIONIC and BioLogic systems, synchronization between electrochemical parameters and mass spectrometric outputs is a defining requirement for advanced experimental workflows. For procurement and strategy teams, this means that integration compatibility, software interoperability, and vendor support for synchronized data capture should be assessed as core acquisition criteria, not secondary conveniences.
Regulatory and standardization context further shapes procurement and deployment planning. DEMS instruments are primarily used for research purposes in laboratory settings under standard electrochemical safety and vacuum system protocols. The study reflects that, beyond general mass spectrometry and electrochemistry guidelines, no specific ISO standards dedicated exclusively to DEMS were identified. This context matters for organizations defining compliance documentation, internal approval processes, and deployment scope, particularly when aligning instrumentation purchasing with broader laboratory safety and operational governance frameworks.
Finally, the study clarifies intended use boundaries. DEMS systems are research-use only laboratory instruments and are not intended for clinical, diagnostic, or production-scale applications. This distinction is strategically important for organizations evaluating market opportunities or internal deployment scenarios, because it frames the commercial and operational boundaries within which these instruments operate. Understanding these boundaries helps prevent misaligned expectations and ensures that procurement, service planning, and market positioning decisions remain grounded in realistic application scope.
Strategic Takeaways for 2026 Decision-Making
The Worldwide Differential Electrochemical Mass Spectrometry Market study is structured to support high-stakes decision-making at a moment when analytical capability, workflow integration, and application-driven demand are converging. For corporate strategists, the market’s sustained growth path and 9.25 percent compound annual rate across the forecast period suggest that differential electrochemical mass spectrometry is becoming a more entrenched element of electrochemical research infrastructure rather than a niche add-on. For procurement and technology leaders, the report’s integration and hardware dynamics emphasize the need to evaluate synchronization capability, membrane interface maintenance implications, and application fit as core purchasing criteria. For competitive strategy and market entry teams, the concentration profile and differentiated positioning of leading providers point to a market where credible integration ecosystems, modular configuration options, and application-tuned support are increasingly decisive.
At the same time, the full depth of the study—its detailed segmentation values, regional and type-based revenue distributions, application-level figures, and company-specific performance analysis—is structured to reward focused engagement. The summary presented here is designed to demonstrate analytical rigor and strategic relevance while preserving the granular intelligence that defines the complete report. Organizations seeking to model procurement scenarios, assess vendor positioning, evaluate market entry timing, or align internal R&D investment plans with evidence-based market structure will find the full study essential to precise planning.
For decision-makers operating in 2026, the central message is that the differential electrochemical mass spectrometry market is expanding in both scale and sophistication. Success in this environment depends on understanding not only how large the market is becoming, but how its hardware realities, integration requirements, application demand patterns, and competitive dynamics are evolving together. PW Consulting’s Worldwide Differential Electrochemical Mass Spectrometry Market study provides the structural intelligence required to navigate that complexity with confidence. To access the complete segmentation breakdowns, forecast detail, competitive analysis, and operational context that underpin these findings, please visit the source page for the full market research release.
Worldwide Differential Electrochemical Mass Spectrometry Market
For detailed analysis of this topic, please visit the official page: Worldwide Differential Electrochemical Mass Spectrometry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Ceramic Wafer Boat Market to Reach $937.53M by 2032 with 8.12% CAGR
By pmarketresearch, 2026-09-16
Navigating the Precision Sector: Strategic Insights into the Global Ceramic Wafer Boat Market Through 2032
The semiconductor equipment supply chain is increasingly defined by the reliability of its consumable components. Among these, ceramic wafer boats serve as a critical interface between the wafer and the processing environment, directly influencing yield, contamination control, and thermal efficiency. As the global industry transitions toward more complex node architectures and higher temperature processing regimes, the demand for advanced ceramic carriers has accelerated. Our latest comprehensive study, the Worldwide Ceramic Wafer Boat Market 2026-2032, offers a granular examination of this evolving landscape, providing decision-makers with the intelligence required to navigate capacity planning, supply chain resilience, and competitive positioning.
This analysis is not merely a retrospective of past performance but a forward-looking strategic tool designed for 2026 corporate planning. With the market having demonstrated steady growth over the historical period from 2020 to 2025, reaching a base valuation of USD 542.8 Million in 2025, the trajectory indicates a robust expansion phase. The forecast period through 2032 projects the market to ascend toward USD 937.53 Million, underpinned by a Compound Annual Growth Rate (CAGR) of 8.12 Percent. Such growth reflects the broader macro trend of expanding semiconductor manufacturing capacity, particularly concentrated in the Asia-Pacific region, where the imperative for high-temperature resistance and chemical stability in wafer processing remains paramount.
Worldwide Ceramic Wafer Boat Market
The Macro Economic Trajectory and Segment Intelligence
Understanding the magnitude of opportunity requires a clear view of the historical baseline and the projected surge. The market has grown consistently from USD 382.4 Million in 2020, navigating supply chain disruptions and geopolitical shifts to achieve consecutive year-over-year gains. By 2026, the market size is anticipated to cross the USD 598.53 Million threshold. This growth is not uniform; it is driven by specific technological imperatives. As logic and memory chips demand tighter tolerances, the material science behind wafer boats becomes a bottleneck and a differentiator.
Worldwide Wafer Boat Market
Our research dissects the market across three primary dimensions: material type, application, and region. While specific regional share percentages and application breakdown amounts are detailed exclusively in the full report to protect client strategic confidentiality, the overarching dynamics are clear. The shift toward Silicon Carbide (SiC) continues to dominate the material landscape due to its superior thermal stability exceeding 1600°C and lower contamination risks compared to traditional quartz alternatives. High-purity quartz remains a viable option for less demanding processes, such as annealing and oxidation up to 1200°C, but the high-performance sector is increasingly favoring advanced ceramics.
Similarly, the application landscape is shifting. Processes such as Diffusion and Oxidation, Chemical Vapor Deposition (CVD), and LPCVD and Epitaxy represent the core consumption drivers. As foundries and integrated device manufacturers push for higher efficiency, the choice of boat material directly correlates with process yield. The report provides a deep dive into how these applications are evolving and which material types are gaining traction within each process flow, without exposing the precise volume splits that could alert competitors during strategy formulation.
Competitive Landscape and Strategic Positioning
The global market for ceramic wafer boats exhibits a moderately concentrated structure, with the top three players holding a combined market share of 48.5 Percent and the top five reaching 62.3 Percent. This concentration suggests that while market leaders maintain significant influence, there remains substantial room for specialized players and regional participants to capture niche value. The competitive arena is diverse, featuring established Japanese and American corporations alongside a robust cohort of Chinese manufacturers who have significantly upgraded their technical capabilities in recent years.
Key incumbents such as Kyocera Corporation continue to leverage their reputation for fine ceramic technology, utilizing high-purity sapphire and advanced ceramics that emphasize plasma and heat resistance with minimal particle generation. CoorsTek, Inc. maintains its status as a global leader in engineered ceramics, providing high-purity options with exceptional thermal and chemical stability suited for high-temperature processes. Ferrotec Corporation supports the ecosystem with quartz and silicon carbide solutions optimized for thermal stability and chemical wear resistance, maintaining operations across key semiconductor hubs in the United States, Japan, and Taiwan.
Simultaneously, the entry and expansion of Chinese manufacturers have reshaped supply dynamics. Companies like Semicorex and Semicera Semiconductor Technology Co., Ltd. specialize in customized silicon carbide coated and SiC ceramic wafer boats, catering specifically to diffusion and oxidation configurations while serving European and American markets. Others, such as 3X Ceramic Parts Company Limited and VeTek Semiconductor, focus on high-temperature resistance up to 1650°C and corrosion resistance, providing viable alternatives for cost-sensitive yet performance-critical applications. Shenyang Starlight Advanced Ceramics Co., Ltd., with over 30 years in SiC solutions, continues to develop recrystallized silicon carbide and quartz boats, recently showcasing their capabilities at the 18th China International Advanced Ceramics Exhibition in January 2026. Gorgeous Ceramic and Hunan DeZhi New Material Co., Ltd. further contribute to the supply base with custom and standard options emphasizing contamination resistance and CVD SiC coated variants.
Recent developments indicate an intensification of innovation. In August 2025, Engineering Ceramic Co., Ltd. introduced recrystallized silicon carbide (RSiC) wafer boats with CVD-SiC coating options in three distinct material types tailored for advanced industries. These moves underscore a competitive environment where material differentiation and coating technologies are becoming the primary battlegrounds for market share.
Regulatory Headwinds and Operational Risks
Strategic planning in 2026 must account for a complex regulatory environment. Export controls on semiconductor manufacturing equipment and related components, including advanced ceramic parts, were refined under the Foreign-Produced Direct Product Rule to address national security concerns in advanced computing and semiconductor production. These regulations introduce potential friction in cross-border supply chains, particularly for companies sourcing high-purity materials or finished components across jurisdictional lines.
The availability of raw materials also remains a critical variable. Silicon carbide serves as the primary core component for high-performance ceramic wafer boats, and fluctuations in the supply of high-grade SiC or the capacity to process it into recrystallized forms can impact production timelines. While high-purity quartz offers an alternative for specific temperature ranges, the industry's migration toward higher performance standards limits its long-term utility in advanced nodes. Decision-makers must evaluate supplier diversification strategies to mitigate these risks, a topic extensively covered in the risk assessment section of our full market study.
Strategic Value for 2026 Decision-Makers
Why does this specific market intelligence matter for your organization in 2026? The answer lies in the intersection of CapEx planning and operational continuity. As the market grows from USD 598.53 Million in 2026 to over USD 900 Million by 2031, the demand for reliable wafer carriers will intensify. Procurement teams need to know which suppliers are scaling capacity and which are focusing on niche high-margin products. R&D departments need to understand the material science trends that will define the next generation of process compatibility.
This report serves as a blueprint for these decisions. It allows stakeholders to benchmark their current supplier base against the competitive landscape, assess the viability of vertical integration versus outsourcing, and identify emerging markets where capacity expansion is outpacing local supply. By understanding the concentration dynamics and the specific technological roadmaps of key players like Kyocera, CoorsTek, and the expanding cohort of specialized Chinese manufacturers, companies can negotiate better terms, secure long-term supply agreements, or identify M&A targets.
What the Full Report Delivers
While this overview provides the strategic context, the full Worldwide Ceramic Wafer Boat Market 2026-2032 study contains the actionable data required to execute these strategies. The document includes comprehensive segmentation analysis that breaks down revenue and volume trends across all major regions and application verticals without the noise found in aggregate industry reports. It provides a detailed company profiling section that examines the financial health, production capacity, and strategic moves of the key market participants listed above.
Furthermore, the report includes a thorough analysis of market dynamics, covering drivers, restraints, and opportunities with specific attention to the regulatory landscape and raw material supply chains. The forecast model offers multiple scenarios, allowing clients to stress-test their assumptions against varying rates of semiconductor capex deployment. Customization options are available for those who require deep dives into specific countries, material grades, or downstream semiconductor applications.
In an industry where precision is everything, relying on aggregate data is insufficient. The ceramic wafer boat market is a critical enabler of semiconductor processing, and its nuances dictate the efficiency of the entire fabrication line. We invite you to access the full report to secure the detailed intelligence necessary to optimize your strategic position in this high-growth sector. The window to align supply chain strategies with the upcoming cycle of capacity expansion is open now, and the data required to navigate it is available in our complete market study.
For detailed analysis of this topic, please visit the official page: Worldwide Ceramic Wafer Boat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Laminating Lithium-ion Capacitor Market Hits $456M in 2025, Poised for 18.54% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Next Wave: Strategic Intelligence on the Worldwide Laminating Lithium-ion Capacitor Market (2026–2032)
The Strategic Imperative of Laminated Lithium-ion Capacitors
The global energy storage landscape is undergoing a structural shift. Lithium-ion capacitors (LICs) have emerged as a critical bridge technology, combining the rapid charge-discharge capabilities of supercapacitors with the higher energy density of lithium-ion chemistry. Within this category, laminated construction—particularly pouch and flexible-module formats—is rapidly becoming the architecture of choice for next-generation applications that demand slim form factors, scalable manufacturing, and improved thermal management. For executives, investors, and technology strategists, the question is no longer whether laminating LIC technology will scale, but how quickly capital, partnerships, and supply chain positioning must be deployed to capture value.
PW Consulting's latest Worldwide Laminating Lithium-ion Capacitor Market study has been designed specifically for that decision window. Covering historical performance from 2020 through the 2025 base year and extending a comprehensive forecast through 2032, the report translates macro momentum into operational intelligence. It is built to help businesses answer three foundational questions: where is the market heading, who is positioned to win, and what levers will separate commercially viable production from stranded assets.
Macro Trajectory: Reading the Curve Beyond the Headline
The numbers tell a story of accelerating adoption, but the strategic value lies in how that growth compounds across technology generations and application verticals. After a measured but steady climb through the early 2020s, the laminating LIC segment crossed into a new growth phase. The market generated approximately $324.94 million in 2023, expanded to $385.05 million in 2024, and reached $456.28 million in 2025. From that base year, the trajectory steepens markedly: the forecast projects $540.87 million in 2026, $641.15 million in 2027, $760.02 million in 2028, $900.93 million in 2029, $1.067 billion in 2030, $1.266 billion in 2031, and roughly $1.501 billion by 2032.
Worldwide Laminating Lithium-ion Capacitor Market
At a compound annual growth rate of 18.54 percent across the 2026–2032 forecast period, this is not a linear extension of prior trends. It is a structural inflection driven by manufacturing maturation, application pull, and an industry-wide pivot toward formats that can be integrated more flexibly into energy storage systems, industrial loads, and mobility platforms. The strategic implication is clear: companies that anchor their planning to conservative, slow-growth assumptions risk mis-timing capacity investments, partnership structures, and product roadmaps. A market expanding at this cadence rewards early alignment with the formats, certifications, and regional supply chains that end customers are beginning to specify.
That said, headline revenue figures are only the starting point. The actual strategic decisions—whether to invest in dry-electrode processes, which specification thresholds will win in particular verticals, how pricing dynamics evolve as activated-carbon sourcing shifts, and where incremental capacity should be located—depend on the segmentation detail and competitive intelligence that complete research provides. The high-level curve signals urgency; the detailed breakdown converts urgency into execution.
Laminating Machine Market
What the Report Covers: Operational Intelligence for Decision-Makers
PW Consulting's laminating LIC market study is structured as a practical decision-support instrument rather than a static data compilation. The report maps the evolution of market sizing from the historical window into a granular forecast framework, enabling readers to benchmark current product portfolios, capacity plans, and regional footprints against the direction of demand. A core focus is placed on laminate-format dynamics, including pouch and lamination-compatible electrode processes, thin-form-factor cells, and the manufacturing transitions that make high-volume production economically feasible.
The study dissects the market across multiple dimensions—technology and form factor, application segments, and regional demand centers—so that leaders can isolate where growth is concentrated and where margin durability is most achievable. By connecting market sizing to the underlying drivers of adoption, the report helps strategists evaluate which applications are transitioning from pilot deployments to specification-driven purchasing, and which regions are becoming procurement hubs versus manufacturing bases. This level of segmentation is essential for companies deciding where to prioritize sales engineering resources, which customer segments deserve dedicated product variants, and how to sequence expansion without diluting operational focus.
Equally important, the research translates regulatory, materials, and supply chain intelligence into market-facing implications. With the industry navigating raw material cost thresholds, pre-doping capability licensing, and geopolitical-driven sourcing diversification, the report connects these structural forces to commercial strategy. Decision-makers gain a clearer line of sight between production economics, qualification timelines, and the competitive positioning required to win in tenders, system integration projects, and OEM design-ins. Rather than leaving readers with isolated facts, the analysis ties those factors into a coherent framework for scenario planning and capital allocation.
Competitive Possession: The Players Shaping the Laminate Transition
The laminating LIC market is not a free-for-all. It is a concentrated arena where a select group of manufacturers is actively defining format standards, scaling production, and pursuing partnerships that lock in downstream demand. The report maps this landscape through detailed company profiles, recent commercial developments, and competitive positioning analysis, giving strategists the context needed to evaluate partnership targets, benchmarking benchmarks, and threat vectors.
LICAP Technologies, Inc., based in Sacramento, California, has moved aggressively into laminate-compatible electrode processes, leveraging proprietary Activated Dry Electrode technology. In March 2026, the company secured a 40,500-square-foot industrial facility in Sacramento, tripling its space to scale production of dry electrode technology for lithium-ion capacitors and ultracapacitors supporting automotive and grid applications. Earlier, in February 2026, LICAP advanced a dry cathode electrode manufacturing collaboration with Nissan focused on scalable production processes applicable to lithium-ion capacitors and broader energy storage. These moves reflect a broader industry pull toward manufacturing approaches that reduce solvent handling, improve consistency, and align with laminate and pouch-compatible formats.
Musashi Energy Solutions Co., Ltd. (JM Energy) in Japan continues to build on its ULTIMO lithium-ion capacitor platform, offering laminate-cell, prismatic-cell, and module formats with a focus on high energy and power density hybrid supercapacitors. The company's established mass-production capacity positions it as a formidable reference point for customers seeking qualified, volume-ready solutions. In March 2025, its ESS400 Energy Storage System using hybrid supercapacitor/LIC technology received UL1973 listing for safety compliance, a milestone that underscores how certifications are becoming strategic gatekeepers in larger storage deployments.
SPEL Technologies Private Limited in India has pushed pouch (laminated) construction into higher-capacitance territory, offering thin-form-factor pouch cells up to 4500F at 3.8V with energy density advantages over standard EDLCs. This product direction illustrates the growing appetite for laminated formats that can deliver more energy in less volume, particularly where system designers need flexibility in packaging and thermal layout.
VINATech Co., Ltd. in South Korea, with facilities in South Korea and Vietnam, manufactures hybrid lithium-ion capacitors under its VPC series at 3.8V, combining EDLC and Li-ion characteristics within smart factory environments. Its emphasis on low-leakage, high-energy applications signals a market in which quality consistency and leakage performance are increasingly weighted in technical evaluations.
JTEKT Corporation and Taiyo Yuden Co., Ltd. in Japan represent additional depth in the competitive field. JTEKT produces laminated-type lithium-ion capacitors using processes similar to lithium-ion batteries, while Taiyo Yuden offers its LITHOSION series of cylinder-type lithium-ion capacitors with high-temperature capabilities up to 105°C for backup and peak power applications. The diversity of form factors and thermal specifications indicates that laminating formats compete within a broader ecosystem of product architectures, and the strategic question for each player is how to position laminate solutions against cylindrical and prismatic alternatives.
The field also includes emerging and regionally positioned players such as YUNASKO, which develops hybrid supercapacitor/LIC cells in prismatic encasement from multi-layered laminated aluminum foil with a focus on high-power modules; Shanghai Yongming Electronic Co., Ltd., a China-based manufacturer emphasizing high-performance and reliability for energy storage; GMCC Electronic Technology WUXI Ltd., which produces lithium-ion capacitors as part of an advanced energy storage portfolio; and Tecate Group in the USA, supplying lithium-ion capacitor products and hybrid solutions for industrial and power applications. Together, these companies illustrate both the global reach of laminating LIC development and the varying maturity levels that strategists must evaluate when assessing supply chain partners or potential acquisition targets.
From a concentration standpoint, the industry exhibits meaningful consolidation pressure. The market's competitive structure indicates that a relatively small number of participants command a large share of revenue. This concentration shapes pricing power, qualification bottlenecks, and the pace at which new entrants can establish credibility. For businesses evaluating the market, the implication is that ecosystem access—through partnerships, distribution channels, and co-development agreements—can be as decisive as raw manufacturing capability. PW Consulting's full study unpacks these competitive dynamics in greater depth, including how firms are differentiating on process technology, certification readiness, and application-specific performance envelopes.
Dynamics That Will Define the Forecast Window
The growth path does not operate in a vacuum. Several structural forces are actively reshaping the economics and execution risk of laminating LIC production, and they deserve close attention in 2026 strategy sessions.
- Raw material economics are becoming a gating factor for cost-competitive manufacturing. Production of lithium-ion capacitors depends on activated carbon for electrodes and lithium for pre-doping. Coconut-shell based activated carbon accounted for approximately 70.75 percent of supercapacitor-specific raw material sources in 2024, underscoring the dependence on a narrow set of feedstock pathways. At the same time, activated carbon for supercapacitor electrodes needs to stay below $10/kg for economic viability, yet current pricing around $15/kg—driven in part by biomass-derived sources—is pressuring margins. These cost dynamics make process efficiency, electrode design, and sourcing strategy central to competitiveness rather than peripheral concerns.
- Pre-doping and manufacturing licensing are lowering barriers but also reshaping competitive entry paths. In July 2023, Asahi Kasei licensed its lithium pre-doping technology to enable lower-cost LIC manufacturing using standard lithium-ion battery equipment and materials. That shift is significant because it supports a transition toward production methods that can more readily accommodate laminate formats and scale beyond niche output. For strategists, the takeaway is that technology licensing, equipment compatibility, and process standardization are now part of the competitive equation, not only cell-level performance.
- Supply chain geography and tariff exposure are forcing reallocation. Tariffs and geopolitical shifts are driving supply chain diversification for critical materials such as lithium and activated carbon in energy storage components, prompting nearshoring and alternative sourcing. Companies that rely on single-region sourcing or fixed logistics assumptions face increasing exposure, while those that build multi-source strategies and align manufacturing footprints with end-market demand can reduce qualification risk and improve resilience.
These dynamics do not operate independently. They interact with application pull, certification timelines, and regional procurement behavior. A company's ability to navigate all four simultaneously—materials cost, process licensing, supply chain diversification, and qualification readiness—will increasingly separate winners from followers. The report's full market intelligence connects these forces to the specific segments and regions where their impact is greatest, enabling a more precise reading of where risk and opportunity converge.
Why This Study Matters for 2026 Decisions
The 2026–2032 window is not merely a forecasting period; it is a planning horizon in which format choice, manufacturing strategy, and competitive positioning are being locked in. Laminating lithium-ion capacitors are moving from a promising technology category toward a mainstream option in selected energy storage and power delivery applications, and that transition is being accelerated by manufacturing advancements, certification progress, and raw-material-driven cost scrutiny. Decision-makers who wait for certainty will find themselves reacting to specifications and supply chain moves that competitors have already internalized.
PW Consulting's Worldwide Laminating Lithium-ion Capacitor Market study is designed to reduce that uncertainty. It offers historical grounding, a multi-year forecast, segmenting intelligence, and competitive analysis that together support product strategy, capacity planning, partnership evaluation, and risk assessment. The macro figures provide the directional signal; the detailed segmentation, company profiles, and industry-context analysis provide the operational map.
Because the market's segmentation splits and application-specific revenue distributions carry direct implications for where to deploy commercial resources, the full report is structured to give readers the granularity required for precise strategy work. Rather than relying on aggregate trends alone, teams can use the complete dataset to compare regional demand patterns, assess how energy-type and power-type LIC variants are contributing to overall growth, and identify which application verticals are most relevant to a given product roadmap. This is the difference between knowing the market is expanding and knowing where to place bets with confidence.
Next Steps: From Market Signal to Executable Strategy
For organizations evaluating laminating lithium-ion capacitors as a procurement source, a product platform, or an investment target, the strategic task in 2026 is to convert broad momentum into specific actions. That means aligning product specifications with the formats that end customers are beginning to prefer, stress-testing manufacturing plans against raw material cost thresholds, and mapping partnership opportunities against the companies that are actively scaling laminate-compatible processes and securing key certifications. It also means recognizing that competitive concentration and qualification barriers can shape market access just as much as technical performance.
The comprehensive PW Consulting research provides the detailed segmentation, company-level intelligence, and industry-context analysis needed to make those choices with greater precision. It is built to support board-level discussions, R&D prioritization, commercial planning, and supply chain strategy by connecting market size and forecast to the operational realities that determine execution success. The headline trajectory indicates that laminating LIC technology is entering an acceleration phase; the full study is what enables leaders to navigate that phase with discipline, focus, and competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Laminating Lithium-ion Capacitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global 3D AOI Equipment in PCB Market to Reach $2.3 Billion by 2032 with 11.2% CAGR
By pmarketresearch, 2026-09-16
Navigating the High-Growth PCB Inspection Landscape: Strategic Insights into the Worldwide 3D AOI Equipment Market (2026-2032)
As the printed circuit board (PCB) industry enters a pivotal phase of technological refinement, the demand for precision manufacturing tools has never been more critical. PW Consulting is pleased to introduce our latest comprehensive study: Worldwide 3D Automated Optical Inspection Equipment in PCB Market . This report serves as a strategic compass for industry stakeholders navigating the complex dynamics between technological advancement, supply chain volatility, and escalating quality standards. With the market valuation reaching approximately 1100.0 Million USD in 2025 and projected to expand significantly through 2032, understanding the trajectory of 3D Automated Optical Inspection (AOI) systems is essential for capital allocation, product development, and competitive positioning.
This article provides a high-level overview of the market forces shaping the sector, highlighting why our in-depth research is indispensable for informed decision-making in 2026 and beyond. While we share macro-level insights here, the full report contains the granular segmentation, competitive benchmarking, and risk analysis necessary to execute robust strategies.
3D Automated Optical Inspection (AOI) Market
Market Trajectory and Growth Drivers
The global market for 3D AOI equipment in PCB manufacturing has demonstrated robust resilience and expansion over the past five years. From 2020 to 2025, the sector evolved from a niche requirement to a standard component of high-reliability assembly lines. Our analysis indicates a compound annual growth rate (CAGR) of 11.2 percent during the forecast period from 2026 to 2032. This growth is not merely a function of volume but is driven by the increasing complexity of PCB architectures, including High-Density Interconnect (HDI) technologies and the miniaturization of components.
The revenue unit for this market is tracked in Million USD, reflecting a mature yet expanding industrial ecosystem. The shift from 2D to 3D inspection capabilities is a primary catalyst, as manufacturers seek to detect defects in solder paste volume, component placement accuracy, and height measurement with greater precision. As electronic devices become more integral to automotive, telecommunications, and medical applications, the tolerance for error diminishes, necessitating advanced inspection tools. Our full report details the specific revenue thresholds expected in 2026 and beyond, providing clear targets for capacity planning.
Technological Evolution and Standards
Technological innovation within the 3D AOI space is accelerating, with several key methods dominating the landscape. Among the prevailing technologies are Moiré Fringe Profilometry, which remains a cornerstone for high-accuracy height measurement, Laser Triangulation for precise surface profiling, and Stereoscopic Imaging for broader depth perception. The integration of these technologies is becoming more sophisticated, often combining multiple sensing modalities to overcome limitations such as multi-reflection suppression on shiny components like Ball Grid Arrays (BGAs) and Quad Flat No-leads (QFNs).
Furthermore, regulatory frameworks are tightening. The IPC-9252B standard, updated in 2025, now mandates 3D height measurement accuracy of ±2μm for AOI in high-reliability PCB inspection. Compliance with such standards is no longer optional for manufacturers serving automotive or medical sectors. Additionally, industry data suggests that lead times for high-resolution 3D camera modules used in AOI systems averaged 16-20 weeks in the fourth quarter of 2025 due to semiconductor shortages. This supply chain friction underscores the need for strategic inventory planning and vendor diversification, details of which are explored extensively in our full analysis.
Competitive Landscape and Key Players
The market exhibits a moderate level of concentration, with the top three companies holding a significant share of the total revenue pool. This oligopolistic structure suggests strong barriers to entry for new competitors but also offers established players substantial leverage in pricing and technology standardization. Our report provides a deep dive into the strategic moves of these market leaders, analyzing their product launches, partnership networks, and regional strengths.
Notable entities shaping the competitive environment include:
- Koh Young Technology (South Korea): Recognized for the Zenith Alpha series, this provider focuses on true 3D imaging for high-speed defect detection in Surface Mount Technology (SMT) assembly.
- CyberOptics Corporation (USA): Known for the SQ3000 3D AOI systems, their technology emphasizes multi-reflection suppression for accurate inspection of complex components.
- Viscom AG (Germany): A developer of high-volume production solutions such as the S3088 ultra for PCB assembly lines, utilizing advanced 3D sensor technology.
- Test Research, Inc. (Taiwan): Provides TR7000 series equipment, placing a strong emphasis on AI-driven analysis for solder paste and component placement verification.
- SAKI Corporation (Japan): Specializes in 3Di series systems, featuring gimbal-less camera technology for precise height measurement and defect classification.
- Mirtec Corporation (USA): Manufactures MV-3 Series systems, integrating high-resolution cameras and laser profiling for comprehensive post-reflow analysis.
- Nordson TEST & INSPECTION (USA): Offers solutions combining AOI and AXI capabilities, catering to automated inspection in high-mix production environments.
Recent activity among these firms illustrates the pace of innovation. For instance, specific product enhancements were announced throughout 2025, including AI-integrated systems capable of handling smaller components like 01005 packages and updated compliance certifications for PCB production data interoperability. These developments signal a shift toward smarter, more compliant inspection ecosystems. Readers seeking the full timeline of product launches and specific model implications should refer to the complete report.
Worldwide 3D Automated Optical Inspection Equipment in PCB Market
Regional Dynamics and Geopolitical Factors
The Asia Pacific region continues to dominate the volume of equipment deployments, reflecting the concentration of PCB manufacturing hubs in East and Southeast Asia. However, North America and Europe maintain significant shares driven by local assembly needs for defense, aerospace, and specialized industrial applications. Our segmentation analysis breaks down the volume contributions across these regions, revealing distinct growth patterns and investment priorities.
Geopolitical factors are increasingly influencing market flows. In 2025, US export controls on advanced imaging sensors under the Wassenaar Arrangement impacted a portion of 3D AOI shipments to China. Simultaneously, the European Union imposed tariffs on AOI equipment imports from non-EU countries starting January 2025, which has raised costs for German PCB assemblers and potentially incentivized local sourcing or alternative supply chains. These trade barriers create complex arbitrage opportunities and risks that require careful navigation. Our full report quantifies these regional shifts and provides scenario planning for supply chain resilience.
Pricing Trends and Investment Considerations
Cost structures within the 3D AOI market are undergoing upward pressure. The average price of 3D AOI systems for PCB increased by 8 percent year-over-year in 2025, largely attributed to optics inflation and component scarcity. Unit costs for advanced systems are converging in the range of 150,000 to 250,000 USD per unit. For capital equipment managers, this pricing environment necessitates a clear Total Cost of Ownership (TCO) analysis that accounts for maintenance, software licensing, and potential downtime due to component lead times.
Investment in 3D AOI is not merely a compliance cost but a strategic enabler for higher yield rates and reduced manual inspection labor. As end-user industries such as Consumer Electronics and Automotive Electronics demand higher reliability, the ROI on advanced inspection becomes clearer. The full study includes detailed break-even analyses and cost-benefit frameworks tailored to different production volumes.
Why This Report is Critical for 2026 Decision-Making
In a market defined by rapid technological shifts and external shocks, reliance on outdated data is a significant liability. This PW Consulting report offers actionable intelligence designed to support strategic planning for the 2026 to 2032 period. Whether you are a manufacturer evaluating procurement strategies, an investor assessing market entry opportunities, or a technology provider seeking to understand competitive threats, this document provides the foundational data required to act with confidence.
Key deliverables within the full report include:
- Historical market size data from 2020 to 2025 with verified figures.
- Forecasting models extending to 2032 with detailed revenue projections.
- Segmentation by technology, end-user, and region without exposing sensitive proprietary splits in this summary.
- Competitive profiling of key vendors including their recent developments and strategic focus.
- Analysis of external factors such as tariffs, export controls, and component supply chain delays.
The concentration of the market, with the top three players holding 52.4 percent of the share and the top five holding 68.15 percent, highlights the importance of understanding supplier relationships and potential consolidation trends. Strategic decisions regarding vendor lock-in or multi-sourcing strategies depend on nuanced insights provided in the full document.
Conclusion and Next Steps
The Worldwide 3D Automated Optical Inspection Equipment in PCB Market is poised for sustained expansion, driven by the relentless demand for quality and miniaturization in electronics manufacturing. However, realizing value in this environment requires more than general market awareness. It demands precise data on segmentation, competitive dynamics, and regulatory impacts.
PW Consulting invites industry leaders to download the full report to access the complete dataset and strategic recommendations. Our team has curated this intelligence to empower your organization to mitigate risk and capture growth opportunities in the coming years. For detailed insights into regional splits, specific technology adoptions, and end-user spending patterns, please visit the source webpage to obtain the comprehensive study.
For detailed analysis of this topic, please visit the official page: Worldwide 3D Automated Optical Inspection Equipment in PCB Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Sees Interlayer Films Market Hit $525.63M by 2032, 8% CAGR
By pmarketresearch, 2026-09-16
Strategic Clarity for 2026: Navigating the Global SGP Interlayer Films Market
As multinational corporations accelerate their sustainability agendas and building codes tighten around fenestration performance, the SGP interlayer films sector stands at a critical inflection point. For executives mapping their procurement, capacity, and market-entry strategies in 2026, intuition is no longer a sufficient compass. The Worldwide SGP Interlayer Films Market research report from PW Consulting delivers the granular, forward-looking intelligence required to convert structural ambiguity into competitive advantage. Drawing on historical performance from 2020 through 2025 and projecting disciplined trajectories through 2032, this analysis equips leadership teams with the scenario-planning rigor needed to de-risk capital allocation across dynamic segments.
Macro Trajectory and the 2026 Investment Inflection
The global SGP interlayer films market has demonstrated resilient, compounding growth across the most recent evaluation window. Revenue expanded from approximately 212.45 million USD in 2020, climbing through successive annual milestones to reach 306.69 million USD by the 2025 base year. Fortifying this momentum, the forecast period projects a compound annual growth rate of 8.0 percent, propelling estimated market size to 343.05 million USD in 2026 and charting a sustained upward path toward 525.63 million USD by 2032. These headline figures do more than quantify expansion; they signal a structural shift in how engineers, architects, and procurement teams value interlayer performance. The consistent year-over-year uplift underscores that SGP films are transitioning from niche specialty inputs to core enablers of high-performance glazing, particularly as building owners and authorities demand enhanced post-breakage integrity, blast mitigation, and long-term optical clarity. For 2026 decision-makers, the strategic imperative is clear: product roadmaps, supplier contracts, and regional distribution architectures must be recalibrated to align with an 8 percent growth engine rather than static legacy demand curves.
What the Report Delivers: From Market Maps to Execution Playbooks
Beyond the aggregate growth narrative, this research translates top-line trajectories into actionable operational intelligence. The full publication dissects demand drivers, supply-chain bottlenecks, and competitive maneuvers with an emphasis on deployable strategy. Readers will encounter rigorous breakdowns across primary application vectors, end-user categories, and geographic corridors, each calibrated to reveal where margin pools concentrate and where volume scaling is most feasible. The report moves past descriptive categorization to interrogate the mechanics of purchasing behavior, specification cycles, and substitution risk within structural glazing, security and hurricane resistance, mobility applications, and adjacent specialty uses.
Supplier and distributor positioning receives similarly granular treatment, enabling executives to benchmark their own value propositions against incumbent capabilities and emerging capacity plays. Because the overarching market structure exhibits pronounced concentration, with the top three players commanding roughly 84.5 percent share and the top five capturing approximately 92.15 percent, the analysis isolates how incumbents leverage patented ionoplast formulations, vertical integration, and certification portfolios to defend high-margin installations. Simultaneously, the report surfaces the pathways through which authorized distributors, specialized laminators, and regional processors can capture share by tailoring thickness options, pre-laminated panel configurations, and region-specific compliance documentation. For procurement leaders, the study provides the comparative framework necessary to evaluate total cost of ownership, lead-time reliability, and specification risk across competing interlayer technologies.
Competitive Architecture: Four Profiles Shaping the Global Landscape
The current competitive arena is anchored by players with distinct technical pedigrees and geographic footprints. Trosifol, headquartered in Wiesbaden, Germany, operates as a leading provider of SentryGlas SGP interlayer films for structural glazing, offering high-strength ionoplast films with tear resistance approximately five times that of conventional PVB, specifically engineered for hurricane-resistant and high-load architectural environments. Its sustained R&D cadence is evident in the October 2024 launch of SentryGlas Expression 78/2, a newly introduced colored SGP interlayer designed for decorative structural glazing with enhanced UV stability, expanding aesthetic options without compromising structural performance.
Worldwide Window Films Market
Kuraray, based in Tokyo, Japan, develops and manufactures SentryGlas ionoplast interlayer films under the Trosifol brand, with particular specialization in ultra-thick SGP films reaching 6.38 mm for blast-resistant and seismic glazing applications worldwide. The company's mid-2024 certification milestone, wherein SentryGlas interlayers achieved EN 16613 conformity for use in overhead glazing applications across Europe, represents a critical market-access lever, reducing specification friction for engineering teams pursuing atriums, canopies, and elevated envelopes.
Everlam, located in Halen, Belgium, supplies SGP interlayer films including SentryGlas variants for safety and security glass laminates, with a clear operational focus on custom thicknesses for European and global structural projects. Its March 2025 capacity expansion, which lifted SGP lamination throughput by 20 percent at the Halen facility, directly responds to intensifying European demand for structural glass assemblies, reinforcing a supply posture calibrated to project pipelines rather than spot transactions.
Glastrotech, operating from Dallas, TX, USA, functions as an authorized distributor and processor of SentryGlas SGP interlayers for North American markets, providing pre-laminated panels for high-performance building facades. By bridging raw interlayer supply with finished-façade readiness, this distribution-and-processing model shortens lead times and reduces on-site fabrication risk, a differentiator that resonates with general contractors seeking schedule certainty in complex envelope installations.
Market Dynamics: Feedstocks, Regulation, and Trade Policy in Tension
Strategy in 2026 cannot be divorced from the external forces currently reshaping cost structures, compliance obligations, and market access. On the input side, recent pricing intelligence shows that polyvinyl butyral and ionomer resins, the essential feedstocks underpinning SGP film production, experienced spot price increases during the final quarter of 2024, driven by ethylene monomer tightness. This cost pressure interacts directly with margin management strategies, particularly for producers reliant on spot procurement rather than hedged or long-term supply agreements. Decision-makers evaluating supplier stability must therefore scrutinize feedstock contracting practices, blending flexibility, and pass-through mechanisms in commercial terms.
At the regulatory level, the European Union's Construction Products Regulation mandates CE marking for SGP interlayers deployed in load-bearing glass, with pRAVE testing required to validate post-breakage vision clarity. This obligation elevates technical documentation from a back-office task to a front-line specification requirement. Specifiers increasingly favor interlayers with pre-validated certification pathways, and manufacturers able to streamline test reporting and regional labeling gain measurable advantages in qualification cycles. In parallel, REACH Annex XVII restrictions on certain plasticizers have reinforced the structural appeal of SGP ionoplasts as non-PVC alternatives, positioning compliance-friendly chemistry as a commercial asset rather than a baseline expectation.
Trade policy introduces a further layer of complexity for North American procurement. US Section 301 duties remain in effect on SGP interlayers imported from China at the 25 percent level through 2025, altering total landed cost comparisons for buyers evaluating offshore-sourced volumes. For multinational programs, this shifts the calculus toward diversified sourcing, regional processing partnerships, and careful HTS classification diligence. The interplay of feedstock volatility, certification mandates, and tariff exposure means that 2026 sourcing strategies must weigh not only unit pricing but also the cumulative cost of qualification delays, logistics friction, and inventory buffers.
Why 2026 Decision-Makers Need This Intelligence Now
Many organizations still approach interlayer selection through the lens of single-project cost optimization, yet the evolving market structure rewards a portfolio-level perspective. As structural glazing, security and hurricane resistance, transportation, and supporting applications continue to diverge in performance requirements and procurement rhythms, blanket specifications create unnecessary exposure. The report's segmentation architecture allows executives to isolate where demand is scaling fastest, which end-user segments prioritize safety-performance certifications, and how regional dynamics influence both pricing tolerance and lead-time expectations. Commercial buildings, residential buildings, industrial and public infrastructure, and automotive and marine applications each follow distinct specification cycles and approval pathways; understanding these differences prevents misallocated R&D effort and poorly timed inventory commitments.
Equally important, the concentration profile of the market shapes negotiation leverage. With a limited group of firms controlling a dominant share of global supply, buyers and competitors alike must understand how incumbents defend premium installations, how distributors extend reach through pre-laminated panel offerings, and where new capacity is most likely to open margin opportunities rather than erode them. For suppliers, the analysis clarifies which product attributes and certifications unlock access to overhead glazing, blast-resistant assemblies, and decorative structural projects. For distributors and processors, it identifies where service differentiation, regional compliance readiness, and project-based panel configurations can translate into stickier relationships and higher realized margins.
From Insight to Execution: What Comes Next
The Worldwide SGP Interlayer Films Market study is structured to convert market visibility into executable strategy. It integrates historical benchmarking, forward projections, application and end-user dynamics, regional deployment logic, competitive profiling, and environmental and regulatory context into a single decision-support framework. Leaders can use the publication to stress-test capacity plans, refine product configurations for targeted segments, align procurement contracts with supply-risk realities, and prioritize geographic engagements where certification readiness and distribution architecture confer measurable advantage.
Worldwide SGP Interlayer Films Market
Because the market landscape is defined by concentrated supply, rising performance expectations, feedstock sensitivity, and evolving trade and compliance conditions, partial intelligence carries real downside risk. The full report provides the depth required to move from directional confidence to precision execution. To access the complete segmentation detail, competitive assessments, and scenario-based guidance that underpin this outlook, visit the official PW Consulting market research page and download the full Worldwide SGP Interlayer Films Market publication.
For detailed analysis of this topic, please visit the official page: Worldwide SGP Interlayer Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HIFU Lipoplasty Devices Market to Hit $909.01M by 2032 at 8.01% CAGR
By pmarketresearch, 2026-09-16
Navigating the Next Phase: Inside the Worldwide HIFU Lipoplasty Devices Market Intelligence
The global aesthetic therapeutics landscape is undergoing a structural shift. Where invasive lipoplasty once dominated procedural suites, High-Intensity Focused Ultrasound (HIFU) has emerged as a defining force, offering clinicians and patients a compelling middle ground between surgical intervention and non-invasive contouring. As market participants prepare for the 2026 planning cycle, the ability to separate signal from noise in this rapidly maturing segment has become a competitive necessity. PW Consulting's latest Worldwide High-Intensity Focused Ultrasound (HIFU) Lipoplasty Devices Market research was designed precisely to meet that need. This study goes beyond top-line projections, delivering the operational, regulatory, and competitive intelligence required to calibrate portfolio strategies, prioritize R&D pipelines, and capture emerging demand across clinical channels.
Drawing on historical tracking from 2020 through 2025 and forward-looking modeling extending to 2032, the research captures a market that has demonstrated consistent expansion. Total addressable revenue scaled from approximately 370 million USD in 2020 to an estimated 530 million USD by 2025, reflecting sustained adoption across mature and growth-phase geographies. The baseline forecast envisions continued momentum through the end of the decade, with the market projected to surpass 850 million USD by 2031 and approach the 900 million USD threshold by 2032. This trajectory translates to a forecast-period compound annual growth rate of roughly 8.01 percent, a figure that underscores robust underlying demand even as pricing pressures, reimbursement dynamics, and regulatory evolution introduce complexity. For executive teams mapping multi-year investment horizons, these macro indicators establish the scale of the opportunity while highlighting the importance of granular execution strategies.
Worldwide High-Intensity Focused Ultrasound (HIFU) Lipoplasty Devices Market
What the Report Delivers: Actionable Intelligence for Strategic Planning
A market of this breadth cannot be navigated on aggregate figures alone. The research compiles a comprehensive, multi-dimensional assessment that bridges strategic oversight with tactical decision-making. Executive teams will find structured evaluations of device architecture, clinical efficacy benchmarks, and the operational economics that govern procurement cycles across different care settings. The study maps the full device landscape, distinguishing stationary console systems from portable and compact alternatives, and examines how each category aligns with facility throughput, staffing models, and patient acquisition strategies.
- Device architecture and clinical positioning: Detailed analysis of HIFU transducer designs, energy delivery optimization, treatment zone coverage, and procedural workflow considerations that influence clinician adoption and patient satisfaction.
- Procurement pathways and end-user economics: An evaluation of purchasing patterns across aesthetic and dermatology clinics, hospitals and surgical centers, and medical spas and wellness centers, including capital expenditure expectations, maintenance cycles, and session-based revenue modeling.
- Regulatory and reimbursement frameworks: A cross-jurisdictional review of clearance requirements, post-market surveillance obligations, and coding structures that shape reimbursement eligibility and practice viability.
- Competitive benchmarking: Profiles of key manufacturers, their product footprints, and strategic moves that are reshaping supply-side dynamics.
- Risk and opportunity mapping: Identification of adoption barriers, technological substitution threats, and regional growth accelerators that warrant scenario planning.
Competitive Dynamics: Market Concentration and Strategic Positioning
The HIFU lipoplasty ecosystem is characterized by a moderately consolidated supply base, where a concentrated group of established players commands a significant share of revenue while remaining exposed to rapid product iteration and indication expansion. The report provides an in-depth review of the firms that are actively shaping the category, including device specifications, regional commercialization strategies, and the clinical narratives that differentiate their offerings.
Among the profiled participants, Liposonix (Hologic) has historically been associated with the Liposonix system, an FDA-cleared HIFU platform designed for non-invasive abdominal fat reduction via high-intensity focused ultrasound. Ulthera (Merz Aesthetics) brings a broader aesthetic platform with the Ultherapy system, originally adapted for skin lifting and tightening and increasingly extended toward body contouring applications within lipoplasty workflows. InMode offers the Ultraformer III, a HIFU device targeting both facial and body sculpting, with explicit emphasis on fat reduction in lipoplasty procedures. Hironic contributes the Doublo Gold HIFU system, positioned for non-surgical fat reduction and skin tightening within aesthetic lipoplasty settings.
Recent corporate activity reinforces the pace of innovation and the intensity of competitive maneuvering. InMode's October 2024 product launch introduced the Ultraformer MPT with enhanced HIFU transducers aimed at improving body contouring and fat reduction efficacy, signaling a clear investment in procedural performance. Around the same period, Merz Aesthetics secured FDA 510(k) clearance in June 2024 for expanded Ultherapy indications, including submental fat reduction, broadening the addressable patient set for an already established platform. Earlier, in November 2023, Hironic renewed its CE Mark for the Doublo Gold PRO with new cartridges designed for deeper fat targeting in lipoplasty, illustrating a continued push toward procedural precision and market differentiation. Together, these developments reflect a competitive environment where regulatory milestones, transducer engineering, and indication breadth are central to market share retention.
Market Dynamics: Regulation, Reimbursement, and the Realities of Clinical Adoption
The growth trajectory of HIFU lipoplasty devices is inseparable from the regulatory and reimbursement environment in which they operate. The report excavates the policy layers that determine where, how, and at what cost these technologies can be deployed. In the United States, HIFU lipoplasty devices are generally subject to FDA Class II 510(k) clearance, requiring manufacturers to demonstrate safety for non-invasive fat ablation at treatment depths of up to 2 cm. This clearance pathway influences product development timelines, labeling scope, and the speed at which new indications can be commercialized.
Across the European Union, device classification and conformity assessment have tightened under the EU MDR framework. HIFU devices fall within the Class IIb category, and compliance now carries mandatory post-market surveillance responsibilities under Regulation (EU) 2017/745. For manufacturers and distributors, these requirements add operational overhead and shape launch sequencing, particularly as companies balance speed-to-market with the need for durable regulatory standing.
Reimbursement considerations are equally consequential. CPT code 0389T covers HIFU for fat reduction, with average Medicare reimbursement of approximately 1,200 USD per treatment session. While this coding structure supports procedural revenue for eligible providers, actual practice economics vary by payer mix, regional utilization patterns, and the degree to which sessions are bundled or marketed as elective aesthetic services. Understanding these reimbursement mechanics is essential for forecasting realistic utilization curves and aligning device procurement with service-line profitability.
The study also addresses operational realities that often surface only after a device enters clinical use. Treatment depth limitations, session duration, patient selection criteria, and clinician training requirements all influence adoption velocity. Where a manufacturer has withdrawn or discontinued a legacy platform, as occurred with the Liposonix system in 2016 when it was no longer commercially available for new purchases, channel strategy and installed-base transitions become critical considerations for both buyers and competitors. These legacy dynamics are examined within the report to clarify how historical product lifecycles influence current purchasing behavior and supplier credibility.
Where Growth Is Concentrated: End-User Channels and Device Profiles
Not all demand channels carry equal weight, and the report provides a structured lens on where revenue generation is most concentrated. Aesthetic and dermatology clinics represent the largest end-user segment, reflecting the category's alignment with outpatient cosmetic procedures and patient-driven demand for minimally invasive body contouring. Hospitals and surgical centers contribute a meaningful secondary share, where HIFU is increasingly evaluated as an adjunct or alternative within broader body-contouring service lines and surgical recovery pathways. Medical spas and wellness centers form a third channel, typically characterized by faster patient turnover, elective purchasing behavior, and strong sensitivity to treatment experience and brand perception.
Device form factor further segments adoption. Stationary console systems command the largest share of revenue, consistent with their suitability for higher-volume clinical environments, integrated workflow control, and more complex treatment planning. Portable and compact devices, while smaller in absolute terms, represent a strategically important category for expanding access in decentralized settings, supporting outreach-based service models, and enabling flexible deployment across multiple locations. The report examines how these device categories interact with end-user purchasing behavior, capital constraints, and clinical throughput expectations.
High Intensity Focused Ultrasound (HIFU) Market
Why This Research Matters for 2026 Decision-Making
As organizations enter the 2026 planning window, the HIFU lipoplasty market presents a landscape that rewards disciplined intelligence. Aggregate growth signals are encouraging, but they conceal considerable variation in regional velocity, clinical adoption speed, reimbursement acceptance, and competitive intensity. A strategic response requires more than a macro outlook; it requires an integrated view of product positioning, regulatory exposure, service-line economics, and competitor intent.
This research is intended to function as a decision-making backbone for executive teams across several core activities:
- Portfolio and investment prioritization: Evaluating which device architectures, indications, and end-user channels offer the strongest alignment with organizational capabilities and capital deployment timelines.
- Regulatory and market access readiness: Anticipating clearance pathways, post-market obligations, and reimbursement positioning so that product launches and distribution plans are calibrated to local requirements.
- Competitive anticipation: Understanding how key manufacturers are evolving transducer technology, extending indications, and refreshing certifications, and what those moves imply for share dynamics and pricing power.
- Channel strategy refinement: Matching procurement models, service workflow, and patient acquisition approaches to the distinct economics of aesthetic clinics, hospitals, and wellness centers.
- Risk management: Identifying adoption constraints, legacy product transitions, and regulatory evolution that may alter demand assumptions or competitive responses.
Acquiring the Full Intelligence Set
This overview is intended to convey the scope, rigor, and strategic relevance of the research without diluting the proprietary detail that makes it actionable. The full study contains the complete market sizing architecture, forecast breakdowns, segmentation values, end-user economic profiles, competitive positioning matrices, and scenario analysis that executive teams require for precise planning. Readers seeking the quantitative foundation behind the narrative trends described here, including the detailed regional and device-type distribution figures and the full set of end-user revenue values that anchor the forecast model, are encouraged to access the source page to retrieve the complete market intelligence package.
For organizations preparing to invest, compete, or expand within the HIFU lipoplasty category through 2026 and beyond, this research offers a structured, up-to-date, and operationally focused view of where the market stands and where it is heading. The opportunity is significant, but so is the need for clarity. Access to the complete report provides that clarity, translating macro momentum into executable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide High-Intensity Focused Ultrasound (HIFU) Lipoplasty Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Chemical DCS Market Reaches $6.51B in 2025, Projects 5.5% CAGR to $9.47B by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Chemical DCS Landscape: Navigating Growth and Transformation Through 2032
The global chemical industry stands at a critical inflection point where operational resilience, regulatory compliance, and digital transformation converge. As chemical manufacturers scale production to meet evolving demand while navigating stringent environmental mandates, the role of the Distributed Control System (DCS) has shifted from a foundational utility to a strategic asset. PW Consulting has released a comprehensive market research study on the Worldwide Chemical Industry Distributed Control System Market, designed to equip executive leadership teams, investors, and technology strategists with the foresight required to make decisive moves throughout 2026 and beyond. This report does not merely track historical performance; it constructs a forward-looking intelligence framework that maps technology adoption, competitive positioning, and market velocity across the forecast horizon of 2026 to 2032.
Market Trajectory and Structural Growth Dynamics
Drawing on a rigorous multi-year analysis spanning historical data from 2020 through 2025 and projecting into the 2026 to 2032 forecast period, the research quantifies a market that has demonstrated sustained expansion. The overall market size reached approximately 6.51 billion USD in 2025, with the trajectory accelerating toward a projected valuation of 6.87 billion USD in 2026 and continuing upward to approach 9.47 billion USD by 2032. This growth is underpinned by a compound annual growth rate of 5.5 percent, reflecting steady capital investment in process automation across chemical manufacturing facilities worldwide. The consistency of this growth curve signals more than cyclical expansion; it indicates structural demand driven by modernization initiatives, aging infrastructure replacement, and the integration of advanced control architectures capable of supporting higher product quality and operational efficiency in complex chemical reactions.
For decision-makers evaluating capital allocation in 2026, these figures provide a baseline for scenario planning. The research dissects the growth vectors without oversimplifying them, allowing organizations to benchmark internal procurement timelines against broader market momentum. Understanding where the market is headed enables procurement, engineering, and IT leadership to align system refresh cycles, capacity expansions, and digital upgrade roadmaps with external demand signals rather than reacting to retrospective benchmarks.
Structural Segmentation and Value Distribution Across the Ecosystem
The report maps the market across three critical dimensions: regional deployment patterns, component-level value distribution, and end-use application concentrations. Rather than presenting these as static snapshots, the analysis frames them as interdependent variables that shape procurement strategy, vendor selection, and localization requirements. Regional dynamics reveal where investment density is highest and how geographic factors influence technology adoption speeds, supply chain readiness, and integration with existing plant infrastructure. Component-level breakdowns clarify how hardware, software, and services contribute to total system value, highlighting the shifting emphasis toward software-defined capabilities and lifecycle support services that extend beyond initial installation. End-use segmentation illuminates which chemical manufacturing verticals are driving control system demand, from large-scale petrochemical complexes to specialty chemical batch operations, fine chemical precision manufacturing, and agrochemical production environments.
Executives reviewing these structural insights gain a multidimensional view of where competitive pressure concentrates and where differentiation opportunities emerge. The research emphasizes how regional investment patterns intersect with local regulatory environments and how component mix evolution reflects broader industry trends toward modular, software-centric architectures that reduce long-term operational costs while improving data visibility and cybersecurity posture.
Competitive Landscape and the Push Toward Software-Defined Automation
The worldwide chemical DCS market is characterized by a moderately concentrated competitive environment, with leading players collectively commanding a substantial share of total revenue. The top three firms account for approximately 42.5 percent of market revenue, while the top five extend that influence to roughly 58.8 percent. This concentration reflects the dominance of established automation vendors with deep process industry expertise, yet it also underscores the dynamic nature of the competitive field as new capabilities reshape buying criteria. The research profiles the core enterprises shaping this landscape, including Emerson Electric Co., Honeywell International Inc., ABB Ltd., Siemens AG, Yokogawa Electric Corporation, Schneider Electric SE, Rockwell Automation Inc., Mitsubishi Electric Corporation, Azbil Corporation, and Hitachi Ltd.
Each profiled company brings distinct technological philosophies and application strengths to the chemical sector. Emerson Electric Co. offers the DeltaV distributed control system optimized for chemical and specialty chemical plants, emphasizing batch process control, cybersecurity enhancements, and software-defined automation that supports higher product quality in complex chemical reactions. Honeywell International Inc. provides the Experion PKS DCS tailored for chemical and petrochemical applications, with capabilities spanning real-time process optimization, safety system integration, and AI-assisted operations designed to improve reliability and compliance. ABB Ltd. delivers the 800xA and Symphony Plus DCS solutions, focusing on seamless modernization, field device integration, and enhanced connectivity for efficient and reliable chemical plant operations. Siemens AG supplies the SIMATIC PCS 7 DCS for chemical facilities, with ongoing upgrades addressing cybersecurity, efficiency gains in ethylene production, and preparation for future digital transformation in process industries. Yokogawa Electric Corporation offers the CENTUM VP integrated production control system, emphasizing autonomous operations, safety, and long-term reliability across global chemical installations.
Vendor-Specific Innovation and Strategic Differentiation
The competitive narrative extends beyond traditional process control into software-defined architectures and lifecycle modernization. Schneider Electric SE provides the EcoStruxure Foxboro software-defined DCS, engineered for flexible, future-ready automation in chemical and hybrid process industries with embedded cybersecurity and real-time intelligence. Rockwell Automation Inc. delivers the PlantPAx DCS suitable for specialty chemical batch processing, supporting migration from legacy systems and advanced automation in chemical manufacturing environments. Mitsubishi Electric Corporation, Azbil Corporation, and Hitachi Ltd. round out the field with DCS solutions that integrate into broader automation portfolios, emphasizing reliable control, operational efficiency, safety, and digital integration across chemical sector applications.
Recent product developments illustrate how these vendors are translating strategic vision into market-ready capabilities. In February 2026, Schneider Electric unveiled EcoStruxure Foxboro Software Defined Automation, positioning it as the industry's first open software-defined DCS for flexible, future-ready industrial automation in process industries including chemicals. Earlier that year, in January 2026, Emerson Electric Co. released DeltaV version 16.LTS with software-defined capabilities designed to reduce automation costs, enhance operational intelligence, improve data visibility, and strengthen cybersecurity for chemical and process applications. Yokogawa Electric Corporation announced Release 7.01 of its CENTUM VP integrated production control system in June 2025, representing the 10th generation of the platform and supporting autonomous operations, safety, and sustainable control in chemical and petrochemical plants. In March 2026, ABB Ltd. released the Symphony Plus SPR2025 DCS update with Automation Extended functionality, enhanced connectivity, field device integration, OPC UA communication, and improved performance for chemical process modernization. These developments signal a clear industry pivot toward modular software architectures, cybersecurity-by-design, and intelligent operations support that reduce total cost of ownership while increasing adaptability to changing production requirements.
Regulatory Environment and Operational Compliance Pressures
Market growth does not occur in a vacuum. Regulatory frameworks are actively reshaping operational requirements and influencing technology selection across chemical manufacturing. One notable dynamic involves the U.S. Environmental Protection Agency's phasedown of high-GWP hydrofluorocarbons under the AIM Act, which imposes restrictions on use in refrigeration, air conditioning, and related chemical process equipment. Compliance dates spanning from 2025 to 2028 create a rolling adjustment period that impacts chemical industry operations and incentivizes investment in control systems capable of supporting process modifications, emissions monitoring, and compliance reporting. Such regulatory pressure reinforces the demand for DCS platforms that can integrate safety systems, optimize resource usage, and provide the data granularity required for audit-ready operations.
The research situates these regulatory forces within the broader market dynamics, illustrating how compliance mandates intersect with automation modernization. Organizations that align their DCS strategy with regulatory timelines can convert compliance obligations into operational advantages, using upgraded control architectures to improve process stability, reduce waste, and strengthen their sustainability positioning.
Report Architecture and Practical Decision Support
This market research study is structured to deliver actionable intelligence at multiple organizational levels. The report provides detailed market sizing and forecast outputs anchored in historical baselines and forward-looking projections, enabling finance and strategy teams to model revenue exposure, procurement budgets, and investment timing. Segmentation analysis breaks down market structure by region, component, and end use, giving executives the context needed to evaluate geographic expansion opportunities, technology mix decisions, and application-specific demand patterns. Competitive profiling delivers in-depth assessments of key companies, covering product positioning, recent releases, and strategic direction, so that procurement and engineering leaders can benchmark vendor offerings against internal requirements.
Beyond static data tables, the report integrates recent industry developments and regulatory context into a cohesive narrative that explains why certain technology trends are accelerating and where competitive vulnerabilities are emerging. The analysis connects product launches, platform upgrades, and software-defined transitions to broader operational objectives such as cybersecurity hardening, legacy system migration, batch process flexibility, and real-time operational intelligence. This approach allows readers to move from understanding what is happening in the market to determining what it means for their own technology roadmaps, vendor negotiations, and capital planning cycles.
Third-Party Chemical Distribution Market
Strategic Implications for 2026 Decision-Makers
For organizations making DCS-related decisions in 2026, the report provides a framework for evaluating trade-offs between immediate operational needs and longer-term transformation goals. The shift toward software-defined architectures, the emphasis on cybersecurity enhancements, and the integration of AI-assisted operations and real-time intelligence all point toward a market where flexibility and future readiness carry increasing weight in vendor selection. At the same time, the concentration of revenue among leading providers and the diversity of regional and application-specific demand mean that procurement strategies must balance proven reliability with the agility to adapt to evolving process requirements and regulatory expectations.
Capital planning teams can use the forecast trajectory to time system upgrades and capacity expansions in alignment with market momentum, while technology leaders can use the competitive and product development analysis to assess which platforms best support modernization objectives such as legacy migration, data visibility, and interoperable connectivity. The report also supports risk assessment by highlighting where regulatory compliance deadlines and technology transition cycles intersect, helping organizations sequence investments to avoid unplanned downtime, compliance gaps, or premature obsolescence.
Accessing the Full Intelligence Framework
The insights summarized here represent the strategic surface of a much deeper research asset. The complete Worldwide Chemical Industry Distributed Control System Market study contains detailed market sizing across forecast years, structural segmentation analysis, competitive profiling, recent product developments, regulatory impact assessment, and scenario-based guidance for procurement and technology planning. For executives and analysts who require granular data to support board-level presentations, vendor evaluations, and investment committee decisions, the full report delivers the comprehensive evidence base needed to move from directional understanding to precise action.
Worldwide Chemical Industry Distributed Control System Market
PW Consulting's analysis is designed for organizations that treat process control not as a maintenance expense but as a strategic enabler of quality, safety, compliance, and operational efficiency. Accessing the complete report provides the detailed intelligence necessary to calibrate 2026 strategies against the market trajectory extending through 2032, ensuring that technology investment decisions are informed by rigorous data, competitive context, and a clear view of where the chemical DCS market is headed.
For detailed analysis of this topic, please visit the official page: Worldwide Chemical Industry Distributed Control System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com