

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Disposable Surgical Electrodes Market to Hit $2.75B by 2032, 6.48% CAGR

Strategic Imperatives in the Global Disposable Surgical Electrodes Market: A 2026 Outlook
The worldwide market for disposable surgical electrodes is entering a decisive phase of expansion, driven by shifting surgical paradigms, stringent infection control protocols, and rapid technological iteration across electrosurgical platforms. As healthcare systems modernize operating room workflows and prioritize single-use instrumentation to mitigate cross-contamination risks, the demand for precision-engineered electrosurgical electrodes has become a critical component of surgical supply chain strategy. This market research report delivers a comprehensive, data-grounded assessment of industry trajectories, competitive dynamics, and regulatory forces shaping the sector through the end of the decade. For executives, procurement leaders, and clinical technology strategists, the findings provide an essential foundation for capital allocation, product portfolio planning, and market entry decisions in 2026 and beyond.
Market Trajectory and Structural Growth Drivers
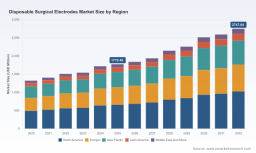
The industry has demonstrated a consistent upward trajectory over the past half-decade, reflecting both volume expansion and value appreciation across global healthcare markets. Historical performance data indicates that the market reached approximately 1,320.5 million USD in 2020, progressing to 1,403.52 million USD in 2021, 1,507.81 million USD in 2022, 1,539.25 million USD in 2023, 1,717.36 million USD in 2024, and 1,770.45 million USD in 2025. This established baseline anchors a forward-looking forecast period spanning 2026 through 2032, during which the market is projected to accelerate under favorable clinical and economic conditions. By 2026, revenue is expected to reach 1,838.53 million USD, followed by progression to 1,934.83 million USD in 2027, 2,144.23 million USD in 2028, 2,254.87 million USD in 2029, 2,512.51 million USD in 2030, 2,589.21 million USD in 2031, and culminating at 2,747.64 million USD in 2032. These projections reflect a compound annual growth rate of 6.48 percent, underscoring the sector's resilience and its alignment with broader minimally invasive surgical adoption curves.
Several macro-level catalysts converge to support this expansion. Surgical volume recovery and growth in ambulatory care centers, coupled with aging demographic profiles in developed economies, continue to elevate procedure frequencies across multiple specialties. Simultaneously, hospital administrators and surgical directors increasingly mandate single-use alternatives to reusable instrumentation, motivated by sterilization overhead, liability considerations, and workflow standardization objectives. The electrosurgical segment benefits directly from these procurement shifts, as disposable electrodes offer consistent performance characteristics, reduced reprocessing burdens, and alignment with modern surgical energy platform ecosystems. Furthermore, incremental innovation in electrode tip geometry, coating technologies, and shaft configurations expands clinical utility, enabling surgeons to perform cutting, coagulation, and ablation with greater precision across open, laparoscopic, and arthroscopic modalities.
Competitive Landscape and Strategic Positioning
The market operates within a moderately concentrated environment, with the top three participants collectively representing 42.15 percent of industry revenue and the top five firms accounting for 56.4 percent. This concentration indicates a landscape where established multinational players maintain strong clinical credibility and distribution infrastructure, while specialized and regional manufacturers compete through cost efficiency, niche procedural focus, and differentiated product features. Understanding the strategic posture of leading companies is essential for evaluating partnership opportunities, competitive threats, and whitespace positioning.
Medtronic, headquartered in Dublin, Ireland, maintains a prominent position through its Valleylab platform, offering PolyHesive corded patient return electrodes alongside a broad suite of electrosurgical instruments and disposable electrodes designed for both open and laparoscopic applications. The company's integrated energy ecosystem and global commercial reach provide significant leverage in institutional procurement frameworks. CONMED Corporation, based in Utica, New York, delivers a comprehensive line of electrosurgical disposables, including pencils, pads, and electrodes such as MacroLyte, SureFit, and ThermoGard dispersive electrodes, addressing the requirements of diverse surgical environments with an emphasis on reliability and procedural versatility.
Johnson & Johnson MedTech, operating through its Ethicon business unit in New Brunswick, New Jersey, supplies electrosurgical devices and disposable electrodes as integral components of its surgical energy portfolio. The company's cross-portfolio integration and strong surgeon relationships enable consistent placement of its electrode solutions across multiple specialties. ERBE Elektromedizin GmbH, located in Tübingen, Germany, manufactures single-use monopolar electrodes spanning spatula, needle, ball, snare, knife, and hook configurations, complemented by electrosurgical pencils with varied shaft sizes and tip geometries tailored for precise cutting and coagulation tasks. Kirwan Surgical Products, LLC, based in Marshfield, Massachusetts, specializes in microsurgical bipolar and monopolar products, including disposable bipolar forceps, pencils, and monopolar suction coagulators and electrodes, serving highly specialized procedural requirements.
Olympus Corporation, with global headquarters in Tokyo, Japan, contributes to the disposable laparoscopic electrode segment, offering specialized solutions such as DTAD electrodes for tonsil and adenoid procedures with monopolar coagulation capability. In the Asia-Pacific manufacturing corridor, Beijing iTrason Technologies produces disposable mini-invasive surgery electrodes and electrosurgical unit electrodes applicable to orthopedic, neurosurgical, arthroscopic, and general use cases. Canwell Medical, based in China, manufactures disposable RF plasma surgical electrodes targeting sports medicine and related applications. Promed, also operating within the Chinese medical device ecosystem, supplies disposable mini-invasive, ENT, laparoscopic, orthopedic, and arthroscopic electrosurgical electrodes for cutting, coagulation, and ablation routines. Hangzhou Valued Medtech Co., Ltd., known commercially as Weide Medical and headquartered in Hangzhou, China, produces disposable electrosurgical hook electrodes and complementary laparoscopic instruments. Progressive Medical Inc., located in St. Louis, Missouri, offers PTFE-coated non-stick disposable electrosurgical electrodes, tips in blade, L-hook, J-hook, and needle configurations, LLETZ tips, and associated pencils and ground pads, emphasizing anti-eschar functionality. Shining World Health Care Co., Ltd., operating from Taiwan as Shinmed, manufactures disposable electrosurgical electrodes in blade, needle, ball, loop, and angled formats, together with pencils and accessories, supporting broad procedural coverage across multiple clinical settings.
Medical Electrodes Market
This diversified field of incumbents, regional manufacturers, and specialty innovators creates a competitive structure in which differentiation increasingly depends on coating performance, tip configuration flexibility, regulatory clearance velocity, and distribution alignment with surgical energy vendors. Companies that can synchronize product development with procedural demand trends and streamline supply chain reliability are best positioned to capture share as the market expands.
Regulatory, Reimbursement, and Operational Dynamics
Market evolution is heavily influenced by regulatory frameworks, safety standards, and reimbursement structures that govern product clearance, clinical deployment, and commercial viability. In the United States, disposable electrosurgical electrodes and related devices, classified under product code GEI, are regulated as Class II medical devices under 21 CFR 878.4400 and typically require 510(k) premarket notification for market clearance. This pathway shapes product launch timelines, competitive sequencing, and the strategic importance of predicate device selection. Recent regulatory activity illustrates the ongoing pace of market entry and innovation. In August 2025, Agnes Medical Co., Ltd. secured FDA 510(k) clearance for its RFMagik electrosurgical device incorporating single-use electrodes for dermatologic and general surgical electrocoagulation and hemostasis. Earlier that year, in June 2025, CnS Medical Co., Ltd. obtained clearance for the DELPHI System, including DELPHI PLUS and DISCORE single-use bipolar electrosurgical electrodes designed for tissue coagulation, ablation, and hemostasis in arthroscopic surgery. Agnes Medical subsequently received clearance in April 2025 for the RFMagik Lite electrosurgical device with single-use electrodes intended for dermatologic and general surgical procedures. More recently, in March 2026, Technomed Europe cleared a new line of disposable concentric needle electrodes for physical medicine and rehabilitation applications.
Worldwide Disposable Surgical Electrodes Market
Beyond premarket clearance, manufacturers must ensure that single-use electrosurgical electrodes comply with IEC 60601-1, IEC 60601-1-2, and IEC 60601-2-2 electrical safety and performance standards, reinforcing the technical rigor required for market participation. Sterilization protocols also constitute a critical operational parameter, as sterile single-use electrodes are typically EO gas sterilized with a three-year shelf life in many cleared devices. These parameters influence inventory planning, logistics design, and hospital procurement cycles. Reimbursement considerations further shape commercial strategy, as electrosurgical procedures utilizing disposable electrodes are billed under various CPT codes depending on specialty, including general surgery, gynecology, and urology. Medicare payments vary according to facility versus physician office settings and incorporate geographic adjustments, requiring manufacturers and service providers to understand coding pathways and payment differentials when positioning products across care environments.
From a materials and performance standpoint, manufacturers increasingly employ PTFE coatings on disposable monopolar electrodes to reduce eschar build-up and improve non-stick performance during surgery. This engineering trend reflects a broader emphasis on procedural efficiency, instrument longevity during a case, and the reduction of intraoperative interruptions caused by electrode fouling. As coating technologies mature and become more widely adopted, they contribute to product differentiation and can influence formulary preferences in high-volume surgical centers.
Segmentation Architecture and Strategic Interpretation
The report maps the market across multiple segmentation dimensions to clarify where revenue concentration, growth momentum, and competitive intensity are most pronounced. Analysis by region captures the relative scale and growth posture of North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, providing context for distribution strategy, market entry timing, and localized regulatory navigation. Product-type segmentation distinguishes among monopolar electrodes, bipolar electrodes, and patient return electrodes, illuminating the differing clinical roles, procedural demands, and commercial characteristics of each category. Procedure-based segmentation further decomposes demand across general surgery, cardiovascular surgery, gynecological surgery, orthopedic surgery, and other applications, enabling stakeholders to align product development and marketing emphasis with the procedural areas generating the strongest consumption trends.
While detailed numerical splits for each region, product type, and procedure are reserved for the full report, the structural composition of the market reveals clear strategic implications. The interplay between segmental demand and competitive positioning suggests that growth will not be uniform; rather, it will be shaped by procedural volume dynamics, specialty adoption rates, and the ability of suppliers to match electrode configurations to specific surgical workflows. Readers seeking precise segment valuations, share estimates, and forward-looking segment projections will find the complete dataset essential for scenario modeling and portfolio prioritization.
What the Full Report Delivers
This market research study is designed to supply decision-makers with a rigorous, operationally useful intelligence framework. The full publication includes historical and forecast revenue analysis, segmentation breakdowns, competitive profiling, regulatory mapping, and strategic recommendations calibrated to the 2026 to 2032 horizon. It integrates primary and secondary research methodologies to triangulate market size, growth pathways, and participant positioning, ensuring that conclusions rest on a defensible analytical foundation. In addition to macro trends, the report examines product development directions, procurement behavior, sterilization and shelf-life considerations, reimbursement context, and the competitive moves that are reshaping market shares. The objective is to equip executives with the clarity required to evaluate expansion opportunities, assess vendor and partner suitability, and anticipate regulatory and technological shifts that will influence purchasing decisions and product roadmaps.
Strategic Value for 2026 Decision-Making
As organizations plan capital deployment, product launches, and market expansion during 2026, access to precise, forward-looking intelligence becomes a competitive necessity. The disposable surgical electrodes market is transitioning from a broadly mature supply environment into a more dynamic landscape characterized by technological refinement, regulatory velocity, and regionally varied growth patterns. Leaders who understand the underlying drivers of demand, the posture of incumbent and emerging competitors, and the operational requirements imposed by safety standards and reimbursement structures will be better prepared to make informed strategic commitments. This report provides that perspective, balancing high-level market direction with the detailed segmentation, company-level profiles, and procedural insights needed to translate market awareness into actionable strategy.
For stakeholders seeking complete segment valuations, regional revenue trajectories, competitive share decompositions, and granular forecast tables across the 2026 to 2032 period, the full report delivers the comprehensive dataset necessary for detailed planning. Accessing the complete analysis ensures that strategic decisions are grounded in the full scope of available evidence, enabling organizations to navigate this growth phase with confidence and precision.
For detailed analysis of this topic, please visit the official page: Worldwide Disposable Surgical Electrodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com