

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Ceramic Wafer Boat Market to Reach $937.53M by 2032 with 8.12% CAGR

Navigating the Precision Sector: Strategic Insights into the Global Ceramic Wafer Boat Market Through 2032
The semiconductor equipment supply chain is increasingly defined by the reliability of its consumable components. Among these, ceramic wafer boats serve as a critical interface between the wafer and the processing environment, directly influencing yield, contamination control, and thermal efficiency. As the global industry transitions toward more complex node architectures and higher temperature processing regimes, the demand for advanced ceramic carriers has accelerated. Our latest comprehensive study, the Worldwide Ceramic Wafer Boat Market 2026-2032, offers a granular examination of this evolving landscape, providing decision-makers with the intelligence required to navigate capacity planning, supply chain resilience, and competitive positioning.
This analysis is not merely a retrospective of past performance but a forward-looking strategic tool designed for 2026 corporate planning. With the market having demonstrated steady growth over the historical period from 2020 to 2025, reaching a base valuation of USD 542.8 Million in 2025, the trajectory indicates a robust expansion phase. The forecast period through 2032 projects the market to ascend toward USD 937.53 Million, underpinned by a Compound Annual Growth Rate (CAGR) of 8.12 Percent. Such growth reflects the broader macro trend of expanding semiconductor manufacturing capacity, particularly concentrated in the Asia-Pacific region, where the imperative for high-temperature resistance and chemical stability in wafer processing remains paramount.
Worldwide Ceramic Wafer Boat Market
The Macro Economic Trajectory and Segment Intelligence
Understanding the magnitude of opportunity requires a clear view of the historical baseline and the projected surge. The market has grown consistently from USD 382.4 Million in 2020, navigating supply chain disruptions and geopolitical shifts to achieve consecutive year-over-year gains. By 2026, the market size is anticipated to cross the USD 598.53 Million threshold. This growth is not uniform; it is driven by specific technological imperatives. As logic and memory chips demand tighter tolerances, the material science behind wafer boats becomes a bottleneck and a differentiator.
Worldwide Wafer Boat Market
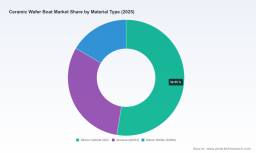
Our research dissects the market across three primary dimensions: material type, application, and region. While specific regional share percentages and application breakdown amounts are detailed exclusively in the full report to protect client strategic confidentiality, the overarching dynamics are clear. The shift toward Silicon Carbide (SiC) continues to dominate the material landscape due to its superior thermal stability exceeding 1600°C and lower contamination risks compared to traditional quartz alternatives. High-purity quartz remains a viable option for less demanding processes, such as annealing and oxidation up to 1200°C, but the high-performance sector is increasingly favoring advanced ceramics.
Similarly, the application landscape is shifting. Processes such as Diffusion and Oxidation, Chemical Vapor Deposition (CVD), and LPCVD and Epitaxy represent the core consumption drivers. As foundries and integrated device manufacturers push for higher efficiency, the choice of boat material directly correlates with process yield. The report provides a deep dive into how these applications are evolving and which material types are gaining traction within each process flow, without exposing the precise volume splits that could alert competitors during strategy formulation.
Competitive Landscape and Strategic Positioning
The global market for ceramic wafer boats exhibits a moderately concentrated structure, with the top three players holding a combined market share of 48.5 Percent and the top five reaching 62.3 Percent. This concentration suggests that while market leaders maintain significant influence, there remains substantial room for specialized players and regional participants to capture niche value. The competitive arena is diverse, featuring established Japanese and American corporations alongside a robust cohort of Chinese manufacturers who have significantly upgraded their technical capabilities in recent years.
Key incumbents such as Kyocera Corporation continue to leverage their reputation for fine ceramic technology, utilizing high-purity sapphire and advanced ceramics that emphasize plasma and heat resistance with minimal particle generation. CoorsTek, Inc. maintains its status as a global leader in engineered ceramics, providing high-purity options with exceptional thermal and chemical stability suited for high-temperature processes. Ferrotec Corporation supports the ecosystem with quartz and silicon carbide solutions optimized for thermal stability and chemical wear resistance, maintaining operations across key semiconductor hubs in the United States, Japan, and Taiwan.
Simultaneously, the entry and expansion of Chinese manufacturers have reshaped supply dynamics. Companies like Semicorex and Semicera Semiconductor Technology Co., Ltd. specialize in customized silicon carbide coated and SiC ceramic wafer boats, catering specifically to diffusion and oxidation configurations while serving European and American markets. Others, such as 3X Ceramic Parts Company Limited and VeTek Semiconductor, focus on high-temperature resistance up to 1650°C and corrosion resistance, providing viable alternatives for cost-sensitive yet performance-critical applications. Shenyang Starlight Advanced Ceramics Co., Ltd., with over 30 years in SiC solutions, continues to develop recrystallized silicon carbide and quartz boats, recently showcasing their capabilities at the 18th China International Advanced Ceramics Exhibition in January 2026. Gorgeous Ceramic and Hunan DeZhi New Material Co., Ltd. further contribute to the supply base with custom and standard options emphasizing contamination resistance and CVD SiC coated variants.
Recent developments indicate an intensification of innovation. In August 2025, Engineering Ceramic Co., Ltd. introduced recrystallized silicon carbide (RSiC) wafer boats with CVD-SiC coating options in three distinct material types tailored for advanced industries. These moves underscore a competitive environment where material differentiation and coating technologies are becoming the primary battlegrounds for market share.
Regulatory Headwinds and Operational Risks
Strategic planning in 2026 must account for a complex regulatory environment. Export controls on semiconductor manufacturing equipment and related components, including advanced ceramic parts, were refined under the Foreign-Produced Direct Product Rule to address national security concerns in advanced computing and semiconductor production. These regulations introduce potential friction in cross-border supply chains, particularly for companies sourcing high-purity materials or finished components across jurisdictional lines.
The availability of raw materials also remains a critical variable. Silicon carbide serves as the primary core component for high-performance ceramic wafer boats, and fluctuations in the supply of high-grade SiC or the capacity to process it into recrystallized forms can impact production timelines. While high-purity quartz offers an alternative for specific temperature ranges, the industry's migration toward higher performance standards limits its long-term utility in advanced nodes. Decision-makers must evaluate supplier diversification strategies to mitigate these risks, a topic extensively covered in the risk assessment section of our full market study.
Strategic Value for 2026 Decision-Makers
Why does this specific market intelligence matter for your organization in 2026? The answer lies in the intersection of CapEx planning and operational continuity. As the market grows from USD 598.53 Million in 2026 to over USD 900 Million by 2031, the demand for reliable wafer carriers will intensify. Procurement teams need to know which suppliers are scaling capacity and which are focusing on niche high-margin products. R&D departments need to understand the material science trends that will define the next generation of process compatibility.
This report serves as a blueprint for these decisions. It allows stakeholders to benchmark their current supplier base against the competitive landscape, assess the viability of vertical integration versus outsourcing, and identify emerging markets where capacity expansion is outpacing local supply. By understanding the concentration dynamics and the specific technological roadmaps of key players like Kyocera, CoorsTek, and the expanding cohort of specialized Chinese manufacturers, companies can negotiate better terms, secure long-term supply agreements, or identify M&A targets.
What the Full Report Delivers
While this overview provides the strategic context, the full Worldwide Ceramic Wafer Boat Market 2026-2032 study contains the actionable data required to execute these strategies. The document includes comprehensive segmentation analysis that breaks down revenue and volume trends across all major regions and application verticals without the noise found in aggregate industry reports. It provides a detailed company profiling section that examines the financial health, production capacity, and strategic moves of the key market participants listed above.
Furthermore, the report includes a thorough analysis of market dynamics, covering drivers, restraints, and opportunities with specific attention to the regulatory landscape and raw material supply chains. The forecast model offers multiple scenarios, allowing clients to stress-test their assumptions against varying rates of semiconductor capex deployment. Customization options are available for those who require deep dives into specific countries, material grades, or downstream semiconductor applications.
In an industry where precision is everything, relying on aggregate data is insufficient. The ceramic wafer boat market is a critical enabler of semiconductor processing, and its nuances dictate the efficiency of the entire fabrication line. We invite you to access the full report to secure the detailed intelligence necessary to optimize your strategic position in this high-growth sector. The window to align supply chain strategies with the upcoming cycle of capacity expansion is open now, and the data required to navigate it is available in our complete market study.
For detailed analysis of this topic, please visit the official page: Worldwide Ceramic Wafer Boat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com