

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global ESD Packing Market Hits $5,035M in 2025, Poised for 8.1% CAGR to 2032

Navigating the Static: Strategic Imperatives in the Global ESD Packing Market (2026-2032)
Executive Overview
The worldwide electrostatic discharge (ESD) packing market is entering a defining growth cycle. As electronics manufacturing becomes increasingly miniaturized and sensitive, the packaging sector responsible for protecting these components must evolve beyond basic containment. Our latest research, Worldwide ESD Packing Market, provides a comprehensive roadmap for stakeholders navigating this complex landscape between 2026 and 2032.
Based on historical performance from 2020 through 2025, the market has demonstrated consistent resilience. The total revenue is projected to expand from approximately 5,035.0 million USD in the base year to roughly 8,685.19 million USD by 2032. This trajectory represents a compound annual growth rate (CAGR) of 8.1 percent during the forecast period. For strategic planners, this growth is not merely a number; it signals a structural shift in how high-value goods are secured, transported, and regulated globally.
The Macro Landscape: Growth Drivers and Constraints
Several converging forces are fueling this expansion. The proliferation of consumer electronics, the relentless demand in semiconductor manufacturing, and the electrification of automotive systems are primary demand engines. However, growth is not uniform. The market is characterized by a moderate concentration level, with the top three competitors holding a combined share of 32.4 percent and the top five reaching 45.85 percent. This fragmentation suggests ample opportunity for niche players while indicating that scaling requires significant operational efficiency or specialized technological advantages.
Supply chain dynamics also play a critical role. Polyethylene (PE) remains the dominant raw material due to its cost-effectiveness and versatility. Yet, reliance on conventional polymers is becoming a liability. The industry is witnessing a pivot toward specialized polymers and conductive fillers, such as carbon black, which inevitably contribute to higher production costs compared to standard materials. Strategic procurement and material innovation are now central to margin preservation.
Worldwide ESD Packing Market
Regulatory Tailwinds and Headwinds
Compliance is no longer a backend function; it is a front-line strategic driver. In the United States, legislative momentum is accelerating. California's SB 54 Plastic Pollution Prevention and Packaging Producer Responsibility Act mandates that producers ensure 100 percent of single-use packaging is recyclable or compostable by 2032. This comes with escalating targets for recycled content and recycling rates. Similarly, Oregon's Plastic Pollution and Recycling Modernization Act has initiated enforcement with producer responsibility fees, and Maryland has recently signed its own packaging EPR law as the sixth U.S. state to do so.
These regulations compel manufacturers to rethink material composition fundamentally. The pressure is not just on end-users but extends through the supply chain to packaging producers. Companies that fail to align their product portfolios with these evolving legal frameworks risk obsolescence or significant penalty costs. Our report dissects these regulatory timelines to help firms anticipate compliance costs and adjust their R&D pipelines accordingly.
Product and End-User Segmentation Dynamics
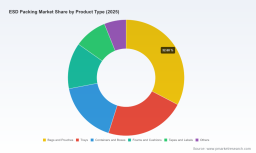
The market structure is diverse, spanning various physical formats and industry verticals. In terms of product types, solutions range from flexible bags and pouches to rigid trays, containers, boxes, foams, cushions, tapes, and labels. Each format serves specific protection requirements based on the sensitivity of the component and the logistics environment. The shift in demand is visible across these categories, with a notable trend toward solutions that offer both static dissipation and environmental sustainability.
Regarding end-user industries, the demand base is broad. Consumer electronics and semiconductor manufacturing represent significant portions of the addressable market, driven by the need for precision protection during assembly and transport. Automotive electronics and aerospace and defense sectors also contribute substantially, often requiring higher durability and certification standards. Healthcare applications, while smaller in volume, demand strict hygiene and safety compliance alongside ESD protection. Understanding the specific pain points of each vertical is crucial for targeted marketing and product development.
Competitive Landscape and Strategic Movements
The competitive environment is active and innovation-driven. Major players are headquartered across the United States, Europe, and Asia, reflecting the global nature of electronics manufacturing. Key entities such as DESCO Industries Inc., 3M Company, and Sealed Air Corporation provide a wide range of static dissipative and shielding solutions. Meanwhile, large packaging conglomerates like Smurfit Kappa Group and DS Smith plc are leveraging their corrugated and paper-based expertise to develop ESD-safe alternatives for electronics distribution.
Recent developments highlight a clear industry pivot toward sustainability and dual-protection features. In mid-2025, Cortec Corporation launched EcoSonic ESD Paper, offering a sustainable recyclable paper alternative to standard plastic bags with dual ESD and corrosion protection. Similarly, EcoCortec introduced films with post-consumer recycled content, and Daubert Cromwell unveiled poly films combining corrosion inhibition and static dissipation for automotive and aerospace sectors. Weber Verpackungen even introduced what was noted as the world's first ESD Paper Bag as a green alternative. These moves indicate that the next battleground for market share is material innovation that satisfies both safety and environmental mandates.
Regional players are also making strides. Nefab Group continues to emphasize reusable and sustainable systems for logistics across electronics, automotive, and aerospace. Dou Yee Enterprises in Singapore tailors solutions for semiconductor manufacturing, while Teknis Limited and GWP Group in the UK focus on custom conductive and dissipative solutions. The presence of specialized firms like Caltex Plastics, Indepak, and Kiva Container underscores the demand for custom thermoformed and multi-layer packaging that standard off-the-shelf products cannot meet.
ESD Grounding Mats Market
Strategic Value for 2026 Decision-Making
Why does this specific research matter for 2026 planning? Because the margin for error is shrinking. The intersection of regulatory pressure, material cost volatility, and technological requirements creates a complex decision matrix. Companies cannot afford to rely on outdated market estimates or generalized industry knowledge.
Our study provides the granularity needed to model future revenue streams accurately. It analyzes the shifting balance between conventional plastic solutions and emerging sustainable alternatives. It maps the competitive intensity across regions without exposing sensitive granular percentages that would compromise the strategic advantage of early readers. Instead, it offers qualitative insights into where capacity is expanding and where consolidation is likely.
For procurement managers, the report offers context on raw material trends, helping to anticipate cost fluctuations related to conductive fillers and polymer availability. For product developers, the analysis of recent launches provides a benchmark for innovation priorities. For executives, the competitive concentration data informs M&A strategy and partnership opportunities. The goal is to equip leadership with the intelligence required to allocate capital efficiently in a market projected to gain over 3,600 million USD in revenue over the forecast period.
Conclusion: Accessing the Full Intelligence
The Worldwide ESD Packing Market is poised for robust expansion, but realizing value within this growth requires navigating a maze of regulatory changes, material science advancements, and competitive maneuvers. The 8.1 percent CAGR is an invitation, but the path to capturing that growth is fraught with nuances that only deep data can reveal.
This article serves as a strategic preview. To build a fully informed 2026 roadmap, stakeholders need access to the complete segmentation analysis, detailed competitor profiles, and specific regional trajectory data contained within the full report. We invite you to explore the comprehensive findings of our Worldwide ESD Packing Market research to secure the detailed intelligence necessary for decisive action.
For detailed analysis of this topic, please visit the official page: Worldwide ESD Packing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com