

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
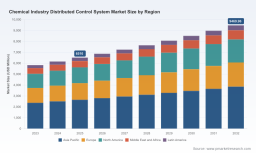
PW Consulting: Global Chemical DCS Market Reaches $6.51B in 2025, Projects 5.5% CAGR to $9.47B by 2032

Strategic Intelligence for the Chemical DCS Landscape: Navigating Growth and Transformation Through 2032
The global chemical industry stands at a critical inflection point where operational resilience, regulatory compliance, and digital transformation converge. As chemical manufacturers scale production to meet evolving demand while navigating stringent environmental mandates, the role of the Distributed Control System (DCS) has shifted from a foundational utility to a strategic asset. PW Consulting has released a comprehensive market research study on the Worldwide Chemical Industry Distributed Control System Market, designed to equip executive leadership teams, investors, and technology strategists with the foresight required to make decisive moves throughout 2026 and beyond. This report does not merely track historical performance; it constructs a forward-looking intelligence framework that maps technology adoption, competitive positioning, and market velocity across the forecast horizon of 2026 to 2032.
Market Trajectory and Structural Growth Dynamics
Drawing on a rigorous multi-year analysis spanning historical data from 2020 through 2025 and projecting into the 2026 to 2032 forecast period, the research quantifies a market that has demonstrated sustained expansion. The overall market size reached approximately 6.51 billion USD in 2025, with the trajectory accelerating toward a projected valuation of 6.87 billion USD in 2026 and continuing upward to approach 9.47 billion USD by 2032. This growth is underpinned by a compound annual growth rate of 5.5 percent, reflecting steady capital investment in process automation across chemical manufacturing facilities worldwide. The consistency of this growth curve signals more than cyclical expansion; it indicates structural demand driven by modernization initiatives, aging infrastructure replacement, and the integration of advanced control architectures capable of supporting higher product quality and operational efficiency in complex chemical reactions.
For decision-makers evaluating capital allocation in 2026, these figures provide a baseline for scenario planning. The research dissects the growth vectors without oversimplifying them, allowing organizations to benchmark internal procurement timelines against broader market momentum. Understanding where the market is headed enables procurement, engineering, and IT leadership to align system refresh cycles, capacity expansions, and digital upgrade roadmaps with external demand signals rather than reacting to retrospective benchmarks.
Structural Segmentation and Value Distribution Across the Ecosystem
The report maps the market across three critical dimensions: regional deployment patterns, component-level value distribution, and end-use application concentrations. Rather than presenting these as static snapshots, the analysis frames them as interdependent variables that shape procurement strategy, vendor selection, and localization requirements. Regional dynamics reveal where investment density is highest and how geographic factors influence technology adoption speeds, supply chain readiness, and integration with existing plant infrastructure. Component-level breakdowns clarify how hardware, software, and services contribute to total system value, highlighting the shifting emphasis toward software-defined capabilities and lifecycle support services that extend beyond initial installation. End-use segmentation illuminates which chemical manufacturing verticals are driving control system demand, from large-scale petrochemical complexes to specialty chemical batch operations, fine chemical precision manufacturing, and agrochemical production environments.
Executives reviewing these structural insights gain a multidimensional view of where competitive pressure concentrates and where differentiation opportunities emerge. The research emphasizes how regional investment patterns intersect with local regulatory environments and how component mix evolution reflects broader industry trends toward modular, software-centric architectures that reduce long-term operational costs while improving data visibility and cybersecurity posture.
Competitive Landscape and the Push Toward Software-Defined Automation
The worldwide chemical DCS market is characterized by a moderately concentrated competitive environment, with leading players collectively commanding a substantial share of total revenue. The top three firms account for approximately 42.5 percent of market revenue, while the top five extend that influence to roughly 58.8 percent. This concentration reflects the dominance of established automation vendors with deep process industry expertise, yet it also underscores the dynamic nature of the competitive field as new capabilities reshape buying criteria. The research profiles the core enterprises shaping this landscape, including Emerson Electric Co., Honeywell International Inc., ABB Ltd., Siemens AG, Yokogawa Electric Corporation, Schneider Electric SE, Rockwell Automation Inc., Mitsubishi Electric Corporation, Azbil Corporation, and Hitachi Ltd.
Each profiled company brings distinct technological philosophies and application strengths to the chemical sector. Emerson Electric Co. offers the DeltaV distributed control system optimized for chemical and specialty chemical plants, emphasizing batch process control, cybersecurity enhancements, and software-defined automation that supports higher product quality in complex chemical reactions. Honeywell International Inc. provides the Experion PKS DCS tailored for chemical and petrochemical applications, with capabilities spanning real-time process optimization, safety system integration, and AI-assisted operations designed to improve reliability and compliance. ABB Ltd. delivers the 800xA and Symphony Plus DCS solutions, focusing on seamless modernization, field device integration, and enhanced connectivity for efficient and reliable chemical plant operations. Siemens AG supplies the SIMATIC PCS 7 DCS for chemical facilities, with ongoing upgrades addressing cybersecurity, efficiency gains in ethylene production, and preparation for future digital transformation in process industries. Yokogawa Electric Corporation offers the CENTUM VP integrated production control system, emphasizing autonomous operations, safety, and long-term reliability across global chemical installations.
Vendor-Specific Innovation and Strategic Differentiation
The competitive narrative extends beyond traditional process control into software-defined architectures and lifecycle modernization. Schneider Electric SE provides the EcoStruxure Foxboro software-defined DCS, engineered for flexible, future-ready automation in chemical and hybrid process industries with embedded cybersecurity and real-time intelligence. Rockwell Automation Inc. delivers the PlantPAx DCS suitable for specialty chemical batch processing, supporting migration from legacy systems and advanced automation in chemical manufacturing environments. Mitsubishi Electric Corporation, Azbil Corporation, and Hitachi Ltd. round out the field with DCS solutions that integrate into broader automation portfolios, emphasizing reliable control, operational efficiency, safety, and digital integration across chemical sector applications.
Recent product developments illustrate how these vendors are translating strategic vision into market-ready capabilities. In February 2026, Schneider Electric unveiled EcoStruxure Foxboro Software Defined Automation, positioning it as the industry's first open software-defined DCS for flexible, future-ready industrial automation in process industries including chemicals. Earlier that year, in January 2026, Emerson Electric Co. released DeltaV version 16.LTS with software-defined capabilities designed to reduce automation costs, enhance operational intelligence, improve data visibility, and strengthen cybersecurity for chemical and process applications. Yokogawa Electric Corporation announced Release 7.01 of its CENTUM VP integrated production control system in June 2025, representing the 10th generation of the platform and supporting autonomous operations, safety, and sustainable control in chemical and petrochemical plants. In March 2026, ABB Ltd. released the Symphony Plus SPR2025 DCS update with Automation Extended functionality, enhanced connectivity, field device integration, OPC UA communication, and improved performance for chemical process modernization. These developments signal a clear industry pivot toward modular software architectures, cybersecurity-by-design, and intelligent operations support that reduce total cost of ownership while increasing adaptability to changing production requirements.
Regulatory Environment and Operational Compliance Pressures
Market growth does not occur in a vacuum. Regulatory frameworks are actively reshaping operational requirements and influencing technology selection across chemical manufacturing. One notable dynamic involves the U.S. Environmental Protection Agency's phasedown of high-GWP hydrofluorocarbons under the AIM Act, which imposes restrictions on use in refrigeration, air conditioning, and related chemical process equipment. Compliance dates spanning from 2025 to 2028 create a rolling adjustment period that impacts chemical industry operations and incentivizes investment in control systems capable of supporting process modifications, emissions monitoring, and compliance reporting. Such regulatory pressure reinforces the demand for DCS platforms that can integrate safety systems, optimize resource usage, and provide the data granularity required for audit-ready operations.
The research situates these regulatory forces within the broader market dynamics, illustrating how compliance mandates intersect with automation modernization. Organizations that align their DCS strategy with regulatory timelines can convert compliance obligations into operational advantages, using upgraded control architectures to improve process stability, reduce waste, and strengthen their sustainability positioning.
Report Architecture and Practical Decision Support
This market research study is structured to deliver actionable intelligence at multiple organizational levels. The report provides detailed market sizing and forecast outputs anchored in historical baselines and forward-looking projections, enabling finance and strategy teams to model revenue exposure, procurement budgets, and investment timing. Segmentation analysis breaks down market structure by region, component, and end use, giving executives the context needed to evaluate geographic expansion opportunities, technology mix decisions, and application-specific demand patterns. Competitive profiling delivers in-depth assessments of key companies, covering product positioning, recent releases, and strategic direction, so that procurement and engineering leaders can benchmark vendor offerings against internal requirements.
Beyond static data tables, the report integrates recent industry developments and regulatory context into a cohesive narrative that explains why certain technology trends are accelerating and where competitive vulnerabilities are emerging. The analysis connects product launches, platform upgrades, and software-defined transitions to broader operational objectives such as cybersecurity hardening, legacy system migration, batch process flexibility, and real-time operational intelligence. This approach allows readers to move from understanding what is happening in the market to determining what it means for their own technology roadmaps, vendor negotiations, and capital planning cycles.
Third-Party Chemical Distribution Market
Strategic Implications for 2026 Decision-Makers
For organizations making DCS-related decisions in 2026, the report provides a framework for evaluating trade-offs between immediate operational needs and longer-term transformation goals. The shift toward software-defined architectures, the emphasis on cybersecurity enhancements, and the integration of AI-assisted operations and real-time intelligence all point toward a market where flexibility and future readiness carry increasing weight in vendor selection. At the same time, the concentration of revenue among leading providers and the diversity of regional and application-specific demand mean that procurement strategies must balance proven reliability with the agility to adapt to evolving process requirements and regulatory expectations.
Capital planning teams can use the forecast trajectory to time system upgrades and capacity expansions in alignment with market momentum, while technology leaders can use the competitive and product development analysis to assess which platforms best support modernization objectives such as legacy migration, data visibility, and interoperable connectivity. The report also supports risk assessment by highlighting where regulatory compliance deadlines and technology transition cycles intersect, helping organizations sequence investments to avoid unplanned downtime, compliance gaps, or premature obsolescence.
Accessing the Full Intelligence Framework
The insights summarized here represent the strategic surface of a much deeper research asset. The complete Worldwide Chemical Industry Distributed Control System Market study contains detailed market sizing across forecast years, structural segmentation analysis, competitive profiling, recent product developments, regulatory impact assessment, and scenario-based guidance for procurement and technology planning. For executives and analysts who require granular data to support board-level presentations, vendor evaluations, and investment committee decisions, the full report delivers the comprehensive evidence base needed to move from directional understanding to precise action.
Worldwide Chemical Industry Distributed Control System Market
PW Consulting's analysis is designed for organizations that treat process control not as a maintenance expense but as a strategic enabler of quality, safety, compliance, and operational efficiency. Accessing the complete report provides the detailed intelligence necessary to calibrate 2026 strategies against the market trajectory extending through 2032, ensuring that technology investment decisions are informed by rigorous data, competitive context, and a clear view of where the chemical DCS market is headed.
For detailed analysis of this topic, please visit the official page: Worldwide Chemical Industry Distributed Control System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com