

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Sees Interlayer Films Market Hit $525.63M by 2032, 8% CAGR

Strategic Clarity for 2026: Navigating the Global SGP Interlayer Films Market
As multinational corporations accelerate their sustainability agendas and building codes tighten around fenestration performance, the SGP interlayer films sector stands at a critical inflection point. For executives mapping their procurement, capacity, and market-entry strategies in 2026, intuition is no longer a sufficient compass. The Worldwide SGP Interlayer Films Market research report from PW Consulting delivers the granular, forward-looking intelligence required to convert structural ambiguity into competitive advantage. Drawing on historical performance from 2020 through 2025 and projecting disciplined trajectories through 2032, this analysis equips leadership teams with the scenario-planning rigor needed to de-risk capital allocation across dynamic segments.
Macro Trajectory and the 2026 Investment Inflection
The global SGP interlayer films market has demonstrated resilient, compounding growth across the most recent evaluation window. Revenue expanded from approximately 212.45 million USD in 2020, climbing through successive annual milestones to reach 306.69 million USD by the 2025 base year. Fortifying this momentum, the forecast period projects a compound annual growth rate of 8.0 percent, propelling estimated market size to 343.05 million USD in 2026 and charting a sustained upward path toward 525.63 million USD by 2032. These headline figures do more than quantify expansion; they signal a structural shift in how engineers, architects, and procurement teams value interlayer performance. The consistent year-over-year uplift underscores that SGP films are transitioning from niche specialty inputs to core enablers of high-performance glazing, particularly as building owners and authorities demand enhanced post-breakage integrity, blast mitigation, and long-term optical clarity. For 2026 decision-makers, the strategic imperative is clear: product roadmaps, supplier contracts, and regional distribution architectures must be recalibrated to align with an 8 percent growth engine rather than static legacy demand curves.
What the Report Delivers: From Market Maps to Execution Playbooks
Beyond the aggregate growth narrative, this research translates top-line trajectories into actionable operational intelligence. The full publication dissects demand drivers, supply-chain bottlenecks, and competitive maneuvers with an emphasis on deployable strategy. Readers will encounter rigorous breakdowns across primary application vectors, end-user categories, and geographic corridors, each calibrated to reveal where margin pools concentrate and where volume scaling is most feasible. The report moves past descriptive categorization to interrogate the mechanics of purchasing behavior, specification cycles, and substitution risk within structural glazing, security and hurricane resistance, mobility applications, and adjacent specialty uses.
Supplier and distributor positioning receives similarly granular treatment, enabling executives to benchmark their own value propositions against incumbent capabilities and emerging capacity plays. Because the overarching market structure exhibits pronounced concentration, with the top three players commanding roughly 84.5 percent share and the top five capturing approximately 92.15 percent, the analysis isolates how incumbents leverage patented ionoplast formulations, vertical integration, and certification portfolios to defend high-margin installations. Simultaneously, the report surfaces the pathways through which authorized distributors, specialized laminators, and regional processors can capture share by tailoring thickness options, pre-laminated panel configurations, and region-specific compliance documentation. For procurement leaders, the study provides the comparative framework necessary to evaluate total cost of ownership, lead-time reliability, and specification risk across competing interlayer technologies.
Competitive Architecture: Four Profiles Shaping the Global Landscape
The current competitive arena is anchored by players with distinct technical pedigrees and geographic footprints. Trosifol, headquartered in Wiesbaden, Germany, operates as a leading provider of SentryGlas SGP interlayer films for structural glazing, offering high-strength ionoplast films with tear resistance approximately five times that of conventional PVB, specifically engineered for hurricane-resistant and high-load architectural environments. Its sustained R&D cadence is evident in the October 2024 launch of SentryGlas Expression 78/2, a newly introduced colored SGP interlayer designed for decorative structural glazing with enhanced UV stability, expanding aesthetic options without compromising structural performance.
Worldwide Window Films Market
Kuraray, based in Tokyo, Japan, develops and manufactures SentryGlas ionoplast interlayer films under the Trosifol brand, with particular specialization in ultra-thick SGP films reaching 6.38 mm for blast-resistant and seismic glazing applications worldwide. The company's mid-2024 certification milestone, wherein SentryGlas interlayers achieved EN 16613 conformity for use in overhead glazing applications across Europe, represents a critical market-access lever, reducing specification friction for engineering teams pursuing atriums, canopies, and elevated envelopes.
Everlam, located in Halen, Belgium, supplies SGP interlayer films including SentryGlas variants for safety and security glass laminates, with a clear operational focus on custom thicknesses for European and global structural projects. Its March 2025 capacity expansion, which lifted SGP lamination throughput by 20 percent at the Halen facility, directly responds to intensifying European demand for structural glass assemblies, reinforcing a supply posture calibrated to project pipelines rather than spot transactions.
Glastrotech, operating from Dallas, TX, USA, functions as an authorized distributor and processor of SentryGlas SGP interlayers for North American markets, providing pre-laminated panels for high-performance building facades. By bridging raw interlayer supply with finished-façade readiness, this distribution-and-processing model shortens lead times and reduces on-site fabrication risk, a differentiator that resonates with general contractors seeking schedule certainty in complex envelope installations.
Market Dynamics: Feedstocks, Regulation, and Trade Policy in Tension
Strategy in 2026 cannot be divorced from the external forces currently reshaping cost structures, compliance obligations, and market access. On the input side, recent pricing intelligence shows that polyvinyl butyral and ionomer resins, the essential feedstocks underpinning SGP film production, experienced spot price increases during the final quarter of 2024, driven by ethylene monomer tightness. This cost pressure interacts directly with margin management strategies, particularly for producers reliant on spot procurement rather than hedged or long-term supply agreements. Decision-makers evaluating supplier stability must therefore scrutinize feedstock contracting practices, blending flexibility, and pass-through mechanisms in commercial terms.
At the regulatory level, the European Union's Construction Products Regulation mandates CE marking for SGP interlayers deployed in load-bearing glass, with pRAVE testing required to validate post-breakage vision clarity. This obligation elevates technical documentation from a back-office task to a front-line specification requirement. Specifiers increasingly favor interlayers with pre-validated certification pathways, and manufacturers able to streamline test reporting and regional labeling gain measurable advantages in qualification cycles. In parallel, REACH Annex XVII restrictions on certain plasticizers have reinforced the structural appeal of SGP ionoplasts as non-PVC alternatives, positioning compliance-friendly chemistry as a commercial asset rather than a baseline expectation.
Trade policy introduces a further layer of complexity for North American procurement. US Section 301 duties remain in effect on SGP interlayers imported from China at the 25 percent level through 2025, altering total landed cost comparisons for buyers evaluating offshore-sourced volumes. For multinational programs, this shifts the calculus toward diversified sourcing, regional processing partnerships, and careful HTS classification diligence. The interplay of feedstock volatility, certification mandates, and tariff exposure means that 2026 sourcing strategies must weigh not only unit pricing but also the cumulative cost of qualification delays, logistics friction, and inventory buffers.
Why 2026 Decision-Makers Need This Intelligence Now
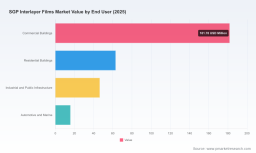
Many organizations still approach interlayer selection through the lens of single-project cost optimization, yet the evolving market structure rewards a portfolio-level perspective. As structural glazing, security and hurricane resistance, transportation, and supporting applications continue to diverge in performance requirements and procurement rhythms, blanket specifications create unnecessary exposure. The report's segmentation architecture allows executives to isolate where demand is scaling fastest, which end-user segments prioritize safety-performance certifications, and how regional dynamics influence both pricing tolerance and lead-time expectations. Commercial buildings, residential buildings, industrial and public infrastructure, and automotive and marine applications each follow distinct specification cycles and approval pathways; understanding these differences prevents misallocated R&D effort and poorly timed inventory commitments.
Equally important, the concentration profile of the market shapes negotiation leverage. With a limited group of firms controlling a dominant share of global supply, buyers and competitors alike must understand how incumbents defend premium installations, how distributors extend reach through pre-laminated panel offerings, and where new capacity is most likely to open margin opportunities rather than erode them. For suppliers, the analysis clarifies which product attributes and certifications unlock access to overhead glazing, blast-resistant assemblies, and decorative structural projects. For distributors and processors, it identifies where service differentiation, regional compliance readiness, and project-based panel configurations can translate into stickier relationships and higher realized margins.
From Insight to Execution: What Comes Next
The Worldwide SGP Interlayer Films Market study is structured to convert market visibility into executable strategy. It integrates historical benchmarking, forward projections, application and end-user dynamics, regional deployment logic, competitive profiling, and environmental and regulatory context into a single decision-support framework. Leaders can use the publication to stress-test capacity plans, refine product configurations for targeted segments, align procurement contracts with supply-risk realities, and prioritize geographic engagements where certification readiness and distribution architecture confer measurable advantage.
Worldwide SGP Interlayer Films Market
Because the market landscape is defined by concentrated supply, rising performance expectations, feedstock sensitivity, and evolving trade and compliance conditions, partial intelligence carries real downside risk. The full report provides the depth required to move from directional confidence to precision execution. To access the complete segmentation detail, competitive assessments, and scenario-based guidance that underpin this outlook, visit the official PW Consulting market research page and download the full Worldwide SGP Interlayer Films Market publication.
For detailed analysis of this topic, please visit the official page: Worldwide SGP Interlayer Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com