

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Laminating Lithium-ion Capacitor Market Hits $456M in 2025, Poised for 18.54% CAGR to 2032

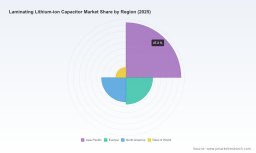
Navigating the Next Wave: Strategic Intelligence on the Worldwide Laminating Lithium-ion Capacitor Market (2026–2032)
The Strategic Imperative of Laminated Lithium-ion Capacitors
The global energy storage landscape is undergoing a structural shift. Lithium-ion capacitors (LICs) have emerged as a critical bridge technology, combining the rapid charge-discharge capabilities of supercapacitors with the higher energy density of lithium-ion chemistry. Within this category, laminated construction—particularly pouch and flexible-module formats—is rapidly becoming the architecture of choice for next-generation applications that demand slim form factors, scalable manufacturing, and improved thermal management. For executives, investors, and technology strategists, the question is no longer whether laminating LIC technology will scale, but how quickly capital, partnerships, and supply chain positioning must be deployed to capture value.
PW Consulting's latest Worldwide Laminating Lithium-ion Capacitor Market study has been designed specifically for that decision window. Covering historical performance from 2020 through the 2025 base year and extending a comprehensive forecast through 2032, the report translates macro momentum into operational intelligence. It is built to help businesses answer three foundational questions: where is the market heading, who is positioned to win, and what levers will separate commercially viable production from stranded assets.
Macro Trajectory: Reading the Curve Beyond the Headline
The numbers tell a story of accelerating adoption, but the strategic value lies in how that growth compounds across technology generations and application verticals. After a measured but steady climb through the early 2020s, the laminating LIC segment crossed into a new growth phase. The market generated approximately $324.94 million in 2023, expanded to $385.05 million in 2024, and reached $456.28 million in 2025. From that base year, the trajectory steepens markedly: the forecast projects $540.87 million in 2026, $641.15 million in 2027, $760.02 million in 2028, $900.93 million in 2029, $1.067 billion in 2030, $1.266 billion in 2031, and roughly $1.501 billion by 2032.
Worldwide Laminating Lithium-ion Capacitor Market
At a compound annual growth rate of 18.54 percent across the 2026–2032 forecast period, this is not a linear extension of prior trends. It is a structural inflection driven by manufacturing maturation, application pull, and an industry-wide pivot toward formats that can be integrated more flexibly into energy storage systems, industrial loads, and mobility platforms. The strategic implication is clear: companies that anchor their planning to conservative, slow-growth assumptions risk mis-timing capacity investments, partnership structures, and product roadmaps. A market expanding at this cadence rewards early alignment with the formats, certifications, and regional supply chains that end customers are beginning to specify.
That said, headline revenue figures are only the starting point. The actual strategic decisions—whether to invest in dry-electrode processes, which specification thresholds will win in particular verticals, how pricing dynamics evolve as activated-carbon sourcing shifts, and where incremental capacity should be located—depend on the segmentation detail and competitive intelligence that complete research provides. The high-level curve signals urgency; the detailed breakdown converts urgency into execution.
Laminating Machine Market
What the Report Covers: Operational Intelligence for Decision-Makers
PW Consulting's laminating LIC market study is structured as a practical decision-support instrument rather than a static data compilation. The report maps the evolution of market sizing from the historical window into a granular forecast framework, enabling readers to benchmark current product portfolios, capacity plans, and regional footprints against the direction of demand. A core focus is placed on laminate-format dynamics, including pouch and lamination-compatible electrode processes, thin-form-factor cells, and the manufacturing transitions that make high-volume production economically feasible.
The study dissects the market across multiple dimensions—technology and form factor, application segments, and regional demand centers—so that leaders can isolate where growth is concentrated and where margin durability is most achievable. By connecting market sizing to the underlying drivers of adoption, the report helps strategists evaluate which applications are transitioning from pilot deployments to specification-driven purchasing, and which regions are becoming procurement hubs versus manufacturing bases. This level of segmentation is essential for companies deciding where to prioritize sales engineering resources, which customer segments deserve dedicated product variants, and how to sequence expansion without diluting operational focus.
Equally important, the research translates regulatory, materials, and supply chain intelligence into market-facing implications. With the industry navigating raw material cost thresholds, pre-doping capability licensing, and geopolitical-driven sourcing diversification, the report connects these structural forces to commercial strategy. Decision-makers gain a clearer line of sight between production economics, qualification timelines, and the competitive positioning required to win in tenders, system integration projects, and OEM design-ins. Rather than leaving readers with isolated facts, the analysis ties those factors into a coherent framework for scenario planning and capital allocation.
Competitive Possession: The Players Shaping the Laminate Transition
The laminating LIC market is not a free-for-all. It is a concentrated arena where a select group of manufacturers is actively defining format standards, scaling production, and pursuing partnerships that lock in downstream demand. The report maps this landscape through detailed company profiles, recent commercial developments, and competitive positioning analysis, giving strategists the context needed to evaluate partnership targets, benchmarking benchmarks, and threat vectors.
LICAP Technologies, Inc., based in Sacramento, California, has moved aggressively into laminate-compatible electrode processes, leveraging proprietary Activated Dry Electrode technology. In March 2026, the company secured a 40,500-square-foot industrial facility in Sacramento, tripling its space to scale production of dry electrode technology for lithium-ion capacitors and ultracapacitors supporting automotive and grid applications. Earlier, in February 2026, LICAP advanced a dry cathode electrode manufacturing collaboration with Nissan focused on scalable production processes applicable to lithium-ion capacitors and broader energy storage. These moves reflect a broader industry pull toward manufacturing approaches that reduce solvent handling, improve consistency, and align with laminate and pouch-compatible formats.
Musashi Energy Solutions Co., Ltd. (JM Energy) in Japan continues to build on its ULTIMO lithium-ion capacitor platform, offering laminate-cell, prismatic-cell, and module formats with a focus on high energy and power density hybrid supercapacitors. The company's established mass-production capacity positions it as a formidable reference point for customers seeking qualified, volume-ready solutions. In March 2025, its ESS400 Energy Storage System using hybrid supercapacitor/LIC technology received UL1973 listing for safety compliance, a milestone that underscores how certifications are becoming strategic gatekeepers in larger storage deployments.
SPEL Technologies Private Limited in India has pushed pouch (laminated) construction into higher-capacitance territory, offering thin-form-factor pouch cells up to 4500F at 3.8V with energy density advantages over standard EDLCs. This product direction illustrates the growing appetite for laminated formats that can deliver more energy in less volume, particularly where system designers need flexibility in packaging and thermal layout.
VINATech Co., Ltd. in South Korea, with facilities in South Korea and Vietnam, manufactures hybrid lithium-ion capacitors under its VPC series at 3.8V, combining EDLC and Li-ion characteristics within smart factory environments. Its emphasis on low-leakage, high-energy applications signals a market in which quality consistency and leakage performance are increasingly weighted in technical evaluations.
JTEKT Corporation and Taiyo Yuden Co., Ltd. in Japan represent additional depth in the competitive field. JTEKT produces laminated-type lithium-ion capacitors using processes similar to lithium-ion batteries, while Taiyo Yuden offers its LITHOSION series of cylinder-type lithium-ion capacitors with high-temperature capabilities up to 105°C for backup and peak power applications. The diversity of form factors and thermal specifications indicates that laminating formats compete within a broader ecosystem of product architectures, and the strategic question for each player is how to position laminate solutions against cylindrical and prismatic alternatives.
The field also includes emerging and regionally positioned players such as YUNASKO, which develops hybrid supercapacitor/LIC cells in prismatic encasement from multi-layered laminated aluminum foil with a focus on high-power modules; Shanghai Yongming Electronic Co., Ltd., a China-based manufacturer emphasizing high-performance and reliability for energy storage; GMCC Electronic Technology WUXI Ltd., which produces lithium-ion capacitors as part of an advanced energy storage portfolio; and Tecate Group in the USA, supplying lithium-ion capacitor products and hybrid solutions for industrial and power applications. Together, these companies illustrate both the global reach of laminating LIC development and the varying maturity levels that strategists must evaluate when assessing supply chain partners or potential acquisition targets.
From a concentration standpoint, the industry exhibits meaningful consolidation pressure. The market's competitive structure indicates that a relatively small number of participants command a large share of revenue. This concentration shapes pricing power, qualification bottlenecks, and the pace at which new entrants can establish credibility. For businesses evaluating the market, the implication is that ecosystem access—through partnerships, distribution channels, and co-development agreements—can be as decisive as raw manufacturing capability. PW Consulting's full study unpacks these competitive dynamics in greater depth, including how firms are differentiating on process technology, certification readiness, and application-specific performance envelopes.
Dynamics That Will Define the Forecast Window
The growth path does not operate in a vacuum. Several structural forces are actively reshaping the economics and execution risk of laminating LIC production, and they deserve close attention in 2026 strategy sessions.
- Raw material economics are becoming a gating factor for cost-competitive manufacturing. Production of lithium-ion capacitors depends on activated carbon for electrodes and lithium for pre-doping. Coconut-shell based activated carbon accounted for approximately 70.75 percent of supercapacitor-specific raw material sources in 2024, underscoring the dependence on a narrow set of feedstock pathways. At the same time, activated carbon for supercapacitor electrodes needs to stay below $10/kg for economic viability, yet current pricing around $15/kg—driven in part by biomass-derived sources—is pressuring margins. These cost dynamics make process efficiency, electrode design, and sourcing strategy central to competitiveness rather than peripheral concerns.
- Pre-doping and manufacturing licensing are lowering barriers but also reshaping competitive entry paths. In July 2023, Asahi Kasei licensed its lithium pre-doping technology to enable lower-cost LIC manufacturing using standard lithium-ion battery equipment and materials. That shift is significant because it supports a transition toward production methods that can more readily accommodate laminate formats and scale beyond niche output. For strategists, the takeaway is that technology licensing, equipment compatibility, and process standardization are now part of the competitive equation, not only cell-level performance.
- Supply chain geography and tariff exposure are forcing reallocation. Tariffs and geopolitical shifts are driving supply chain diversification for critical materials such as lithium and activated carbon in energy storage components, prompting nearshoring and alternative sourcing. Companies that rely on single-region sourcing or fixed logistics assumptions face increasing exposure, while those that build multi-source strategies and align manufacturing footprints with end-market demand can reduce qualification risk and improve resilience.
These dynamics do not operate independently. They interact with application pull, certification timelines, and regional procurement behavior. A company's ability to navigate all four simultaneously—materials cost, process licensing, supply chain diversification, and qualification readiness—will increasingly separate winners from followers. The report's full market intelligence connects these forces to the specific segments and regions where their impact is greatest, enabling a more precise reading of where risk and opportunity converge.
Why This Study Matters for 2026 Decisions
The 2026–2032 window is not merely a forecasting period; it is a planning horizon in which format choice, manufacturing strategy, and competitive positioning are being locked in. Laminating lithium-ion capacitors are moving from a promising technology category toward a mainstream option in selected energy storage and power delivery applications, and that transition is being accelerated by manufacturing advancements, certification progress, and raw-material-driven cost scrutiny. Decision-makers who wait for certainty will find themselves reacting to specifications and supply chain moves that competitors have already internalized.
PW Consulting's Worldwide Laminating Lithium-ion Capacitor Market study is designed to reduce that uncertainty. It offers historical grounding, a multi-year forecast, segmenting intelligence, and competitive analysis that together support product strategy, capacity planning, partnership evaluation, and risk assessment. The macro figures provide the directional signal; the detailed segmentation, company profiles, and industry-context analysis provide the operational map.
Because the market's segmentation splits and application-specific revenue distributions carry direct implications for where to deploy commercial resources, the full report is structured to give readers the granularity required for precise strategy work. Rather than relying on aggregate trends alone, teams can use the complete dataset to compare regional demand patterns, assess how energy-type and power-type LIC variants are contributing to overall growth, and identify which application verticals are most relevant to a given product roadmap. This is the difference between knowing the market is expanding and knowing where to place bets with confidence.
Next Steps: From Market Signal to Executable Strategy
For organizations evaluating laminating lithium-ion capacitors as a procurement source, a product platform, or an investment target, the strategic task in 2026 is to convert broad momentum into specific actions. That means aligning product specifications with the formats that end customers are beginning to prefer, stress-testing manufacturing plans against raw material cost thresholds, and mapping partnership opportunities against the companies that are actively scaling laminate-compatible processes and securing key certifications. It also means recognizing that competitive concentration and qualification barriers can shape market access just as much as technical performance.
The comprehensive PW Consulting research provides the detailed segmentation, company-level intelligence, and industry-context analysis needed to make those choices with greater precision. It is built to support board-level discussions, R&D prioritization, commercial planning, and supply chain strategy by connecting market size and forecast to the operational realities that determine execution success. The headline trajectory indicates that laminating LIC technology is entering an acceleration phase; the full study is what enables leaders to navigate that phase with discipline, focus, and competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Laminating Lithium-ion Capacitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com