

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global 3D AOI Equipment in PCB Market to Reach $2.3 Billion by 2032 with 11.2% CAGR

Navigating the High-Growth PCB Inspection Landscape: Strategic Insights into the Worldwide 3D AOI Equipment Market (2026-2032)
As the printed circuit board (PCB) industry enters a pivotal phase of technological refinement, the demand for precision manufacturing tools has never been more critical. PW Consulting is pleased to introduce our latest comprehensive study: Worldwide 3D Automated Optical Inspection Equipment in PCB Market . This report serves as a strategic compass for industry stakeholders navigating the complex dynamics between technological advancement, supply chain volatility, and escalating quality standards. With the market valuation reaching approximately 1100.0 Million USD in 2025 and projected to expand significantly through 2032, understanding the trajectory of 3D Automated Optical Inspection (AOI) systems is essential for capital allocation, product development, and competitive positioning.
This article provides a high-level overview of the market forces shaping the sector, highlighting why our in-depth research is indispensable for informed decision-making in 2026 and beyond. While we share macro-level insights here, the full report contains the granular segmentation, competitive benchmarking, and risk analysis necessary to execute robust strategies.
3D Automated Optical Inspection (AOI) Market
Market Trajectory and Growth Drivers
The global market for 3D AOI equipment in PCB manufacturing has demonstrated robust resilience and expansion over the past five years. From 2020 to 2025, the sector evolved from a niche requirement to a standard component of high-reliability assembly lines. Our analysis indicates a compound annual growth rate (CAGR) of 11.2 percent during the forecast period from 2026 to 2032. This growth is not merely a function of volume but is driven by the increasing complexity of PCB architectures, including High-Density Interconnect (HDI) technologies and the miniaturization of components.
The revenue unit for this market is tracked in Million USD, reflecting a mature yet expanding industrial ecosystem. The shift from 2D to 3D inspection capabilities is a primary catalyst, as manufacturers seek to detect defects in solder paste volume, component placement accuracy, and height measurement with greater precision. As electronic devices become more integral to automotive, telecommunications, and medical applications, the tolerance for error diminishes, necessitating advanced inspection tools. Our full report details the specific revenue thresholds expected in 2026 and beyond, providing clear targets for capacity planning.
Technological Evolution and Standards
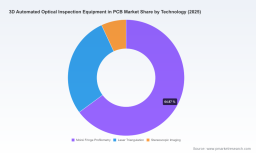
Technological innovation within the 3D AOI space is accelerating, with several key methods dominating the landscape. Among the prevailing technologies are Moiré Fringe Profilometry, which remains a cornerstone for high-accuracy height measurement, Laser Triangulation for precise surface profiling, and Stereoscopic Imaging for broader depth perception. The integration of these technologies is becoming more sophisticated, often combining multiple sensing modalities to overcome limitations such as multi-reflection suppression on shiny components like Ball Grid Arrays (BGAs) and Quad Flat No-leads (QFNs).
Furthermore, regulatory frameworks are tightening. The IPC-9252B standard, updated in 2025, now mandates 3D height measurement accuracy of ±2μm for AOI in high-reliability PCB inspection. Compliance with such standards is no longer optional for manufacturers serving automotive or medical sectors. Additionally, industry data suggests that lead times for high-resolution 3D camera modules used in AOI systems averaged 16-20 weeks in the fourth quarter of 2025 due to semiconductor shortages. This supply chain friction underscores the need for strategic inventory planning and vendor diversification, details of which are explored extensively in our full analysis.
Competitive Landscape and Key Players
The market exhibits a moderate level of concentration, with the top three companies holding a significant share of the total revenue pool. This oligopolistic structure suggests strong barriers to entry for new competitors but also offers established players substantial leverage in pricing and technology standardization. Our report provides a deep dive into the strategic moves of these market leaders, analyzing their product launches, partnership networks, and regional strengths.
Notable entities shaping the competitive environment include:
- Koh Young Technology (South Korea): Recognized for the Zenith Alpha series, this provider focuses on true 3D imaging for high-speed defect detection in Surface Mount Technology (SMT) assembly.
- CyberOptics Corporation (USA): Known for the SQ3000 3D AOI systems, their technology emphasizes multi-reflection suppression for accurate inspection of complex components.
- Viscom AG (Germany): A developer of high-volume production solutions such as the S3088 ultra for PCB assembly lines, utilizing advanced 3D sensor technology.
- Test Research, Inc. (Taiwan): Provides TR7000 series equipment, placing a strong emphasis on AI-driven analysis for solder paste and component placement verification.
- SAKI Corporation (Japan): Specializes in 3Di series systems, featuring gimbal-less camera technology for precise height measurement and defect classification.
- Mirtec Corporation (USA): Manufactures MV-3 Series systems, integrating high-resolution cameras and laser profiling for comprehensive post-reflow analysis.
- Nordson TEST & INSPECTION (USA): Offers solutions combining AOI and AXI capabilities, catering to automated inspection in high-mix production environments.
Recent activity among these firms illustrates the pace of innovation. For instance, specific product enhancements were announced throughout 2025, including AI-integrated systems capable of handling smaller components like 01005 packages and updated compliance certifications for PCB production data interoperability. These developments signal a shift toward smarter, more compliant inspection ecosystems. Readers seeking the full timeline of product launches and specific model implications should refer to the complete report.
Worldwide 3D Automated Optical Inspection Equipment in PCB Market
Regional Dynamics and Geopolitical Factors
The Asia Pacific region continues to dominate the volume of equipment deployments, reflecting the concentration of PCB manufacturing hubs in East and Southeast Asia. However, North America and Europe maintain significant shares driven by local assembly needs for defense, aerospace, and specialized industrial applications. Our segmentation analysis breaks down the volume contributions across these regions, revealing distinct growth patterns and investment priorities.
Geopolitical factors are increasingly influencing market flows. In 2025, US export controls on advanced imaging sensors under the Wassenaar Arrangement impacted a portion of 3D AOI shipments to China. Simultaneously, the European Union imposed tariffs on AOI equipment imports from non-EU countries starting January 2025, which has raised costs for German PCB assemblers and potentially incentivized local sourcing or alternative supply chains. These trade barriers create complex arbitrage opportunities and risks that require careful navigation. Our full report quantifies these regional shifts and provides scenario planning for supply chain resilience.
Pricing Trends and Investment Considerations
Cost structures within the 3D AOI market are undergoing upward pressure. The average price of 3D AOI systems for PCB increased by 8 percent year-over-year in 2025, largely attributed to optics inflation and component scarcity. Unit costs for advanced systems are converging in the range of 150,000 to 250,000 USD per unit. For capital equipment managers, this pricing environment necessitates a clear Total Cost of Ownership (TCO) analysis that accounts for maintenance, software licensing, and potential downtime due to component lead times.
Investment in 3D AOI is not merely a compliance cost but a strategic enabler for higher yield rates and reduced manual inspection labor. As end-user industries such as Consumer Electronics and Automotive Electronics demand higher reliability, the ROI on advanced inspection becomes clearer. The full study includes detailed break-even analyses and cost-benefit frameworks tailored to different production volumes.
Why This Report is Critical for 2026 Decision-Making
In a market defined by rapid technological shifts and external shocks, reliance on outdated data is a significant liability. This PW Consulting report offers actionable intelligence designed to support strategic planning for the 2026 to 2032 period. Whether you are a manufacturer evaluating procurement strategies, an investor assessing market entry opportunities, or a technology provider seeking to understand competitive threats, this document provides the foundational data required to act with confidence.
Key deliverables within the full report include:
- Historical market size data from 2020 to 2025 with verified figures.
- Forecasting models extending to 2032 with detailed revenue projections.
- Segmentation by technology, end-user, and region without exposing sensitive proprietary splits in this summary.
- Competitive profiling of key vendors including their recent developments and strategic focus.
- Analysis of external factors such as tariffs, export controls, and component supply chain delays.
The concentration of the market, with the top three players holding 52.4 percent of the share and the top five holding 68.15 percent, highlights the importance of understanding supplier relationships and potential consolidation trends. Strategic decisions regarding vendor lock-in or multi-sourcing strategies depend on nuanced insights provided in the full document.
Conclusion and Next Steps
The Worldwide 3D Automated Optical Inspection Equipment in PCB Market is poised for sustained expansion, driven by the relentless demand for quality and miniaturization in electronics manufacturing. However, realizing value in this environment requires more than general market awareness. It demands precise data on segmentation, competitive dynamics, and regulatory impacts.
PW Consulting invites industry leaders to download the full report to access the complete dataset and strategic recommendations. Our team has curated this intelligence to empower your organization to mitigate risk and capture growth opportunities in the coming years. For detailed insights into regional splits, specific technology adoptions, and end-user spending patterns, please visit the source webpage to obtain the comprehensive study.
For detailed analysis of this topic, please visit the official page: Worldwide 3D Automated Optical Inspection Equipment in PCB Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com