

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Cell Isolation Market to Grow at 13.62% CAGR Through 2032
By pmarketresearch, 2026-07-30
Cell Isolation & Cell Separation Market — Strategic Brief for 2026 Decision-Makers
Executive overview
As cell-based science accelerates from bench research to approved therapies and high-volume biomanufacturing, the cell isolation and separation market is maturing into a strategic infrastructure layer for life-science organizations. PW Consulting’s latest study (base year 2025) frames that transition with a data-driven market trajectory: from an estimated market in 2025 to a long-term forecast through 2032 driven by a compounded annual growth rate of 13.62%. The market’s historical evolution and multi-year forecast together illuminate where near-term investments will compound into sustainable advantage by 2028–2032.
Cell Isolation/Cell Separation Market
Market trajectory at a glance
-
Historical momentum: Our modeling traces a rapid recovery and expansion from the 2020 inflection point through 2025, reflecting increased adoption across research, clinical translation and early commercial cell therapy manufacturing.
Cell Isolation/Cell Separation Market -
Near-term inflection (2026): The market is set to continue its strong growth into 2026 and beyond; our forecast period (2026–2032) quantifies this momentum and scenarios for scale-up across both instruments and consumables.
Cell Isolation/Cell Separation Market -
Market structure: Concentration metrics indicate a market where a handful of global players retain meaningful share but room remains for specialist entrants and regional service providers to capture niche and adjacencies.
Why this report matters for 2026 corporate strategy
-
Investment prioritization — R&D vs. scale: The report identifies which product archetypes (automation platforms, high-throughput sorters, disposable consumables, closed-system processing) generate faster commercial ramp and recurring revenue, enabling finance and R&D leaders to prioritize capital allocation and product roadmaps.
-
M&A and partnership signal-mapping: Consolidation is selective and strategic. The study provides acquisition targets and partnership archetypes that accelerate entry into clinical GMP workflows, high-throughput sorting, or service-delivery models without overpaying for low-margin instrumentation.
-
Go-to-market optimization: With changing reimbursement and regulatory signals, device makers and CMOs must align sales channels, value propositions and pricing policies to both research and clinical buyers. Our analysis translates market growth into addressable opportunity by buyer persona and procurement cycle.
-
Regulatory & reimbursement readiness: The full research frames immediate compliance actions and payer engagement strategies that materially affect commercial timelines for clinical and commercial-scale cell processing.
What’s inside the report — practical outputs for action
-
Robust market sizing & scenarios: Bottom‑up market models (base year 2025) with sensitivity scenarios for conservative, base and accelerated adoption paths through 2032. Each scenario ties directly to key adoption drivers so leaders can stress-test investment choices.
-
Go-to-market playbooks: Tactical GTM templates for vendors and service providers, including channel selection matrices, segmented pricing playbooks, and customer-value messaging tailored for academic labs, biopharma CDMOs, and hospital/diagnostic end users.
-
Technology roadmaps and adoption curves: Comparative timelines for automation, magnetic separation, flow-based sorting and filtration modalities — including recommended trigger points for product launches and upgrade cycles.
-
Operational and manufacturing KPIs: Benchmarks for throughput, yield, cost-per-sample, and cleanroom/GMP conversion paths to guide capital equipment decisions and scale-up investments.
-
Regulatory & reimbursement playbook: Actionable guidance to align product development and submission strategies with evolving payer rules and device pathways, and checklists for GMP transition, ISO 13485 compliance and clinical trial integration.
-
Competitive landscaping and vendor scorecards: Deep, qualitative assessments (strengths, vulnerabilities, product roadmaps) of tier‑1 and emerging vendors with pragmatic partner evaluation criteria for alliances, OEM and distribution agreements.
-
M&A & corporate development toolkit: Valuation comparables, deal archetypes, integration risk checklists and a shortlist of capability gaps that acquisitions or JVs can rapidly fill.
-
Case studies & commercial pilots: Real-world examples illustrating how lab networks, CMOs and instrument vendors moved from pilot projects to recurring revenue models.
Competitive landscape — core players and strategic implications
The market is shaped by a mix of specialized innovators and diversified life‑science conglomerates. The competitive narratives below synthesize each player’s strategic posture and the near-term implications we expect to matter for 2026 planning.
-
STEMCELL Technologies Inc. — A specialist in immunomagnetic kits and automated sorters, STEMCELL’s recent acquisition of high‑throughput sorter technology accelerates its push into automated, high-purity sorting for cell therapy manufacturing. Expect bundled consumable+automation offerings and expanded service/validation support as their priority.
-
Miltenyi Biotec — A leader in clinically oriented magnetic-activated cell sorting and closed-system platforms with strong GMP pedigree. Its platforms are positioned for clinical translation; regulatory endorsements and clinical customer referenceability remain core advantages.
-
Thermo Fisher Scientific — Leverages scale and breadth across reagents, beads and instrument lines to offer end-to-end workflows for bead-based therapies. Their strategic play is integration — from consumables to manufacturing-scale workflows — and competitive pricing at volume.
-
Becton, Dickinson and Company (BD) — With flow cytometry systems and reagent suites, BD targets high-throughput, high-purity sorting for both research and translational labs. BD’s channel reach into hospitals and diagnostic labs is a powerful route-to-market for in-vitro diagnostics adjacent use-cases.
-
Danaher (Cytiva) — Focused on closed, GMP-scale processing and filtration systems, Cytiva is a natural partner for biomanufacturers scaling to commercial cell therapy batches. Its strength is process integration with bioprocessing ecosystems.
-
Merck KGaA (MilliporeSigma) , Agilent , Beckman Coulter , Terumo BCT , Lonza , Bio‑Rad — Each brings pockets of strength: reagent platforms, analytical/sorter combos, apheresis and clinical processing, or GMP-oriented consumables. Strategic partnerships and co-development agreements are the fastest way for niche vendors to scale with these incumbents.
Recent developments and regulatory backdrop
-
Notable transactions and service launches signal an emphasis on automation and outsourced services. For example, the integration of high‑throughput sorting technology into incumbents’ portfolios and the launch of commercial FACS services in regulated markets are early indicators of a shift toward service-enabled revenue models.
-
Regulatory and payer shifts materially affect unit economics. Recent policy changes that integrate certain manufacturing steps into reimbursement calculations and limited device exemptions under humanitarian pathways introduce both opportunities and constraints for commercialization timelines.
-
Quality and device certification remain table stakes. Major platforms adhere to ISO 13485 and other GMP-relevant standards — a requirement for market access in clinical programs and aggregated purchasing by CMOs and hospitals.
-
Emerging designations for manufacturing technologies that reduce process impurities are accelerating adoption in therapeutic manufacturing, and companies that can evidence lower host‑cell DNA or improved safety attributes can capture premium positioning.
Strategic imperatives for 2026
-
Prioritize consumables-led monetization: Consumables drive recurring revenue and create platform lock-in. Product leaders should design upgrade paths that combine single-use kits with subscription inventory models and validation support.
-
Invest selectively in automation that unlocks scale: Automation investments should be prioritized where they demonstrably reduce cost-per-dose, reduce variability, and shorten release cycles — criteria that matter to CDMOs and large biopharma customers.
-
Embed regulatory strategy into product design: Early alignment with GMP, ISO 13485 and payer requirements reduces time-to-market friction. Consider clinical-grade SKU roadmaps and companion validation packages for rapid customer qualification.
-
Build service and lab-network offers: Outsourced processing and commercial FACS services are accelerating. Vendors that can provide validated service networks or asset-light partnerships with third‑party labs will capture a portion of outsourced spend.
-
Use M&A to fill capability gaps: Bolt-on acquisitions in automation, high-throughput sorting, or software for process analytics can compress time-to-market and achieve scale economies faster than organic development.
-
Engage payers and policy makers proactively: Changes to reimbursement treatment for cell-manufacturing steps require proactive engagement to preserve economic models for clinical and commercial therapies.
-
Harden supply chain and manufacturing readiness: Single-use consumables and bespoke reagents require resilient sourcing and predictable manufacturing scale plans to support larger clinical and commercial customers.
Final note — where to go next
PW Consulting’s full Cell Isolation/Cell Separation Market report provides the confidential, segment-level breakdowns, vendor scorecards and model files needed to translate the headline growth trajectory into executable 12–36 month plans. This strategic brief is structured to show the depth of our analysis while preserving the detailed segmentation and financial models that are the operational tools for decisive action. For the full dataset, scenario workbooks and bespoke advisory support to convert this intelligence into a tailored market-entry or scale-up plan, please refer to the PW Consulting report page or contact our advisory team.
For detailed analysis of this topic, please visit the official page: Cell Isolation/Cell Separation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Multi-Mode Blue Laser Diode Market Poised for 8.6% CAGR Through 2032
By pmarketresearch, 2026-07-30
Multi-Mode Blue Laser Diode Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present this preview to frame the strategic choices companies must confront in 2026 as the multi-mode blue laser diode market transitions from niche growth to mainstream industrial relevance. This piece synthesizes our market modeling, competitive analysis, and actionable strategic frameworks — enough to inform board- and C-suite-level discussions while reserving the granular segment-level figures for the full PW Consulting report.
Multi-Mode Blue Laser Diode Market
Executive snapshot
- Market trajectory: The global multi-mode blue laser diode market has expanded from roughly USD 1.85 Million in 2020 to USD 2.80 Million in 2025 (base year). Our forecast projects continued expansion through the 2026–2032 horizon, with the market reaching approximately USD 4.99 Million by 2032.
- Compound growth: A 2026–2032 CAGR of 8.6% underpins this projection and highlights robust adoption across industrial, projection and high-value applications.
- Structure: Market concentration remains moderate — the top three players account for roughly a quarter of the market, with the top five near 30% — implying both established leaders and meaningful room for challengers and niche specialists.
Why this matters for 2026 strategy
2026 is a pivot year. The market has moved beyond early adopters into a phase where suppliers, system integrators, and OEMs must choose how to capture value: deepen technical differentiation, pursue scale through consolidation, or fight for pockets of premium margin in specialized applications. The 8.6% CAGR signals sustained opportunity, but success will depend on aligning go-to-market moves with structural forces — technology maturation (GaN and packaging), thermal and reliability engineering, and the evolving needs of industrial, imaging, and consumer systems.
Multi-Mode Blue Laser Diode Market
Macro dynamics shaping the market
- Technology maturation: Advances in GaN epitaxy, multi-die integration, and packaging have elevated optical outputs and lifetime characteristics. These technical gains expand the addressable application set for multi-mode blue diodes — from projection and display engines to high-precision industrial processing.
- Demand vectors: A convergence of demand from industrial processing, display/projection, medical devices, and automotive sensing is diversifying pull for higher-power multi-mode solutions. The transition from single-purpose to multi-application platforms favors suppliers who can offer modular, thermally-robust, and cost-competitive modules.
- Supply-side constraints: Critical bottlenecks include thermal management at scale, die yield for high-power multi-die assemblies, and packaging supply chains. Companies that secure proprietary packaging, optical coupling IP, or downstream system integration will have a durable advantage.
- Competitive concentration: With CR3 around 25% and CR5 around 30%, the market is neither a tight oligopoly nor a fragmented free-for-all. This structure supports targeted M&A and partnership plays to capture scale without triggering major antitrust concerns in most jurisdictions.
Competitive landscape — strategic implications
The competitive map includes established optoelectronics majors, component specialists, and laser systems companies. Each incumbent brings different strengths that dictate complementary moves for partners and competitors alike.
Multi-Mode Blue Laser Diode Market
- Nichia Corporation (Tokushima, Japan): A technology leader in GaN-based blue laser diodes with strong IP and an emphasis on high-power modules. Strategic implication: Nichia is the partner of choice for firms prioritizing supply stability and proven GaN device performance; challengers must out-innovate on integration, thermal/IP packaging, or system-level differentiation.
- ams‑OSRAM AG (Austria): Recent product launches — notably a high-output Vegalas Power series device introduced in late 2025 — demonstrate a push into projection and display markets with high optical power multi-die designs. Strategic implication: OEMs in projection and imaging should evaluate Vegalas-class devices for short-term performance gains while negotiating supply and co-development terms to lock in roadmaps.
- Sony and Sharp (Japan): Both leverage vertical integration into consumer electronics and display subsystems. Strategic implication: Expect tight coupling between diode roadmaps and system-level designs — companies supplying consumer or display OEMs should prioritize APUs and interface compatibility.
- ROHM and Panasonic (Japan): Emphasize diversified portfolios across medical and automotive domains. Strategic implication: These suppliers are attractive for regulated sectors where compliance, long lifecycle support, and conservative qualification regimes matter.
- Coherent, IPG Photonics, TRUMPF (USA/Germany): These are system-oriented or high-power industrial providers who design modules and turnkey systems around diode arrays. Strategic implication: They are ideal partners for customers seeking plug-and-play industrial solutions; they also represent potential consolidation targets for companies looking to move up the value chain.
Decision-making frameworks for 2026
We recommend executives evaluate strategic options using three interlocking frameworks:
- Value capture matrix (product vs. system): Decide whether to compete at the component level (diode IP, die manufacturing), the module level (thermal/optical packaging, driver electronics), or the system level (turnkey industrial machines, projection engines). Margins and investment scale differ materially across these layers.
- Risk-adjusted investment funnel: Allocate development and M&A capital across low-risk supply security actions (long-term offtake agreements), medium-risk integration bets (packaging and module engineering), and high-risk disruptive plays (novel diode architectures, vertical integration into systems). Use staged gates keyed to yield and MTBF milestones.
- Partner orchestration ladder: Map strategic partners by capability (epitaxy, packaging, thermal solutions, optical subsystems) and design collaborative engagement — from IP licensing to JV manufacturing — that preserves optionality while accelerating time-to-market.
Practical moves for 2026
Based on our scenario modeling and supplier landscape review, here are prioritized actions for executives planning 2026 strategies:
- Secure supply continuity: Negotiate multi-year supply and capacity reservations with primary diode manufacturers, or co-invest in packaging capacity to mitigate lead-time risk.
- Invest in thermal and packaging IP: Small-to-medium investments in thermal interface materials, active cooling control algorithms, and optical coupling reduce system-level costs and increase deployment reliability.
- Pursue selective M&A or strategic alliances: Targets include specialized packaging houses, high-yield epitaxy fabs, and module integrators to rapidly climb the value chain.
- Differentiate on integration: Focus R&D on software-driven beam control, modular optics, and serviceable module designs to lock customers into longer product lifecycles and recurring revenue streams.
- Prepare regulatory and qualification paths: For medical and automotive applications, invest early in compliance testing and long-term reliability programs to accelerate certification timelines.
What the full PW Consulting report delivers (operationally focused)
While this preview sketches strategic contours, the full report is intended as an operational toolkit for 2026 planning cycles. Key practical deliverables include:
- Granular market model with annualized revenue exercises (historical 2020–2025 base and forecasts 2026–2032) and scenario toggles to test adoption rates, price erosion, and supply constraints.
- Detailed segmentation by region, device type, and application with interactive sensitivity analysis (kept out of this preview to preserve research exclusivity).
- Supplier heatmaps and a mapped ecosystem of upstream suppliers, packaging specialists, and system integrators — annotated with capability scores and risk flags.
- Competitive dossiers on leading manufacturers, including technology roadmaps, recent product launches, patent posture, and suggested engagement strategies for each player.
- Operational playbooks: due-diligence checklists for M&A, sample term-sheet language for long-term supply agreements, and an integration timeline calibrated to production ramp profiles.
- Investment case templates and an ROI calculator tailored to common strategic options: module development, manufacturing co-investment, and system-level expansion.
Concluding view — positioning for optionality
The multi-mode blue laser diode market is entering a formative stage where technological improvements, a sustained mid-single-digit to high-single-digit CAGR, and a moderate competitive concentration converge to create differentiated pathways for value capture. 2026 will reward firms that balance near-term supply security with medium-term bets on packaging and system integration. Whether the objective is to lead on component IP, to assemble differentiated modules, or to deliver turnkey systems, the strategic imperatives are clear: secure capacity, invest in integration IP, and align M&A and partnership activity to preserve optionality.
Next steps
PW Consulting’s full Multi-Mode Blue Laser Diode Market report (base year 2025; forecast period 2026–2032) contains the detailed segment analytics, interactive models, and executable playbooks referenced above. For decision-makers preparing budgets, M&A pipelines, or product roadmaps in 2026, this report is structured to convert insight into action. Contact our research team or visit our report page to access the complete intelligence package and the downloadable operational toolset.
For detailed analysis of this topic, please visit the official page: Multi-Mode Blue Laser Diode Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hybrid Adhesives & Sealants Market — USD 8,879M in 2025; 6.12% CAGR to 2032
By pmarketresearch, 2026-07-30
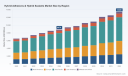
Hybrid Adhesives & Hybrid Sealants Market — Strategic Outlook for 2026 Decision Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a condensed strategic primer drawn from our forthcoming Hybrid Adhesives & Hybrid Sealants Market study (base year 2025). This brief is designed as a high-value preview for executives who must make decisive 2026 investments — in procurement, R&D, capacity, M&A, and go-to-market — while intentionally withholding the granular segment tables and country-level allocations that make up the full paid report.
Hybrid Adhesives & Hybrid Sealants Market
Market at a Glance: Trajectory and Structural Facts
The hybrid adhesives and sealants market is exhibiting steady, structurally supported expansion. Our market model pegs the global industry at approximately USD 8,879 million in 2025, growing at a compound annual growth rate (CAGR) of 6.12% across the 2026–2032 forecast window. Under the baseline scenario, the market is modeled to cross the USD 13 billion mark by the end of the forecast horizon.
Hybrid Adhesives & Hybrid Sealants Market
This is not a cyclical blip: the historical series from 2020 through 2025 shows recovery and incremental acceleration as applications in construction, transportation electrification, and electronics drive sustained demand. At the same time, market concentration metrics indicate a moderate-to-high consolidation profile with the top three players capturing a meaningful share of demand and the top five controlling well over half of total revenues — an important consideration for competitors and buyers alike when assessing negotiation leverage and innovation partnerships.
Hybrid Adhesives & Hybrid Sealants Market
What’s Driving Growth — and What Could Stall It
- Demand-side vectors: Structural demand is underpinned by building & construction renovation cycles, expanding automotive applications (notably EV battery and lightweight assembly), and increased electronics packaging complexity. Hybrid chemistries are displacing legacy silicones and polyurethanes where formulators can offer multi-performance benefits (adhesion, elasticity, low-VOC emissions).
- Supply-side constraints and raw material volatility: Input-cost dynamics are now a central strategic risk. Recent industry events — including major silicone suppliers announcing double-digit price adjustments and acute silane spot-price pressure linked to photovoltaic feedstock demand and trade barriers — have materially increased production cost uncertainty. Tariffs and supply restrictions (including very high import duties in some markets) exacerbate cost pass-through challenges and inventory management complexity.
- Regulation and sustainability: Low-VOC formulations, greener precursors, and end-of-life considerations are shaping product road maps. Buyers will reward suppliers who can demonstrate lower life-cycle impact without compromising performance.
- Technology substitution and product innovation: The field is evolving beyond simple replacements: hybrid binders and silane-modified polymers are being engineered to meet multi-material bonding demands and faster cycle times, enabling new assembly processes across transport and industrial segments.
Competitive Landscape — Who Matters and Why
The competitive map is populated by consolidated global chemical majors and specialty formulators. Leading incumbents combine broad formulation portfolios with deep channel and OEM relationships; agile regional players compete on price and custom formulation services. Below is a high-level synthesis of strategic positioning among the core players covered in our study:
- Henkel AG & Co. KGaA (Düsseldorf, Germany): Leverages strong brand equity (Loctite, Teroson) and MS-polymer technologies with solutions tailored to automotive assembly and construction. Their R&D emphasis on low-VOC, flexible adhesive systems positions them well for regulatory-driven procurement.
- Sika AG (Baar, Switzerland): A dominant presence in construction and waterproofing with the Sikaflex MS polymer family. Sika’s global distribution and project-level engineering support make them a preferred partner on large infrastructure and commercial builds.
- 3M Company (Saint Paul, US): Differentiates through product-system selling and specialty hybrid adhesive-sealant platforms optimized for UV resistance and industrial bonding. 3M’s technical channels and OEM co-development capabilities are a strategic edge.
- Dow Inc. (Midland, US): Focused play in high-growth segments such as EV battery assembly and industrial bonding, leveraging polymer science to serve electrification trends.
- H.B. Fuller, Bostik (Arkema), Wacker, RPM, and others: These players form a second tier of scale and specialization: hot-melt hybrids, marine-grade formulations, and silane-modified polymers for niche industrial and construction use-cases. Several are accelerating production investments and regional capacity to de-risk supply chains.
Collectively, the market shows active strategic repositioning: production capacity investments, next-gen launches, and targeted product introductions aimed at application-specific performance improvements. Our full report includes competitive scorecards, product pipeline analyses, and supplier risk matrices for these companies.
Recent Developments — Signals You Need to Act On
- Manufacturing scale-up: In mid-2025, a major polymer producer commenced hybrid polymer production at a new European site, signaling renewed upstream investment and potential regional supply rebalancing.
- Next-generation product launches: Late-2025 saw leading adhesive brands introduce MS polymer hybrid solutions tailored for automotive display bonding with improved flexibility and sustainability credentials — a clear indicator that OEM demands for integrated performance and regulatory compliance are accelerating product development cycles.
- Input-price shocks: Since early 2026, notable suppliers have announced significant price increases on silicone inputs after catalyst cost escalations; simultaneously, silane spot markets remain elevated due to competing demand and tariff-driven import constraints. These signals point to an elevated near-term cost base and incentivize buyers to re-evaluate sourcing strategies and hedging frameworks.
Strategic Implications for 2026 Decision Makers
For 2026 corporate planning, the interplay of robust end-market demand and heightened raw-material volatility creates both opportunity and risk. Below are prioritized strategic actions that PW Consulting recommends for market participants, from OEMs and formulators to private equity and distributors.
- Procurement and supply security: Move from spot-centric buying to a hybrid procurement model: longer-term supplier contracts tied to indexed pass-through mechanisms, strategic stockpiles for critical silane and silicone derivatives, and secondary sourcing in lower-tariff jurisdictions. Evaluate supplier performance beyond price — include delivery, formulation fidelity, and sustainability metrics.
- Pricing and margin strategy: Implement value-based pricing for performance-differentiated hybrid solutions (e.g., EV battery adhesives or architectural low-VOC sealants). Use a tiered approach to recover input-cost inflation while protecting volume through contractual escalation clauses and shared-savings clauses for cost reductions.
- R&D and product roadmap: Prioritize chemistries that reduce dependency on tariff-exposed feedstocks and catalysts susceptible to price shocks. Accelerate low-VOC, lower-silane-content formulations, and modularized product platforms that can be rapidly tailored for OEM specifications.
- Capacity investment and localization: Target regional capacity expansions where demand growth is highest and supply-chain friction is most acute. For smaller players, consider toll-manufacturing partnerships with established producers to de-risk capital spend while retaining formulation IP.
- M&A and alliances: The mid-market is ripe for consolidation and capability acquisitions — especially specialist formulators with automotive or electronics credentials. Buyers should prioritize targets with unique formulations, long-term offtake contracts, or localized manufacturing footprints.
- Commercial go-to-market: Differentiate by bundling technical service, application testing, and certification support. Use pilot programs with OEMs to secure specification wins that create switching costs and recurring revenue streams.
What the Full PW Consulting Report Delivers (Operationally Focused)
Our full market study is structured to convert insight into action. Key deliverables include:
- Bottom-up revenue model and scenario forecasts (2026–2032) with sensitivity testing under alternative raw-material and tariff scenarios.
- Competitor scorecards with product portfolios, capacity maps, and strategic positioning assessments.
- Customer segmentation and buying-behavior archetypes for construction, transportation, electronics, and industrial OEMs.
- Detailed supplier risk matrix and procurement playbook (contract templates, indexing approaches, and stock buffer calculus).
- Go-to-market & commercialization playbooks, including value-pricing models and channel optimization recommendations.
- M&A target-screening tool and integration checklists for acquirers.
Note: In keeping with our “teaser-first” approach, this preview intentionally omits the granular segment tables, regional allocations, and per-application revenue tables that substantiate the forecast and inform precise tactical decisions. Those data layers are reserved for subscribers and report purchasers to preserve competitive intelligence value.
Recommended Next Steps for Executives — A 90-Day Roadmap
- Week 1–4: Convene a cross-functional Rapid Response Team (Procurement, R&D, Sales, Finance) to stress-test current supplier contracts and identify critical single-source exposures.
- Week 5–8: Launch RFPs for alternative silane/silicone supply and secure pilot of low-silane formulations with a preferred OEM to validate performance claims and pricing elasticity.
- Week 9–12: Finalize a prioritized investment case (capex vs. toll-manufacturing) and shortlist M&A or partnership targets assisted by our target-screening framework.
Closing — Why 2026 Is a Pivotal Year
The hybrid adhesives and sealants market in 2026 sits at the intersection of accelerating end-market demand and structural supply-chain stress. Companies that move early — securing diversified feedstock access, protecting margin through disciplined pricing, and differentiating via product performance and sustainability — will gain asymmetric advantage. PW Consulting’s full study provides the quantitative foundation and tactical playbooks you need to execute with conviction. For clients ready to convert insight into near-term action, the full dataset and scenario tools unlock the precise levers required to defend margin, capture growth, and evaluate strategic transactions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Hybrid Adhesives & Hybrid Sealants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gas Barbecues Market USD 190M in 2025, 5.1% CAGR (2026-2032)
By pmarketresearch, 2026-07-30
Gas Barbecues Market 2026: Strategic Preview for Decision-Makers
Executive snapshot
As PW Consulting’s senior industry analyst, I present a strategic preview of our full Gas Barbecues Market study — a decision-focused briefing tailored for executives planning capital allocation, product roadmaps, and go-to-market moves in 2026. Between 2020 and 2025 the global market expanded steadily, and our base-year assessment (2025) positions the industry on a continuation path: a compound annual growth rate of 5.1% across the 2026–2032 forecast window, with the market moving from the low-hundreds of millions in 2020 to a projected headline figure in 2032. This preview outlines why those topline dynamics matter, what the report delivers in operational terms, and the high-conviction strategic moves companies should consider before the second half of 2026.
Gas Barbecues Market
Why the 2026 inflection matters
-
Durable, demand-driven growth: After recovering from pandemic-era shocks, the market recorded consistent year-on-year expansion through 2025. Our forecast to 2032 — framed at a mid-single-digit CAGR — signals a market where product innovation, channel evolution, and regulatory nuance will determine winners and laggards rather than macro cyclical swings alone.
Gas Barbecues Market -
Consolidation pressure: Market concentration is material. The leading three participants together control a dominant portion of revenues, and the top five extend that control significantly. For incumbent manufacturers, the implication is clear — scale, brand differentiation, and integrated channel strategies produce disproportionate margin and distribution advantages.
Gas Barbecues Market -
Technology and premiumization: Smart integration and hybrid cooking systems are shifting consumer willingness to pay. Recent product rollouts from established manufacturers underscore how connectivity and improved thermoregulation are becoming baseline expectations in premium tiers.
What our full report delivers (operational highlights)
The PW Consulting study is structured to be a working toolkit for 2026 decisions — not an academic exercise. Key operational deliverables include:
-
Validated market model with historical (2020–2025) reconciliation and a granular forecast (2026–2032) across demand scenarios. The model is built for sensitivity testing so teams can stress-test assumptions (inflation, gas price shocks, regulatory change, channel mix shifts) and quantify P&L impact.
-
Go-to-market playbooks for three strategic archetypes: premium incumbents, value-focused challengers, and specialist OEMs. Each playbook translates demand insights into SKU rationalization, recommended price ladders, distribution prioritization, and promotional cadence for the next 18–24 months.
-
Supply chain and cost-mitigation blueprints: bill-of-material benchmarks, critical-supplier mapping, and contingency plans for stainless-steel and electronics supply — including estimated cost exposure points and levers that materially affect gross margin.
-
Regulatory and compliance matrix: a practical guide to state- and municipal-level permit regimes, safety standards that affect installations and warranties, and proactive design adjustments to limit compliance costs and product recalls.
-
Competition dossiers and M&A watchlist: strategic profiles for established and emerging players, with acquisition-priority scoring and integration risk assessments tailored to buyers seeking inorganic growth.
-
Commercial impact simulations: revenue and margin projections for alternative strategic moves (e.g., new smart-grill launch, entry into rental or commercial foodservice segments, vertical integration of selected supply lines).
Competitive landscape — players to watch
Our competitive analysis synthesizes product portfolio breadth, manufacturing footprint, brand equity, and innovation cadence. Notable market participants include long-standing brands with strong domestic manufacturing and distribution networks, premium specialists focused on outdoor kitchen ecosystems, and firms investing in hybrid/connected cooking experiences. Recent industry developments illustrate the pace of innovation and marketing intensity:
-
Weber — introduced a refreshed Spirit lineup in early 2025 and followed with smart-enabled Genesis and Spirit models in 2026, signaling a concerted push into connected features and user experience platforms.
-
Napoleon — launched promotional and new-product activities in 2026, reinforcing the importance of seasonal event-driven marketing in the premium segment.
-
Multiple manufacturers — including established outdoor-equipment players — continue to expand portability and hybrid-fuel offerings to bridge consumer preferences across convenience and culinary versatility.
For executives weighing competitive moves, our report maps each major player against three strategic dimensions — product differentiation, channel reach, and manufacturing leverage — providing actionable priority areas for investment or defensive measures.
Supply chain, materials, and manufacturing considerations
Product durability and brand promise hinge on materials and supplier control. Industry-standard construction relies heavily on 304 stainless steel for longevity and heat performance, making stainless-steel sourcing and price volatility a primary supply-side risk. Electronics for ignition and connectivity introduce a second risk layer: lead times and quality assurance for control modules and sensors.
-
Sourcing strategies that matter in 2026: dual-sourcing for critical stainless grades, preferred supplier agreements with volume commitments, and investment in nearshoring or regional logistics hubs to protect time-to-market during peak seasons.
-
Manufacturing levers: modularization of grill platforms, platform-based product families to reduce SKU complexity, and targeted automation investments in welding and finishing to lower labor-driven variability in yield and cost.
Regulatory and safety dynamics
Regulation is no longer peripheral. State and local safety codes — particularly those referencing fire-safety standards and appliance installation permits — are actively shaping installation practices and product liabilities. Two practical touchpoints for manufacturers and distributors:
-
Fire safety standards that influence design and documentation requirements for portable and installed grills, and that increasingly appear in state-level adoption of national fire protection guidance.
-
Local permitting regimes for gas appliance installation, which impose inspection and certification steps that affect after-sales service models and warranty terms.
Our report converts these regulatory inputs into actionable product and service design changes — for example, labeling and instruction enhancements, aftermarket inspection partnerships, and modular features that simplify certified installation.
Strategic imperatives for 2026 decision-making
Based on the combined market, competitive, supply, and regulatory intelligence, PW Consulting recommends five high-impact strategic moves to prioritize in 2026:
-
Invest selectively in connectivity and sensory controls to capture premium price realization while structuring software-as-a-service pathways to create recurring revenue.
-
Rationalize SKUs to reduce manufacturing complexity and focus marketing spend on a narrower set of high-margin configurations that align with channel-specific demand drivers.
-
Strengthen supplier agreements for 304 stainless steel and certification-validated ignition systems; consider hedging or long-term purchasing to insulate margins from commodity shocks.
-
Build a compliance-centric after-sales ecosystem: partner with regional installers, expand certification documentation, and design warranty terms that reflect local regulatory constraints.
-
Pursue M&A selectively: prioritize targets that offer either channel access (e.g., specialized commercial accounts) or cost synergies (e.g., regional manufacturing capacity) rather than those seeking marginal geographic share.
How to use the full PW Consulting study in your 2026 planning cycle
Use the report as a decision-support system across three planning horizons:
-
Immediate (0–6 months): validate SKU rationalization, fix critical supplier terms, and sequence product launches for the 2026 selling season using our channel-playbook templates.
-
Near-term (6–18 months): implement manufacturing efficiency initiatives, pilot smart-product monetization models, and negotiate regional installation partnerships to lower warranty risk.
-
Strategic (18–36 months): evaluate inorganic growth candidates against our M&A scoring framework and align long-term R&D investments to projected premiumization trends captured in the forecast scenarios.
Final perspective and next step
The gas barbecues market in 2026 presents a classic opportunity set: steady, predictable topline growth combined with strategic inflection points driven by technology, channel consolidation, and compliance complexity. Our full report equips decision-makers with the granular tools to convert those market dynamics into repeatable growth and margin improvements — from operational playbooks to quantified investment cases.
To access the full methodology, detailed scenario outputs, and the complete competitor and supplier appendices that we intentionally reserve for the full study, please visit the PW Consulting report page. The companion dataset and model license are provided to purchasing clients so executive teams can run bespoke sensitivity analyses aligned to corporate risk tolerances and investment horizons.
For detailed analysis of this topic, please visit the official page: Gas Barbecues Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Metabolic Cart Market Poised for 7.3% CAGR Through 2032
By pmarketresearch, 2026-07-30
Metabolic Cart Market 2026: Strategic Preview for Decision Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a high-level, practice-oriented preview of our full Metabolic Cart Market study. This briefing is designed to inform executive decisions in 2026 by synthesizing the market’s macro trajectory, competitive posture, regulatory influencers, and the practical levers that determine commercial success. It intentionally surfaces analytical depth while withholding tabulated, segment-level particulars—our full report contains the granular forecasts and proprietary splits that will validate and operationalize the strategies summarized here.
Metabolic Cart Market
Market Snapshot: Macro Trajectory and What It Means
The metabolic cart market reached a clear inflection by the 2025 base year, with global revenues approaching the low‑hundreds of millions (USD, base year 2025). Our horizon analysis projects sustained expansion through 2032 at a compounded annual growth rate of 7.3%, with the market moving from the 2025 base to a substantially larger industry by the end of the forecast window. This growth is neither evenly distributed nor random—it is driven by converging forces in clinical adoption, portable diagnostics, and an expanding set of applications from cardiopulmonary exercise testing to metabolic assessment in sports science and nutritional medicine.
Metabolic Cart Market
Two structural takeaways for 2026 planning:
Metabolic Cart Market
- Scale matters: market concentration is meaningful—top-three vendors account for a clear majority of market share, and top-five players further consolidate leadership. This creates both barriers and opportunities for challenger brands depending on chosen routes to market.
- Growth pockets exist at the intersection of portability and reimbursability: devices and service bundles that can be deployed outside the traditional lab—yet still qualify for reimbursement—will disproportionately capture incremental demand.
Competitive Dynamics — Tactical Implications
The market is populated by legacy device specialists and newer niche entrants. Several incumbent and emerging vendors define the competitive landscape:
- Parvo Medics (Salt Lake City): A long-standing clinical and research standard-bearer. Their flagship solution has become a de facto benchmark in many institutions—strengths include clinical validation and entrenched user familiarity. For incumbents, the challenge is leveraging brand equity while modernizing usability and integration capabilities.
- COSMED (Rome): Strong in cardiopulmonary exercise and resting metabolic assessment with proven product lines. European engineering pedigree and breadth across CPET and RMR positions COSMED well where integrated testing is required. Strategic focus should be on ease of deployment and cloud-enabled analytics to expand appeal.
- MGC Diagnostics (Saint Paul): Offers breath-by-breath systems aimed at stress testing. Their value proposition is around clinical precision and systems integration—an advantage in hospital cardiology and pulmonary labs.
- KORR Medical Technologies (Salt Lake City): Focused on indirect calorimetry and RMR solutions with explicit reimbursement messaging. Their assertion of CPT-code coverage illustrates the leverage available when reimbursement pathways are secured.
- Schiller AG and Geratherm Medical AG (Switzerland & Germany): Both offer integrated cardiopulmonary platforms that include metabolic analysis—useful where multi-modality diagnostics are bundled.
- Iworx Systems (Dover): Serves research and teaching markets with modular metabolic measurement tools—an anchor in academia and early-stage clinical research.
Strategic implication: vendors that combine validated measurement accuracy, simplified operation, and a clear economic case (reimbursement or demonstrable downstream revenue) will win procurement committees’ attention in 2026.
Regulatory and Reimbursement Dynamics — Risk and Opportunity
Regulatory events have direct commercial impact: a Class I recall issued in 2024 for sample-line components on a leading platform underscores the market sensitivity to safety events. Device manufacturers must therefore prioritize component traceability, accelerated corrective actions, and robust post-market surveillance to maintain clinical trust and avoid market disruption.
On the reimbursement front, the recognition of certain metabolic tests under existing CPT codes provides a near-term demand catalyst—particularly for providers who can monetize point-of-care metabolic assessments. Companies that align product messaging, clinical evidence and billing guidance will ease buyer friction and accelerate adoption.
Technology & Product Trends to Watch in 2026
- Portability: A notable shift toward portable metabolic analyzers is underway. Portable devices enable field-based sports testing, home-based nutritional assessment, and decentralized research studies—broadening total addressable market when accuracy and usability thresholds are achieved.
- Software and connectivity: Integration into existing EMR, cloud analytics, and automated reporting determine long-term stickiness. Buyers increasingly value platforms that reduce technician time and improve longitudinal tracking.
- Modular ecosystems: Products that can be configured across resting, exercise, and ICU contexts reduce procurement friction and improve utilization rates.
- Quality and safety engineering: Component-level robustness—especially for consumables and sample pathways—has moved from cost center to competitive differentiator after high-profile safety recalls.
Practical Strategic Priorities for 2026
For private equity, vendors, and hospital procurement leaders, the following priorities should inform 2026 plans:
- Prioritize reimbursable use-cases: If your offering can be positioned to fall under established billing codes, accelerate evidence generation and payer engagement. Even partial reimbursement materially lowers the buyer’s total cost of ownership.
- Invest in portable and hybrid solutions cautiously: Portability unlocks new markets but requires matching lab-grade fidelity. A two-track R&D investment—one to optimize a high-throughput lab platform, another to miniaturize with validated accuracy—is recommended.
- Strengthen post-market surveillance and supply-chain traceability: Build rapid-response protocols and visible QA processes to mitigate recall risk and preserve brand trust.
- Make software the differentiator: Prioritize automated calibration, user workflows, and longitudinal analytics. Software-enabled features increase switching costs and provide recurring revenue opportunities.
- Pursue targeted partnerships over broad distribution: Hospitals, sports federations, and research consortia can be high-value anchors. Pilot programs that demonstrate clinical and operational ROI will outpace broad, unfocused reseller strategies.
- Consider M&A selectively: The market’s concentration suggests value in bolt-on acquisitions that add vertical capabilities (e.g., cloud analytics, consumables, or reimbursement support services) rather than horizontal duplication.
What the Full PW Consulting Report Delivers
Our complete market study expands this preview into an operational playbook. Key deliverables include:
- Validated market sizing and a 2026–2032 forecast model built on the 2025 base year, showing where investable growth will materialize across product archetypes and clinical applications.
- Vendor scorecards that combine technical performance, installed base, distribution reach, and service economics—designed to inform vendor selection and M&A screening.
- Risk mapping covering regulatory exposures, component supply bottlenecks, and recall scenarios with mitigation pathways that buyers and suppliers can implement.
- Go-to-market playbooks tailored to three buyer segments (hospitals/labs, sports/performance providers, and research/academia) with pricing and contract structures that reflect procurement realities in 2026.
- Actionable KPIs and dashboard templates for commercial teams: conversion metrics, utilization thresholds that justify capital purchases, and post-sales service SLAs to protect retention.
Note: This preview omits the granular regional, application and product split tables, vendor-level unit and revenue forecasts, and downloadable financial models included in the full report. Those detailed exhibits are critical for transaction diligence and budgeting—and are accessible via our publication portal.
Closing Assessment — The 2026 Competitive Imperative
By 2026 the metabolic cart market will reward clarity of value proposition and operational excellence. Firms that combine validated clinical accuracy with easy-to-deploy workflows, a defensible reimbursement story, and resilience against safety-related disruptions will be favored by buyers. Market concentration signals that partnerships and targeted acquisitions can be powerful accelerants for growth, but execution must be accompanied by strong post-market evidence and service capabilities.
PW Consulting’s full report equips executives with the granular inputs, vendor benchmarking, and tactical playbooks required to convert the market’s growth into durable revenue streams and strategic advantage. For organizations planning capital allocation, product roadmaps, or M&A activity in 2026, this study is intended to be the decision-grade foundation.
For detailed analysis of this topic, please visit the official page: Metabolic Cart Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cephalosporin Market — USD 17,700M in 2025, 3.0% CAGR to 2032
By pmarketresearch, 2026-07-30
Cephalosporin Market 2026 — Strategic Briefing for Executive Decision-Making
Executive snapshot
The global cephalosporin market is transitioning from a commodity antibiotic landscape into an arena shaped by supply‑chain concentration, regulatory repricing and targeted product innovation. Using a 2025 base year, PW Consulting’s proprietary modeling captures a market that reached approximately USD 17,700 Million in 2025 and moves forward at a steady compound annual growth rate (CAGR) of roughly 3.0% across our 2026–2032 forecast window. Under our baseline scenario, total market value expands materially by 2032, reflecting a combination of moderate demand growth, lifecycle substitution from older molecules, and premiumization driven by combination therapies and hospital‑procured sterile injectables.
Cephalosporin Market
Why this report matters for 2026 strategic choices
- Capital allocation — Prioritise investments in assets and geographies that hedge tariff and raw‑material concentration risks while capturing the upside from higher‑margin sterile injectable and late‑generation cephalosporins.
- Supply‑chain strategy — Decide between vertical integration, dual‑sourcing, or long‑term procurement contracts to neutralize concentrated intermediate supply and tariff exposure.
- Portfolio management — Balance generics volume plays (which continue to dominate the market) with selective innovation and fixed‑dose or combination therapeutic entries that command premium pricing and faster hospital adoption.
- M&A and partnerships — Use focused inorganic plays to secure capacity, regulatory dossiers and regional market access in an environment where three players control a meaningful share of the market (CR3 ~35%; CR5 ~42%).
- Regulatory readiness — Align site investments and clinical/regulatory timelines with accelerated review pathways for priority antimicrobials in the US and China.
Market dynamics: the structural forces shaping 2026
Three structural dynamics dominate the near‑term landscape.
Cephalosporin Market
- Supply concentration of key intermediates. A small number of Chinese production clusters continue to account for the bulk of 7‑ACA and 6‑APA intermediates and related fermentation outputs. This concentration creates meaningful pricing and reliability leverage for those suppliers and translates into tangible operational risk for global purchasers.
- Trade and tariff pressure. Since early 2025 expanded tariff measures have raised landed costs for some Chinese API and intermediate imports. In practical terms, increased duties have created new landed‑cost thresholds that procurement teams must bake into tender pricing and long‑term sourcing decisions.
- Regulatory and reimbursement context for generics and new entries. Generics remain the backbone of the market (more than half of total volume is supplied by off‑patent molecules), driven by hospital procurement policies and established formularies. At the same time, regulators in major markets are prioritising reviews for novel cephalosporin combinations addressing antimicrobial resistance, which creates windows for premium product launches if manufacturers can demonstrate GMP‑compliant production and robust clinical dossiers.
Recent industry developments (signals you cannot ignore)
- May 2026 — Regulatory green light: A US regulatory authority approval for a cefepime + beta‑lactamase inhibitor combination underscores the market’s movement toward combination therapies for complicated Gram‑negative infections; this approval illustrates both the clinical and commercial upside for differentiated products that address resistance.
- 2025–2026 — Capacity and licensing activity: Targeted plant inaugurations and new approvals in Asia signal demand for injectables and reinforce the strategic importance of regional manufacturing footprints in the face of trade friction.
Strategic implications and recommended plays for 2026
Executives should treat 2026 as a year to rebalance risk against optionality. Tactical and strategic moves with the highest expected value include:
Cephalosporin Market
- Sourcing diversification or nearshoring. Move beyond single‑cluster dependency by securing alternative suppliers in India, Europe or inland Chinese provinces, or by structuring joint ventures that provide priority access to intermediates.
- Dual‑track manufacturing investments. Invest selectively in modular sterile injectable capacity that can be scaled for both cephalosporins and other beta‑lactam classes; modularity reduces capital risk and accelerates time‑to‑market for high‑margin hospital products.
- Lifecycle management for generics. Use tender intelligence to identify generics with durable hospital demand and low price elasticity; pair volume supply agreements with low‑cost manufacturing to defend margin corridors.
- Premiumization via differentiated combinations. Prioritise R&D and regulatory filings for combination antibiotics that can access priority review pathways and command differentiated reimbursement in hospital formularies.
- M&A and capability buys. Pursue bolt‑on acquisitions to acquire GMP dossiers, sterile fill capabilities or regional market access—particularly where incumbent players hold concentrated shares but lack full end‑to‑end integration.
- Procurement and pricing playbook. Redesign procurement contracts to include tariff‑pass‑through clauses, indexation to intermediates, and co‑investments in supply security to stabilise long‑term costs.
Competitive landscape — who to watch and why
The competitive field is a mix of large diversified multinationals, speciality European manufacturers, and high‑volume Indian and Chinese API producers. Several profiles are especially instructive for strategic planners:
- Aurobindo Pharma Ltd. (Hyderabad, India) — A major producer of semisynthetic cephalosporin APIs and intermediates with integrated fermentation and chemical synthesis capabilities; a natural partner or acquisition target for companies seeking secure API capacity.
- Lupin Ltd. (Mumbai, India) — A GMP‑certified manufacturer of both APIs and finished formulations; competitive on volume supplies for established generics.
- Cipla Ltd. and Sun Pharmaceutical Industries Ltd. (Mumbai, India) — Large diversified players with USFDA‑approved sites; strength in both oral and injectable portfolios and notable presence in hospital procurement channels.
- Orchid Pharma (Chennai, India) and Wockhardt Ltd. (Mumbai, India) — Specialist suppliers focused on parenteral APIs and sterile formulations; strategically significant for hospital injectable markets and combination product filings.
- Teva, Pfizer, GSK, Novartis, Merck — Global firms that balance branded innovation with generics scale; they are gatekeepers for certain regulated markets and can redistribute supply rapidly through global networks.
- Chinese manufacturers (e.g., Shandong Lukang, Qilu) — High‑volume API and intermediate producers that influence global pricing and supply rhythms; their operation and policy environment underpin the market’s short‑term supply dynamics.
Market concentration metrics indicate an industry that is neither highly fragmented nor dominated by a single incumbent: the top three firms hold roughly 35% of sales, and the top five about 42%. That structure favors strategic consolidation where target companies add capability or geography rather than pure scale.
What the PW Consulting Cephalosporin market study delivers
This report is engineered for decision‑makers who need both strategic context and implementable tactics. Included modules are:
- Granular market sizing and forecast models (2020–2032) with alt‑scenarios and sensitivity testing around commodity pricing, tariff shocks and accelerated regulatory approvals.
- Supply‑chain risk maps that identify single‑point‑failure suppliers, tariff exposure corridors and hedging levers for procurement teams.
- Regulatory tracker for major agencies (US FDA, NMPA, EMA) and an assessment framework for how approvals or priority reviews change commercial timelines.
- Commercial opportunity matrices by product archetype (legacy oral generics, sterile injectables, late‑generation cephalosporins, and novel combinations) designed to guide R&D and go‑to‑market resource allocation.
- Competitive benchmarking dossiers for the leading 15 manufacturers with capability scoring (API fermentation, semisynthesis, sterile fill, regulatory approvals) and acquisition attractiveness indices.
- A procurement and pricing playbook tailored for hospital tender environments, including contract clauses, indexation approaches and risk‑sharing templates for customers and suppliers.
- Deal origination lists and quick‑win M&A targets scored on strategic fit, regulatory cleanliness and capacity uplift potential.
- Interactive Excel models and executive dashboards enabling rapid scenario analysis for Board presentations and investment committees.
Note: while the public briefing above outlines core themes and high‑level figures, the report contains detailed splits by generation, application, region and route, as well as cell‑level forecasts and company‑level revenue estimates. These granular datasets and benchmarking tables are available exclusively in the full report and associated data pack.
How to use this intelligence in 90 / 180 / 360 days
- 90 days: Run a supply chain audit to quantify exposure to concentrated intermediates and renegotiate top‑tier supplier contracts to include contingency supply clauses.
- 180 days: Evaluate two strategic options—(a) a targeted joint venture in an alternative manufacturing hub, or (b) retrofit of modular injectable capacity—and model P&L outcomes under tariff stress scenarios.
- 360 days: Execute a priority regulatory filing for one differentiated product or a small bolt‑on acquisition to secure API capacity and accelerate hospital adoption pathways.
Conclusion — the 2026 mandate
For executives, 2026 is the year to convert awareness of structural risk into concrete strategic positioning. The cephalosporin market offers predictable top‑line growth and attractive cash generation for the right owners, but that potential is contingent on active management of supply concentration, tariff exposure and regulatory timing. PW Consulting’s market study provides the integrated analytics and the executable playbook to inform capital allocation, commercial tactics and M&A decision‑making. The overview presented here is intended to demonstrate the depth of our analysis—full granular breakouts, scenario inputs and company‑level financials are provided in the complete report and data package.
To access the comprehensive dataset, interactive models and the full competitive dossiers that underpin these conclusions, please visit our report page or contact PW Consulting’s Cephalosporin Practice Lead for a briefing and executive deck.
For detailed analysis of this topic, please visit the official page: Cephalosporin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pool Chemical Market: USD 1,565.89M in 2025, projected 4.51% CAGR (2026–2032) — PW Consulting
By pmarketresearch, 2026-07-30
Pool Chemical Market 2026: Strategic Trailer for Executive Decision-Making
As PW Consulting’s lead industry analyst, I present a concise strategic briefing that translates our full Pool Chemical Market study into immediate, board‑level implications for 2026. This piece previews the report’s most consequential findings—market scale, growth trajectory, competitive dynamics, and actionable playbooks—while intentionally withholding the granular segmented tables and model outputs reserved for the full report. Think of this as the executive trailer: enough depth to inform decisions and provoke questions, not the complete dataset.
Pool Chemical Market
Macro picture: scale and trajectory
The global pool chemical market has moved from recovery into a steady expansion phase. Using 2025 as our base year, the market is projected to grow at a compound annual growth rate (CAGR) of approximately 4.51% through the 2026–2032 forecast window. After a post‑pandemic rebound, the market shows resilient structural demand drivers—ongoing residential pool installations, retrofit cycles in aging commercial facilities, and accelerating adoption of digital dosing and automation systems—supporting mid‑single‑digit growth into the next decade.
Pool Chemical Market
For executives planning 2026 capital allocation, the message is clear: the market is large enough to justify capacity and product investment, yet growth is moderate enough that share gains, margin improvement and cost management will be decisive in determining winners. Our full study provides the time‑series market size trajectory, scenario overlays and sensitivity to key inputs; in this summary we frame the strategic implications of those dynamics.
Pool Chemical Market
Why this matters for 2026 decisions
- Investment timing: Moderate, predictable growth favors targeted capital deployment—capacity optimization, automation, and selective M&A—over indiscriminate greenfield expansion.
- Margin leverage: With wholesaling and private‑label activity increasing, firms that control formulation, distribution and pricing can convert modest volume gains into outsized margin improvements.
- Supply‑chain resilience: Recent price volatility and logistical frictions have shown that supply stability and feedstock sourcing strategies are value drivers as important as top‑line growth.
- Regulatory compliance and ESG: Tighter environmental controls and product stewardship obligations are raising the cost of doing business—and creating opportunities for eco‑differentiated products.
Competitive landscape: consolidation, private labels, and technology entrants
The market exhibits a medium concentration profile: the top three firms account for just under half of market share, and the top five collectively hold a clear but not dominant majority. That structure favors both scale players seeking incremental consolidation and nimble specialists who can exploit product differentiation or channel niche plays.
Key strategic moves we tracked in 2025–2026 illustrate two concurrent themes: incumbents doubling down on private‑label and proprietary formulations to lift margins, and new/adjacent entrants pushing product innovation and digital services. Illustrative developments include:
- Leading distributors expanding private‑label offerings and reporting chemical category margin improvement—evidence that channel control matters.
- Technology providers launching integrated dosing and monitoring systems that blur the line between chemical supplier and service provider, enabling recurring revenue models.
- Established equipment and water‑treatment companies augmenting portfolios with eco‑friendly chemistries through strategic acquisitions.
Profiles of core competitors are included in the full report. Highlights you should know now: distributors with deep retail footprints and proprietary brands bring a distribution premium; manufacturers of core chlorine products retain pricing influence tied to chlor‑alkali cost cycles; and specialty chemical firms enjoy pricing power when paired with validated performance or regulatory advantage.
Recent events shaping 2026 strategy
- Commercial signals: Q1 and mid‑year earnings commentary from major distributors has pointed to higher chemical volumes and structural margin gains from private‑label lines—an important confirmation of the channel shift we modeled.
- Product innovation: New professional water‑management systems combining automated dosing, real‑time monitoring and integrated service contracts are changing buying criteria for commercial operators and higher‑end residential customers.
- M&A and portfolio moves: Acquisitions of eco‑chemical startups by equipment and service incumbents demonstrate an acceleration of sustainability‑driven product roll‑outs and vertical integration.
- Supply pressures: Weather, energy costs and port congestion have intermittently tightened chlorine and shipping markets, producing short‑term price movements that underscore the need for procurement playbooks.
- Regulatory overlay: Tariff actions and tightened environmental discharge guidance increase compliance costs—particularly for players reliant on complex international supply chains.
Operational risks and input cost outlook
Raw material and logistics risk are the primary near‑term operational vulnerabilities. Chlor‑alkali input cost behavior and transport frictions have been the most visible drivers of margin pressure; while feedstock indices have stabilized in recent months, episodic price upticks remain possible under energy or production disruptions. Tariff measures and tighter discharge regulations in major markets add a structural cost burden for firms with long, import‑dependent supply chains.
In practice, this means procurement teams must adopt layered risk management—hedging where feasible, establishing multi‑sourcing strategies, and building inventory playbooks for peak seasons—while commercial teams protect margin through smarter contract structures and value‑added services.
What’s inside the full PW Consulting report (practical tools for 2026)
The full study is designed to be operationally actionable for strategy, commercial, procurement and R&D teams. Key deliverables include:
- Market sizing and trend models with base year 2025 and a 2026–2032 forecast, plus scenario sensitivity to feedstock pricing and regulatory tightening.
- Competitive intelligence dossiers and capability maps for the leading players across distribution, manufacturing and specialty chemistry.
- Price‑to‑win matrices and commercial playbooks tailored to residential and commercial channels, including private‑label economics and margin modeling.
- Supply‑chain risk heatmaps and procurement strategies (multi‑source decision trees, forward purchasing thresholds and inventory optimization heuristics).
- Innovation trackers and go‑to‑market roadmaps for eco‑friendly chemistries, dosing automation, and service‑based monetization.
- Regulatory compliance checklists and cost impact assessments for major jurisdictions, plus an emissions/discharge compliance calculator for corporate reporting teams.
We intentionally omit the granular region‑by‑type‑by‑application tables here; those segmentation matrices and the underlying datasets are included exclusively in the paid report to preserve the competitive value of the insights.
Strategic recommendations for 2026 (prioritized)
- Protect and grow margins: Accelerate private‑label formulations and contract offerings that lock in long‑term, higher‑margin customer relationships—especially in retail and professional service channels.
- Invest selectively in automation: Prioritize partnerships or product roll‑outs that bundle chemicals with monitoring/dosing to convert commodity buyers into subscription service clients.
- Hedge and diversify supply: Implement a tiered procurement strategy: secured core supply agreements for key chlorinated feedstocks, a secondary pool of regional suppliers, and targeted inventory buffers ahead of peak seasons.
- Pursue bolt‑on sustainability targets: Use M&A or licensing to acquire validated eco‑friendly chemistries—these generate premium pricing and reduce regulatory downside.
- Optimize channel mix: Rebalance commercial vs residential focus based on gross margin contribution and service potential—details and quantitative thresholds are in the full model.
How PW Consulting’s outputs accelerate implementation
Boards and executive teams will find immediate value from three deliverables in the full report: (1) a market model calibrated for capital and M&A planning, (2) a competitor moves tracker to inform defensive/offensive actions, and (3) procurement and product commercialization playbooks that translate scenario results into 90‑, 180‑ and 360‑day actions. These are designed to be directly plugged into annual planning cycles and M&A diligence processes.
Next steps
If your 2026 plans involve capacity investment, private‑label expansion, vertical integration or an eco‑innovation pathway, the full PW Consulting Pool Chemical Market report contains the granular segmentation, price elasticity matrices and competitor benchmarking you will need to execute. Request the full report to access the detailed regional/type/application breakdowns, datasets, and the tactical templates referenced above.
For a bespoke briefing tailored to your strategy team—covering scenario stress‑testing against your supply chain, or a defensible M&A target short‑list—contact our Pool Chemical Market practice at PW Consulting. The window to translate the current market momentum into sustainable advantage is open; the right combination of procurement discipline, product differentiation and channel orchestration will determine who captures outsized returns in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Pool Chemical Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Colocation Market Set to Expand at 14.4% CAGR through 2032
By pmarketresearch, 2026-07-30
Colocation Market 2026: A Strategic Preview for Enterprise Decision‑Makers
As organizations accelerate digital transformation and scale AI workloads, colocation has re-emerged as a strategic infrastructure choice. PW Consulting’s latest Colocation Market study (base year 2025, forecast 2026–2032) synthesizes five years of historical observation with forward-looking scenarios to equip executives with the evidence they need to make high‑stakes decisions in 2026. The market we modelled grew from roughly USD 47.3 million in 2020 to USD 104.3 million in 2025 and, under a central scenario, is projected to reach about USD 265.5 million by 2032 — representing a compound annual growth rate of 14.4%. Those headline numbers frame a market that is substantial, accelerating, and strategically differentiated by workload, sovereignty needs, and interconnection intensity.
Colocation Market
Why this study matters in 2026
-
Timing matters: Capital cycles, capacity ramp lead times and long procurement windows mean that decisions made in 2026 will determine latency, resilience and TCO outcomes for the next decade.
Colocation Market -
Workload differentiation: The contours of “colocation” are widening — from classic enterprise rack deployments to hyperscale campuses optimized for dense AI appliances. A one‑size procurement approach now carries execution risk.
Colocation Market -
Regulatory and energy dynamics: New reporting and interconnection rules, changes to grid policy and data‑sovereignty mandates have turned site selection and contract terms into regulatory as well as technical decisions.
What the report delivers — operationally useful outputs
This study is built as a practical playbook for strategists, real‑estate and IT procurement teams, and private capital managers. The full report goes well beyond high‑level forecasts and includes the following actionable modules:
-
Transparent market sizing and scenario engine — base case, upside (accelerated AI adoption), and downside (grid constraints) scenarios with Monte Carlo sensitivity around key variables.
-
Vendor and site scorecards — standardized, exportable templates that rank providers across interconnection density, AI readiness, sustainability credentials, contractual flexibility and time‑to‑service metrics.
-
Site selection toolkit — a weighted scoring model for prioritizing markets that balances latency, power availability, regulatory risk, and cost inputs. Includes a decision tree for colocating edge versus core workloads.
-
TCO and contract negotiation playbook — integrated capex/opex templates, power procurement strategies and a negotiation checklist that highlights clauses typically overlooked in colocation agreements.
-
Workload mapping and migration patterns — recommended packaging of workload types (including high‑density AI clusters) into deployment archetypes with migration timelines and dependency maps.
-
M&A and investment playbook — criteria for bolt‑on acquisitions, greenfield vs. buy decisions, and a private equity checklist that aligns IRR sensitivity with construction and permitting risks.
-
Regulatory overlay and sustainability metrics — compliance matrices for new reporting regimes and a set of KPIs to include in RFPs to track PUE, water usage effectiveness and embodied carbon.
-
Interactive dataset and dashboards — an online portal with downloadable model inputs, provider footprints and market access matrices to drive workshop sessions and vendor negotiations.
Note: this article intentionally highlights the report’s structure and tools without reproducing the full segmentation tables and granular regional shares. Those datasets, our provider benchmarking scores and model inputs are available in the full report and interactive portal.
Market dynamics — what’s driving growth and risk in 2026
-
AI and high‑density compute: The principal demand vector is densifying compute deployments. Providers that have invested in high‑power distribution, flexible floor space and chilled water systems are capturing disproportionate demand.
-
Interconnection and latency: Network effects are real — sites with deep interconnection ecosystems accelerate cloud on‑ramp and partner integrations for enterprises with hybrid architectures.
-
Data sovereignty and regulated workloads: Government mandates in multiple jurisdictions are forcing a segment of regulated workloads to remain onshore. This structural requirement reshapes procurement priorities and increases local colocation demand.
-
Policy and reporting: Regulatory changes requiring operational transparency (e.g., mandatory reporting of energy and water performance) are creating new compliance costs and differentiators for sustainable operators.
-
Supply constraints: Construction unit costs and skilled labor availability are limiting near‑term capacity expansion in key markets. These supply dynamics underpin pricing resilience despite efficiency gains.
-
Market concentration: The competitive landscape shows meaningful concentration at the top — the combined share of the largest three and five providers indicate an environment of regional incumbency plus room for specialist entrants.
Competitive landscape — who matters and why
The report profiles global and regional leaders and assesses how each player’s footprint, product strategy and recent investments position them against enterprise needs:
-
Equinix — The world’s largest carrier‑neutral colocation provider, notable for interconnection density and accelerating AI‑ready capacity. Recent expansion into new national markets highlights a strategy that blends sovereignty controls with hybrid multicloud tooling.
-
Digital Realty — A capacity‑centric operator with a large wholesale and enterprise colocation estate. Recent market entries in Europe underscore a continued emphasis on global scale and sustainability reporting.
-
Iron Mountain — A trusted provider for regulated industries, now scaling hyperscale campuses suited for AI workloads while preserving their compliance heritage.
-
QTS — Positioning around carrier neutrality and large‑scale capacity with a focus on North America and Europe, and messaging that leans into AI demand capture.
-
CoreSite — Strong in high‑density facilities and interconnection services, with thought leadership that frames colocation as the connective layer for hybrid IT.
-
Vantage Data Centers — Scalable wholesale and campus strategies that are tailored for hyperscale and enterprise customers needing modular expansion paths.
-
CyrusOne, Switch, NTT and ST Telemedia — Each brings differentiated strengths: enterprise reliability, cloud/edge integration, Asia‑Pacific reach, and regional interconnection ecosystems respectively.
Recent corporate moves included several targeted expansions and sustainability disclosures; these actions demonstrate that operators are contesting both capacity and policy leadership. For buyers, provider selection increasingly requires a dual assessment of physical capability and policy alignment.
Strategic implications and recommended responses for enterprise leaders
Organizations can translate the study’s insights into practical steps in 2026. The report recommends a prioritized set of actions:
-
Classify workloads by sovereignty, latency sensitivity and compute density. Treat AI/HPC clusters and regulated workloads as separate procurement tracks with distinct acceptance tests.
-
Use scenario TCO models to drive negotiation thresholds. Factor in power pass‑through, demand charges and escalation clauses tied to regulatory reporting requirements.
-
Embed sustainability and operational transparency into RFPs. Insist on measurable KPIs, audit rights and timelines for decarbonization commitments.
-
Lock in interconnection and cloud on‑ramps where latency or partner ecosystems matter; conversely, prioritize wholesale campus economics where raw capacity and scale are the driver.
-
Plan capex and release schedules against construction lead times; where speed matters, evaluate pre‑built or brownfield options to de‑risk go‑to‑market timelines.
-
Establish a governance cadence to monitor policy changes and grid interconnection developments that can materially affect site viability.
How to extract maximum value from the full PW Consulting study
This article is a strategic preview — a clear view of the market’s arc without publishing the report’s granular segmentation tables and vendor scorecards. The full study offers the complete dataset, downloadable models, and interactive dashboards that allow you to:
-
Run bespoke market share and location scenarios using your internal workload assumptions;
-
Download provider benchmark matrices and the negotiation playbook to accelerate RFP cycles;
-
Access the regulatory compliance matrix and sustainability KPI templates for inclusion in contracts and board reporting.
In 2026, colocation is not simply about space and power — it is a lever for enterprise agility, regulatory compliance and cloud‑adjacent performance. PW Consulting’s Colocation Market study equips leaders to convert market momentum into high‑confidence decisions. For the complete dataset, provider scoring sheets and interactive modeling tools, access the full report and portal to run tailored scenarios against your operating constraints and strategic priorities.
For detailed analysis of this topic, please visit the official page: Colocation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Car Bumpers Market — USD 16,500M in 2025, 4.2% CAGR through 2032
By pmarketresearch, 2026-07-30
Car Bumpers Market 2026: Strategic Preview for Decision-Makers
Executive Snapshot
As the automotive industry shifts toward lightweighting, circularity, and differentiated aftermarket demand, the global car bumpers market is navigating steady expansion and structural change. PW Consulting’s latest analysis—anchored on a 2025 base year and a 2026–2032 forecast horizon—finds the market moving from roughly USD 14.1 billion in 2020 to about USD 16.5 billion in 2025, with a projected continuation to just over USD 22.0 billion by 2032 at a compounded annual growth rate (CAGR) of 4.2% for the 2026–2032 period (USD, Million). This trajectory masks important inflections in material choices, aftermarket dynamics, and regulatory pressure that will determine winners and losers in 2026 and beyond.
Car Bumpers Market
Why this matters for 2026 strategic planning
- Timing of capital deployment: A moderate, predictable CAGR creates a window for measured capital investment in tooling, recycling infrastructure, and material switching. Companies that deploy selectively in 2026—targeting modular manufacturing and adaptable tooling—will avoid stranded assets if demand composition shifts.
- Supply-chain repositioning: With polypropylene (PP) entrenched as the dominant bumper polymer, shifts in polyolefin feedstock pricing and recycling policies directly influence cost and design choices. Buyers and suppliers must lock in flex contracts or vertical partnerships to stabilize input cost exposure.
- Aftermarket and retrofit economics: The aftermarket continues to be a margin pool with different economics from OEM supply; differentiating channel strategies between painted CAPA-style parts, heavy-duty steel bumpers, and premium offroad offerings will be crucial.
- ESG and regulatory timing: Emerging regulatory signals—especially in Europe and select North American jurisdictions—intensify the need for circular design and take-back capabilities. 2026 is the inflection year for executing pilot recycling programs at scale.
Market Trajectory: Key Numbers to Guide Strategy
Use the following macro touchpoints as strategic guardrails when evaluating 2026 initiatives: the market expanded materially from the early-2020s through 2025, and our forecast shows a continuation of measured growth into 2032 under a 4.2% CAGR assumption for the 2026–2032 period. These aggregated figures are intentionally highlighted to support top-level budgeting, headcount planning, and portfolio prioritization. For granular regional, application, and type splits—critical when sizing investments by geography or product line—the full dataset and working models in the complete report are essential.
Car Bumpers Market
Segment & Supply-Chain Dynamics (What’s changing)
- Material mix evolution: Polypropylene remains the workhorse for bumpers—valued for low density, impact resistance, and cost efficiency—supporting lightweight vehicle design. At the same time, pockets of demand for steel, aluminum, and composites persist where durability, repairability, or premium positioning matter.
- Raw-material cost signals: Regional price movements for polypropylene and propylene feedstock softened in late-2025, reflecting weaker packaging and automotive demand in some Asian markets. Volatility in feedstock markets will determine the relative competitiveness of polymer-based versus metal bumpers through 2026.
- Recycling and circularity: Policy and commercial initiatives are accelerating closed-loop experimentation. Programs piloted in Europe and select North American locales show OEMs and recyclers converting end-of-life bumpers into reprocessed PP feedstock—an enabler of recycled-content mandates and a vector for sustainable differentiation.
- Aftermarket segmentation: The aftermarket is bifurcating: one track emphasizes low-cost CAPA/OEM-style painted replacements for mass-market vehicles; the other targets performance, offroad, and heavy-duty segments where steel and specialty finishes command premium margins and brand loyalty.
Competitive Landscape: Who to Watch
The market is populated by distinct competitor archetypes: specialized heavy-duty fabricators, precision offroad manufacturers, premium aftermarket OEMs, and parts suppliers focusing on painted body panels. The following firm-level perspectives highlight strategic postures relevant to 2026 planning:
Car Bumpers Market
- Buckstop Truckware (Prineville, OR) — An established manufacturer of heavy-duty aftermarket steel and winch bumpers for domestic truck platforms. Recent capacity shifts, including a facility relocation completed in mid-2026, signal a readiness to increase throughput and accelerate aftermarket delivery times. For incumbents and investors, Buckstop’s move highlights the importance of flexible U.S. fabrication capacity to serve regional aftermarket demand.
- Expedition One (Ogden, UT) — Focused on precision-built 4x4 offroad bumpers and overland accessories, this profile represents the premium, experience-driven aftermarket segment. Products in this category prioritize modularity and accessory integration (winches, lighting, sensors), offering higher margins but requiring close alignment with enthusiast channels and digital community engagement.
- Fab Fours (Lancaster, SC) — A U.S.-based manufacturer of premium steel truck and SUV bumpers and rock sliders. Their positioning underlines a continued domestic appetite for rugged, durable bumpers where repairability and heavy-duty performance trump lightweighting—an important counterbalance to polymer-focused OEM strategies.
- Partify (Warren, MI) — A supplier of painted aftermarket body parts and CAPA/OEM-style replacements, Partify exemplifies the mass-replacement channel with service-level differentiation (warranties, paint match, logistics). Partnerships between such suppliers and insurer/repair ecosystems represent a durable demand channel.
Across these archetypes, strategic choices in 2026 should focus on: manufacturing flexibility, aftermarket channel partnerships, and the ability to integrate recycled-content materials without compromising quality or warranty promises.
Regulatory & Sustainability Forces
- Policy acceleration in 2025–2026: European regulatory bodies released policy options for boosting plastic recycling in the automotive sector in late 2025. Complementary municipal-level moves—such as bans on automotive plastics to landfills—are catalyzing commercial recycling initiatives and local take-back schemes.
- Corporate recycling initiatives: Industry actors and recyclers have moved from pilots to scaled programs, collecting damaged or end-of-life PP bumpers and reprocessing them into new material streams—an operational reality that lowers the barrier to recycled-content mandates and can create a new feedstock arbitrage if collection logistics are optimized.
- Design-for-recycling: The next wave of competitive differentiation will be product designs that ease disassembly, reduce mixed-material joins, and enable high-value polymer streams—actionable levers for 2026 product development roadmaps.
Practical Implications & Strategic Playbooks for 2026
PW Consulting’s analysis translates market dynamics into decision-ready plays across four archetypal stakeholders:
- OEMs: Adopt modular bumper architectures that allow a single vehicle platform to accept different material inserts or reinforcement options. Prioritize validated recycled-content formulations and pilot closed-loop sourcing agreements in 2026 to smooth compliance risk and brand exposure.
- Tier Suppliers & Fabricators: Invest selectively in dual-capacity lines (polymeric injection/compression molding plus metal fabrication) and flexible finishing cells. Lock in feedstock flexibility—either through hedged contracts or strategic JV with recyclers—to maintain margin resilience if polymer costs rebound.
- Aftermarket & Specialty Brands: Differentiate via service—warranties, rapid-fit painted parts, and accessory ecosystems. For premium offroad and heavy-duty suppliers, prioritize direct-to-consumer community engagement and accessory modularity to capture higher lifetime value.
- Private Equity & Strategic Investors: Look for consolidation targets with strong aftermarket channels or proprietary supply-chain relationships (e.g., take-back/recycling contracts). M&A in 2026 will be most accretive where synergies reduce material cost exposure or expand aftermarket distribution networks.
What the Full PW Consulting Report Delivers (Practical, Executable)
Our comprehensive study goes beyond headline forecasts to deliver operational tools for 2026 implementation, including:
- Detailed demand models by geography, application, and material type (with customizable scenarios and sensitivity to feedstock price swings).
- Unit-cost and margin models for polymer versus metal bumpers across production scales.
- Supply-chain heatmaps and supplier risk matrices identifying single-source exposures and logistics choke points.
- Competitive dossiers, including capability audits and M&A readiness assessments for leading aftermarket and OEM suppliers.
- Regulatory scenario planning and compliance playbooks for recycled-content mandates and landfill diversion rules.
- Go-to-market strategies for aftermarket entrants and OEM sourcing tender templates for recycled-content procurement.
The public preview intentionally omits in-report tables that break down regional, application, and type-specific revenues and market shares—these are included in the full database and interactive models that PW Consulting provides to paying clients to support investment memoranda, sourcing RFPs, and product roadmaps.
Final Strategic Takeaways for 2026
- 2026 is a year to operationalize flexibility: invest in manufacturing adaptability and supply relationships rather than heavy, single-technology capital outlays.
- Material strategy is a profit lever: aligning design, procurement, and recycling partnerships will reduce cost exposure and meet tightening policy demands.
- Aftermarket remains a durable margin pool—differentiate by channel, service, and integration with repair ecosystems.
- Regulatory and municipal actions are moving the economics of recycling; early movers in take-back and recycled-content will gain both cost and reputational advantage.
Next Steps
For 2026 decision cycles, PW Consulting recommends commissioning the full report and accompanying model set to convert these strategic imperatives into executable project plans. Our full deliverable includes the granular segmentation, live spreadsheets, supplier scorecards, and board-level briefings that boards and executive teams need to authorize capital, M&A, and strategic partnerships with confidence.
For detailed analysis of this topic, please visit the official page: Car Bumpers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PID Sensors Market to Reach USD 304.7M by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-30
PID Sensors and Detectors Market — Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a concise, decision‑focused preview of our new PID (Photoionization Detection) Sensors and Detectors Market study. The attached research is designed to arm executives, product strategists, and investors with the practical intelligence they need to make confident 2026 choices — from R&D priorities and go‑to‑market planning to M&A and compliance investments. This preview demonstrates the analytical depth and actionable framing you will find in the full report while deliberately withholding the detailed segment tables and proprietary breakouts that drive tactical execution.
PID (Photoionization Detection) Sensors and Detectors Market
Market trajectory at a glance
PID sensor and detector demand has moved beyond niche environmental projects and is now a staple of industrial safety and continuous environmental monitoring programs. Our analysis uses 2025 as the base year and covers historical performance from 2020–2025 and a forecast horizon through 2032. The market expanded from roughly USD 120.5 Million in 2020 to an estimated USD 195.0 Million in 2025, and our central forecast shows compound annual growth of 6.5% over the 2026–2032 window, bringing the market to approximately USD 305 Million by 2032. That trajectory reflects accelerating adoption across compliance‑led monitoring, remote infrastructure deployments, and replacement cycles driven by upgraded sensor performance.
PID (Photoionization Detection) Sensors and Detectors Market
Why this research matters for 2026 decisions
- Timing for investment and product bets: With mid‑single‑digit CAGR and clear pockets of accelerating demand, 2026 is a window to scale production capacity, secure component supply, or fast‑track next‑gen lamp and electronics improvements that yield step changes in field performance.
- Regulatory and standards risk management: VOC exposure limits, evolving EU regulatory frameworks, and calibration accreditation expectations are changing procurement criteria — companies that map product specs to compliance outcomes will win enterprise contracts.
- Commercial prioritization: The market is neither fragmented chaos nor monopolized dominance — strategic consolidation and targeted partnerships can produce disproportionate returns if timed to forecast inflections.
- Operational resilience: Battery life and low‑power electronics matter for portable/handheld use cases. Operational plans that ignore electronics and calibration economics will underperform in real deployments.
Market dynamics that will shape corporate strategy
- Regulatory push drives procurement: Stricter VOC exposure thresholds and chemical registration requirements have pushed large industrial buyers and environmental agencies to prioritize PID‑based solutions for real‑time verification and compliance documentation.
- Standardization and calibration: ISO 17025 accreditation requirements for calibration labs raise the bar for vendors offering calibration services and after‑sales support. Buyers increasingly evaluate total cost of ownership, not just sensor purchase price.
- Technology differentiation: Recent product introductions emphasize ppb‑level sensitivity, longer lamp life, and sensor‑to‑sensor repeatability. Those attributes reduce field recalibration and improve data quality — critical differentiators for high‑value contracts.
- Infrastructure integration: Remote monitoring architectures in oil & gas, petrochemical, and large chemical plants are integrating PID sensors into SCADA and cloud analytics for plume tracking and leak localization. That trend elevates systems integrators as strategic channel partners.
- Power and portability constraints: Achieving ppb sensitivity while maintaining battery life requires trade‑offs in electronics design. Solutions that optimize ultra‑low power consumption while preserving analytical performance will capture a growing share of portable and handheld segments.
Competitive landscape — what to watch
The market is characterized by a compact set of established vendors, several of which have invested heavily in product upgrades and brand initiatives over the past 18–24 months. Top vendors account for a material share of the market, with the three largest players occupying roughly a third of sales and the top five just over half — a structure that encourages both competitive R&D and opportunistic consolidation.
PID (Photoionization Detection) Sensors and Detectors Market
- ION Science Ltd (Fowlmere, UK) — Recognized as a market leader in PID sensor manufacture, ION Science has broadened its portfolio and launched a new brand to sharpen innovation positioning. Their moves signal continued focus on performance‑oriented detectors and multi‑gas platforms for compliance monitoring.
- Alphasense (Chorleywood, UK) — Alphasense’s PIDX range targets sensor‑to‑sensor repeatability and extended lamp life, directly addressing OEM concerns about calibration burden. Their technology roadmap suggests a push into higher‑volume OEM deployments.
- AMETEK MOCON (Brooklyn Park, USA) — A key OEM supplier with newly introduced piD‑TECH sensors designed for industrial safety and environmental monitoring. AMETEK’s product refreshes highlight the competitive focus on accuracy and field usability.
- PID Analyzers, LLC (HNU, Sandwich, USA) — Offers PID‑branded analyzers across air, water, and process monitoring, maintaining a stable role in specialized applications and channel partnerships with system integrators.
- RKI Instruments (Hayward, USA) & WatchGas (UK) — Both firms round out the competitive map with differentiated portable/multi‑gas detector offerings that embed PID functionality for VOC detection in safety and industrial use cases.
Recent product launches and brand initiatives through 2024–2025 have intensified competition around lamp life, repeatability, and integration readiness. For example, AMETEK MOCON’s introduction of a next‑generation piD‑TECH sensor and Alphasense’s PIDX range are explicit attempts to capture the OEM upgrade cycle. ION Science’s new brand and multi‑gas detector introductions further demonstrate how incumbents are broadening their addressable market.
Strategic implications and recommended actions for 2026
- Manufacturers & OEMs: Prioritize modular, drop‑in designs and standardized calibration interfaces. Investments in lamp technology, sensor repeatability, and low‑power electronics will reduce buyer switching costs and lengthen product lifecycles.
- Channel & system integrators: Build calibration and data‑management services into contracts; create bundled offerings that combine PID hardware, accreditation‑compliant calibration, and analytics for regulatory reporting.
- End‑users (industrial, governments): Treat PID procurement as a system purchase — include lifecycle calibration costs, data quality requirements, and integration timelines in RFPs. Prioritize vendors that can demonstrate ISO 17025 calibration pathways and proven field performance.
- Investors & corporate development: Look for M&A opportunities that close gaps in calibration networks, software analytics, or low‑power electronics capabilities. Given market concentration, small bolt‑on acquisitions can rapidly scale addressable offerings and margin profiles.
- Product strategy teams: Use multi‑scenario roadmaps to balance near‑term portable/handheld upgrades with mid‑term fixed‑monitoring deployments tied to remote‑monitoring architectures.
What PW Consulting’s full report delivers (practical highlights)
Our full PID Sensors and Detectors Market report is structured to convert insight into action. Key deliverables include:
- Validated market sizing and a 2026–2032 forecast model, with sensitivity analysis and scenario variants that reflect regulatory and technology risk.
- Go‑to‑market playbooks for OEMs, distributors, and systems integrators that include pricing archetypes, contract structures, and channel economics.
- Vendor benchmark and capability heatmap — assessing product performance (sensitivity, lamp life, repeatability), calibration support, and integration readiness.
- Supply‑chain and component risk analysis, with recommendations to de‑risk lamp and electronics sourcing through strategic supplier agreements or dual sourcing.
- Regulatory impact assessment and compliance cost templates that map VOC/REACH/CLP scenarios to procurement and lifecycle costs.
- Operational models for calibration and after‑sales services, including a guide to building ISO 17025‑aligned calibration networks or partner ecosystems.
- M&A and investment shortlist with rationale and integration playbooks focused on targeting capability gaps rather than geographic expansion alone.
Each section is accompanied by pragmatic templates — procurement checklist, RFP language, total cost of ownership calculator, and deployment sequencing guidance — enabling rapid translation from insight to boardroom decisions.
How to apply this intelligence in 2026 — five practical moves
- Embed calibration economics into every product business case: require TCO analyses that include ISO 17025‑compliant calibration to avoid post‑purchase surprises.
- Prioritize low‑power, ppb‑capable product lines for pilot deployments in remote monitoring; these pilots will validate upgrade economics for larger fixed installations.
- Pursue strategic OEM partnerships that offer drop‑in replacements and clear upgrade paths to lock in channel partners and reduce long‑term churn.
- Align R&D roadmaps with regulatory timelines: calibrate feature release schedules to expected compliance deadlines in key verticals to capture early procurement cycles.
- Evaluate targeted acquisitions that instantly add calibration capacity, analytics software, or low‑power electronics expertise rather than green‑field investment.
Final note — what this preview omits and where to go next
This preview intentionally demonstrates the report’s analytic sophistication while withholding the granular segment tables, region‑by‑application splits, and proprietary vendor scoring that we use to recommend specific tactical actions. Those segment‑level figures and supplier scorecards are the core proprietary assets of the full PID Sensors and Detectors Market study and are available in the complete report.
If your 2026 planning requires precise addressable market sizing by channel, product variant, or application, or if you want bespoke scenario runs calibrated to your product roadmap, PW Consulting can provide the full dataset, vendor heatmaps, and customized advisory support. Our team will help translate the market forecast into procurement specs, product roadmaps, and M&A playbooks that deliver measurable returns within 12–24 months.
For detailed analysis of this topic, please visit the official page: PID (Photoionization Detection) Sensors and Detectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com